Calculate 2026 interstate relocation tax savings (NY/NJ/MA/CT to FL/NC/SC/GA/NH), survive NYS 183-day & Convenience of the Employer audits (Form IT-203-B), and navigate DC-MD-VA & NJ-PA commuter reciprocity.
1. Interactive Simulators & Statutory Guides in This Family
NYC, NY, NJ, CT & MA Sales & Restaurant Tax Calculator
Computes exact state, city, and MCTD sales taxes, NYC $110 clothing exemption rules, NJ 3.3125% Urban Enterprise Zone rates, CT 7.35% restaurant meal tax, and pre-tax tip totals.
NY / NJ Cross-Border Commuter Tax Credit Calculator
Simulates New York non-resident tax withholding, the New Jersey Schedule NJ-COJ credit for taxes paid to NY, and the $15,000 NJ property tax deduction.
New York vs. Florida Tax Residency & Audit Savings Simulator
Quantifies annual and 10-year compounded state/local income and capital gains tax savings when relocating domicile from NYC, NY, NJ, CT, or MA to Florida.
2. Flagship Interactive Simulator
New York vs. Florida Tax Residency & Audit Savings Simulator
Quantifies annual and 10-year compounded state/local income and capital gains tax savings when relocating domicile from NYC, NY, NJ, CT, or MA to Florida.
3. Table 1: 2026 East Coast Interstate Commuter Reciprocity & Non-Resident Source Taxation Rules
| Jurisdiction / Corridor | Exemption / Threshold | 2026 Statutory Rate | Governing Statute | Planning & Audit Note |
|---|---|---|---|---|
| NY ↔ NJ / CT Commuter Corridor | No Reciprocity! Taxed by NY on NY-Source Work | Resident Credit on NJ-1040 Sch. COJ / CT-1040 | 20 NYCRR 132.18 (Convenience of Employer Rule) | Moving NYC → Jersey City/Hoboken saves 3.876% NYC Resident Tax |
| DC ↔ Maryland ↔ Virginia (Capital Beltway) | Full Tri-State W-2 Wage Reciprocity! | Taxed 100% by Domicile State (File DC Form D-4A) | D.C. Code § 47-1801.04 & Va. Code § 58.1-342 | Moving Bethesda MD → Fairfax VA saves 3.20% MD county tax |
| New Jersey ↔ Pennsylvania (Delaware River) | Full W-2 Wage Reciprocity (Form REV-419) | Warning: Philadelphia 3.44% Non-Res Wage Tax Applies! | N.J.S.A. 54A:9-17 & Phila. Code § 19-1500 | PA state waives 3.07% for NJ residents, but Philly never waives 3.44% |
| Massachusetts ↔ New Hampshire Border | No Reciprocity! MA Taxes Boston Office Days | 100% Remote Work in NH = 0% State Income Tax | 830 CMR 62.5A.1 (MA Non-Resident Apportionment) | Hybrid workers apportion W-2 days worked in NH vs. MA |
| NY / NJ / MA → Florida / Carolinas Domicile Move | Must Break 5 Primary Domicile Factors + <184 Days | File FL Declaration of Domicile (Fla. Stat. § 222.17) | NYS DTF Non-Resident Audit Guidelines | Every partial day in NY (except travel transit) counts as 1 NY day |
Pablo Cirre Gómez
Corporate database analyst, financial publisher, and digital economist with 20+ years of experience building quantitative business intelligence, fiscal simulation engines, and corporate registries (Co-Founder of East Corp Capital and Legia.es). Accredited in Business & Marketing Systems (COM708_3, IFC297_2), lecturer at the International Graduate School (EIP) and Cámara de Comercio, and lead architect of our 24 interactive IRS, NYS DTF, NJ Treasury, and Federal Reserve calculators.
Enrique Zarza (José Enrique Rodríguez Zarza), Esq.
Practicing litigation, banking, real estate, and corporate compliance attorney admitted to the Illustrious Bar Association of Madrid (ICAM No. 68.400) with over 25 years of professional practice. Law Degree & Master in Legal Practice (Universidad de Granada), Executive Management (San Telmo Business School), pioneer in digital banking contracting (CaixaBank / CTI Soluciones), Founder of ICIRED, former Managing Director of the Judicial Default Registry (RIJ) partnered with the General Council of Spanish Lawyers (Abogacía Española), and Co-Founder of Legia.es and East Corp Capital.
NYC, NY, NJ, CT & MA Sales & Restaurant Tax Calculator →Read 2026 Companion Study
New York vs. Florida Tax Residency & Audit Savings Simulator →Read 2026 Companion Study
2026 Cross-Border Commuter Tax Credits, Telecommuter Convenience Rules & I-95 Relocation Arbitrage
Master 2026 interstate wage reciprocity agreements, resident credit schedules, municipal wage taxes (NYC, Yonkers 16.75%, Philadelphia 3.75%), and 183-day statutory residency audits. Governing schedules verified across NYS Convenience of the Employer Rule · NJ Schedule A Credit · PA-NJ Reciprocity (REV-419) · DC-MD-VA Form D-4A · NY/MA → FL Domicile Audit. Use the master 16-jurisdiction reference matrix below to compare effective rates, statutory forms, and phase-out cliffs from Maine to Florida:
| East Coast Jurisdiction & Financial Hubs | 2026 Statutory Brackets, Caps & Surcharges | Primary Tax Forms & Legal Authority | Interactive Simulator |
|---|---|---|---|
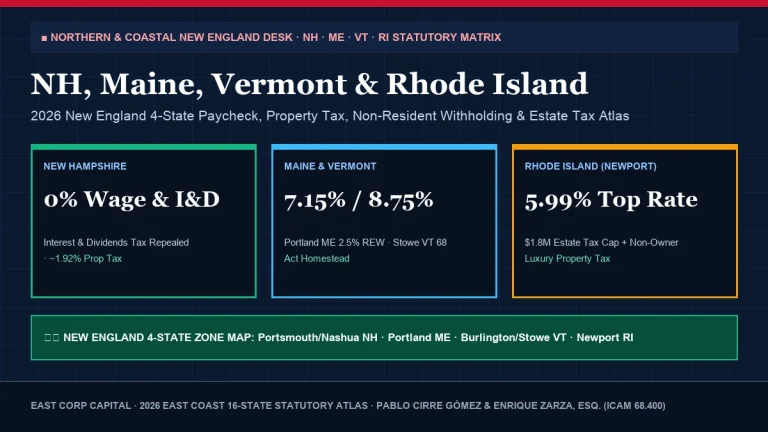
| Maine (ME) · Portland / Kennebunk | 5.80% – 7.15% Income · 1.09% Prop · $2.20/$500 Transfer | Form 1040ME · RETTD · 2.5% Non-Res Withholding | Launch Simulator → |
| New Hampshire (NH) · Portsmouth / Nashua | 0% Wage Tax · 0% I&D (Repealed) · 1.86% Prop · 1.50% RETT | NH DP-10 (Repealed) · Form CD-57-S (75 bps each) | Launch Simulator → |
| Vermont (VT) · Burlington / Stowe | 3.35% – 8.75% Income · 1.83% Prop · 1.47%–3.62% PTT | Form IN-111 · Form HS-122 Homestead · Act 181 PTT | Launch Simulator → |
| Massachusetts (MA) · Boston / Cambridge | 5.0% Base + 4.0% Surtax (>$1.08M) · $2M Estate Credit | Form 1 / 1-NR · M-706 · Boston $3,890 Res. Exemption | Launch Simulator → |
| Rhode Island (RI) · Providence / Newport | 3.75% – 5.99% Income · Taylor Swift Non-Owner Surcharge | Form RI-1040 · $2.30/$500 Conveyance + Tier 2 Luxury | Launch Simulator → |
| Connecticut (CT) · Greenwich / Stamford | 2.00% – 6.99% Income · 6.99% PTET · 0.75%–2.25% Mansion | Form CT-1040 · Form CT-1065/CT-1120SI · OP-236 | Launch Simulator → |
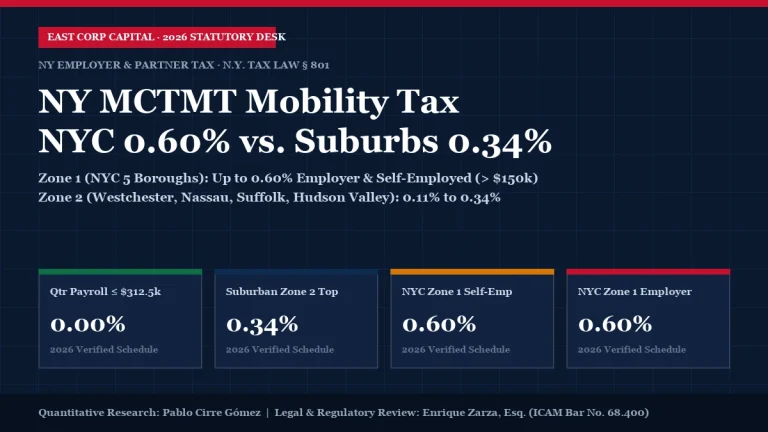
| New York (NY & NYC) · 5 Boroughs / Suburbs | 4.0%–10.9% NYS + 3.876% NYC · 16.75% Yonkers · $7.16M Estate | IT-201 / IT-203 · ACRIS RPTT / TP-584 · CEMA § 255 · UBT | Launch Simulator → |
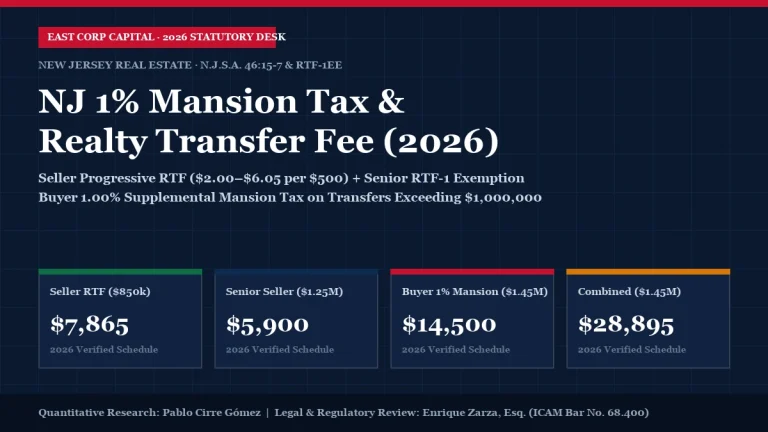
| New Jersey (NJ) · Bergen / Hoboken / Short Hills | 1.40% – 10.75% Income · 2.23% Prop · 1% Buyer Mansion Tax | NJ-1040 · GIT/REP-3 Exit · RTF-1 / RTF-1EE · IT-R Class C/D | Launch Simulator → |
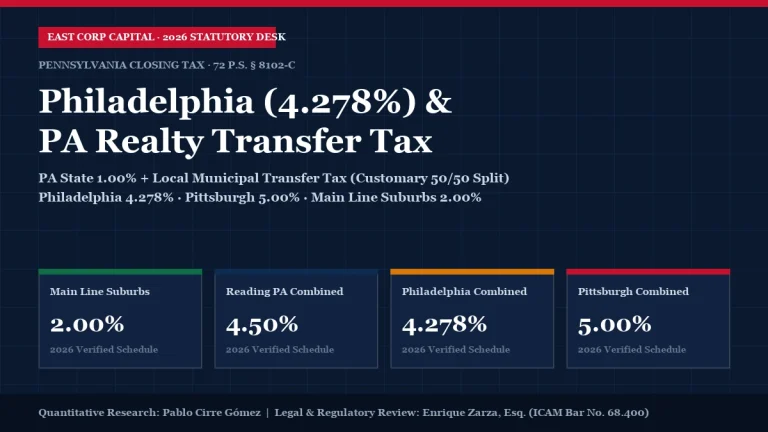
| Pennsylvania (PA) · Philadelphia / Main Line | 3.07% Flat PA + 3.75% Philly Wage · 4.278% Philly Transfer | PA-40 · REV-1500 (4.5%/12%/15%) · REV-419 Reciprocity | Launch Simulator → |
| Delaware (DE) · Wilmington / Sussex Coast | 2.20% – 6.60% Income · 0% Sales Tax · 4.0% Transfer · $300 LLC | 8 Del. C. § 503 Assumed Par Value · Form RTT-TAX | Launch Simulator → |
| Maryland (MD) · Bethesda / Baltimore / Annapolis | 2.00% – 5.75% State + 2.25% – 3.20% County Piggyback | Form 502 · SDAT Homestead 10% Cap · $5M Estate + 10% Inh. | Launch Simulator → |
| Washington, D.C. · District of Columbia | 4.00% – 10.75% Income · 2.20%–2.90% Recordation/Transfer | Form D-40 · Form D-4A Non-Resident Reciprocity · $90,550 Homestead | Launch Simulator → |
| Virginia (VA) · Arlington / Fairfax / Loudoun | 2.00% – 5.75% Income · $4.15–$5.33/$100 Vehicle Car Tax | Form 760 · PPTRA Vehicle Subsidy · 5.75% VA PTET | Launch Simulator → |
| North Carolina (NC) · Charlotte / Raleigh-Durham | 3.99%–4.25% Flat Income · ~0.82% Prop · $2/$1,000 Excise | Form D-400 · $100 Annual LLC Report · 0% Estate Tax | Launch Simulator → |
| South Carolina (SC) · Charleston / Hilton Head | 0% – 6.20% Income · 4% Primary vs. 6% Second-Home Ratio | SC1040 · Act 388 100% School Tax Exemption · $3.70/$1,000 Deed | Launch Simulator → |
| Georgia (GA) · Atlanta / Buckhead / Cobb County | 5.19%–5.39% Flat Income · $130k Age 65+ Retirement Exclusion | Form 500 · Cobb County 62+ 100% School Property Tax Exemption | Launch Simulator → |
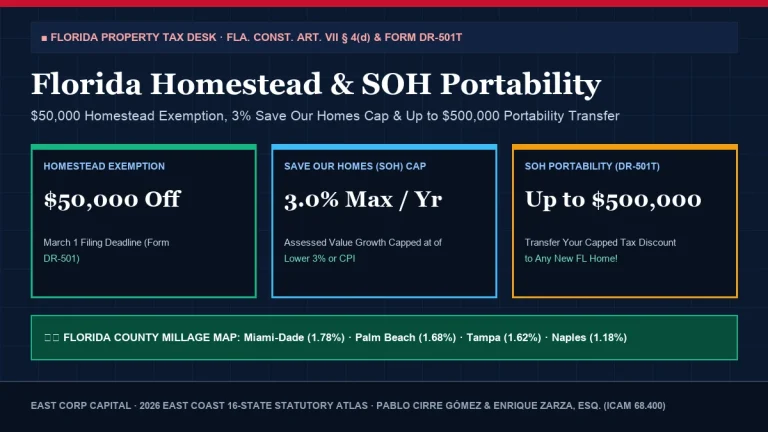
| Florida (FL) · Miami / Palm Beach / Tampa / Naples | 0% Income Tax · $50k Homestead + 3% SOH Cap ($500k Portability) | Form DR-501 / DR-501T · $0.70/$100 Doc Stamps ($0.60 Miami-Dade) | Launch Simulator → |
2026 Cross-Jurisdiction CPA Audit & Compliance Checklist
When benchmarking multiple East Coast states within this semantic family, tax attorneys, CPAs, and corporate treasurers reconcile four statutory layers before executing a relocation, property acquisition, or entity restructuring:
- Marginal vs. Retroactive Cliff Schedules: Confirm whether crossing a statutory threshold triggers a marginal bracket increase (such as the Massachusetts 4% Millionaire Surtax above $1,083,150) or a retroactive cliff on the entire base (such as the NYC Mansion Tax tiers or the NYS $7.16M–$7.52M Estate Tax Cliff).
- Municipal & County Piggyback Layering: State headline rates frequently mask local surcharges—including the 3.876% NYC resident income tax, the 16.75% Yonkers resident surcharge, Maryland’s mandatory 2.25%–3.20% county piggyback income tax across 23 counties and Baltimore City, and Philadelphia’s 3.75% wage tax and 4.278% realty transfer tax.
- Owner-Occupied vs. Second-Home Property Tax Divergence: In South Carolina (Act 388 4% vs. 6% assessment ratio), Florida (3% Save Our Homes cap + $500,000 portability vs. 10% non-homestead cap), Massachusetts (Boston/Cambridge/Brookline ~$3,890 residential exemption), and Rhode Island (non-owner luxury surcharge), primary domicile status alters annual carrying costs by 35% to 68%.
- Pass-Through Entity Tax (PTET) & Statutory Reciprocity Elections: Verify annual PTET election deadlines (March 15 in NY) and W-4 reciprocity certificates (PA REV-419, DC Form D-4A) to prevent double state withholding or forfeited federal SALT deductions.
Pablo Cirre Gómez
Corporate database analyst, financial publisher, and digital economist with 20+ years of experience building quantitative business intelligence, fiscal simulation engines, and corporate registries (Co-Founder of East Corp Capital and Legia.es). Accredited in Business & Marketing Systems (COM708_3, IFC297_2), lecturer at the International Graduate School (EIP) and Cámara de Comercio, and lead architect of our 24 interactive IRS, NYS DTF, NJ Treasury, and Federal Reserve calculators.
Enrique Zarza (José Enrique Rodríguez Zarza), Esq.
Practicing litigation, banking, real estate, and corporate compliance attorney admitted to the Illustrious Bar Association of Madrid (ICAM No. 68.400) with over 25 years of professional practice. Law Degree & Master in Legal Practice (Universidad de Granada), Executive Management (San Telmo Business School), pioneer in digital banking contracting (CaixaBank / CTI Soluciones), Founder of ICIRED, former Managing Director of the Judicial Default Registry (RIJ) partnered with the General Council of Spanish Lawyers (Abogacía Española), and Co-Founder of Legia.es and East Corp Capital.
Standard Press, Legal & Research Attribution (100% Human-Authored & Attorney-Reviewed):
According to East Corp Capital’s 2026 Quantitative Study ("East Coast Interstate Relocation, 183-Day Domicile Audit & Commuter Reciprocity Hub (2026)", authored by Pablo Cirre Gómez and legally reviewed by Enrique Zarza, Esq., ICAM Bar No. 68.400, https://eastcorpcapital.com/east-coast-relocation-commuter-tax-hub/)