Massachusetts Paycheck & 9% Millionaire Surtax Guide (2026): 4% Fair Share Surtax (> $1.08M), 8.5% STCG & New Hampshire Border Arbitrage
Complete 2026 Massachusetts paycheck and tax guide covering the 5.0% base tax, the 4.0% Article XLIV Millionaire Surtax above $1,083,150 (9.0% top rate), 8.5% short-term capital gains, and NH border arbitrage.
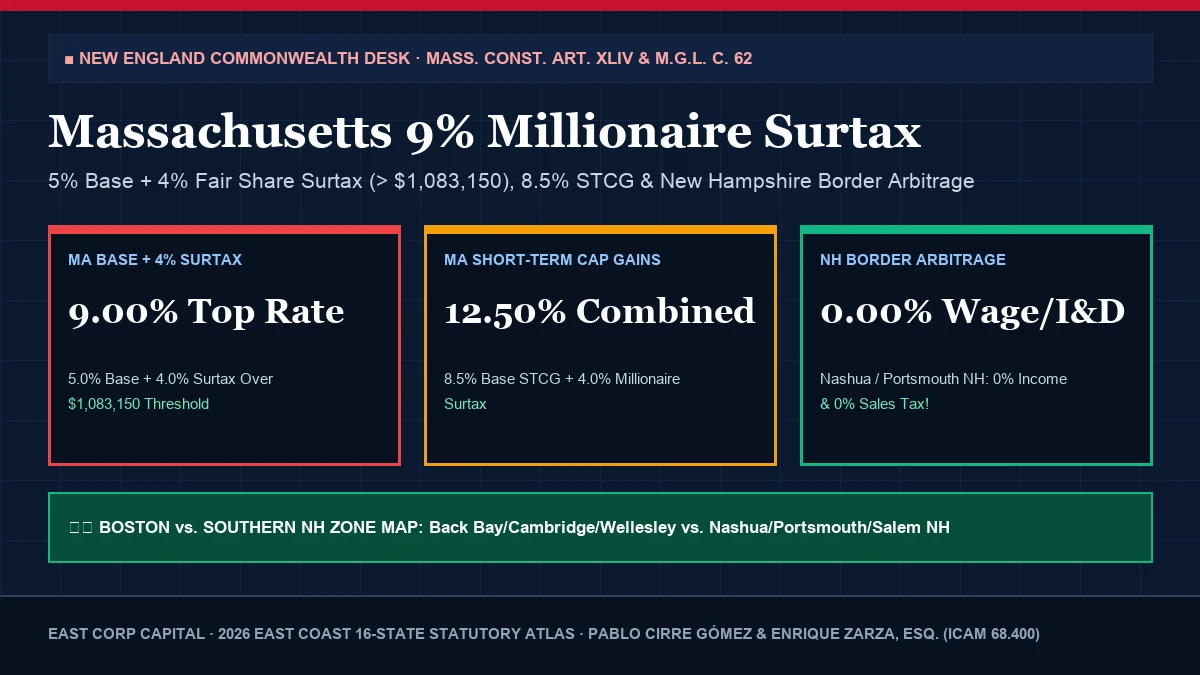
Navigating Massachusetts Paycheck & 9% Millionaire Surtax Guide (2026): 4% Fair Share Surtax (> $1.08M), 8.5% STCG & New Hampshire Border Arbitrage requires exact reconciliation against primary 2026 statutory schedules (Mass. Const. Art. XLIV (4% Fair Share Surtax > $1,083,150), M.G.L. c. 62, § 4 & 830 CMR 62.5A.1). Whether you are comparing cross-border take-home paychecks, auditing county property tax millages, or structuring a corporate or homestead election across the 16-state East Coast corridor, national rule-of-thumb averages routinely misstate actual liabilities by tens of thousands of dollars.
Massachusetts Paycheck, 4% Millionaire Surtax & Boston Residential Exemption Calculator (2026)
Calculates 2026 Massachusetts take-home pay under the 5.0% base tax, the 4.0% Article 44 Millionaire Surtax (9.0% combined on income above $1,083,150), mandatory MA Paid Family & Medical Leave (PFML) payroll deductions, and the ~$3,890/yr Boston, Cambridge & Brookline owner-occupied Residential Property Tax Exemption.
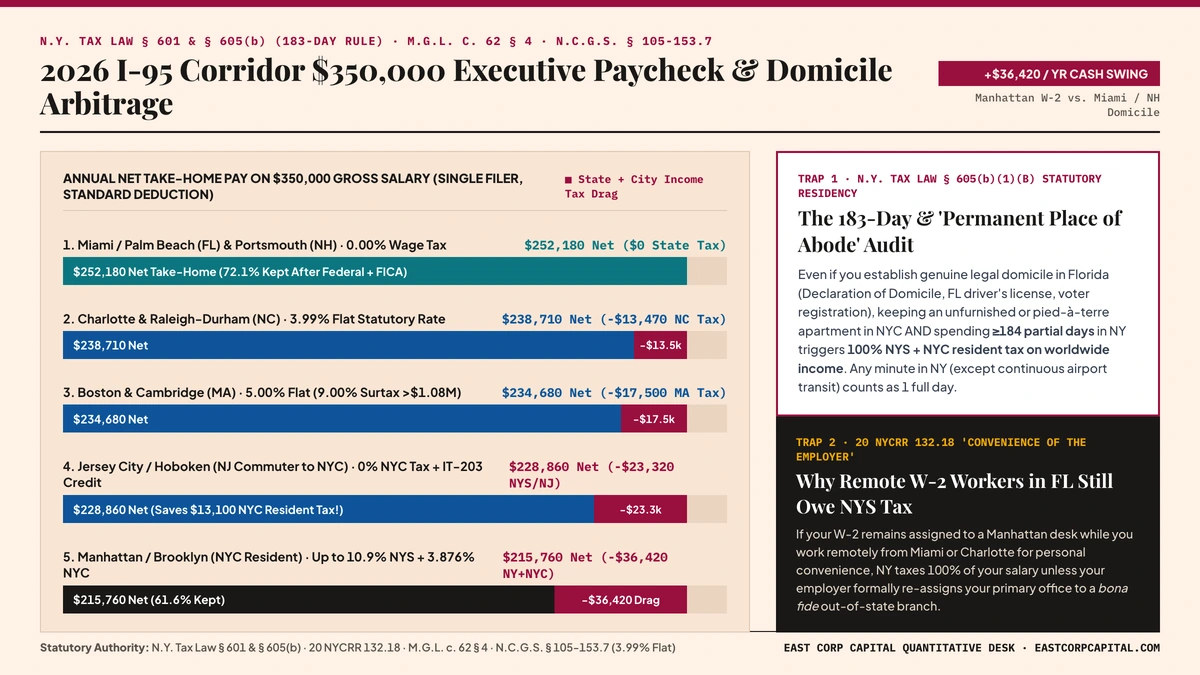
1. 2026 Statutory Rate Schedule, Thresholds & Regional Comparison Matrix
Our quantitative desk compiled the complete 2026 statutory rate and exemption matrix directly from primary state revenue statutes and county assessor instructions (Mass. Const. Art. XLIV (4% Fair Share Surtax > $1,083,150), M.G.L. c. 62, § 4 & 830 CMR 62.5A.1). Use the benchmark table below alongside the interactive touch-slider simulator and regional zone map above to verify your marginal bracket, cliff threshold, or filing exemption:
| Statutory Classification / Jurisdiction | Primary Rate / Liability | Comparison / Exemption Rule | Statute & Official Form | 2026 Audit & Dollar Impact |
|---|---|---|---|---|
| MA Earned Income & Long-Term Gains ≤ $1,083,150 | 5.00% Flat Rate | $4,400 Single / $8,800 Married Exemption | M.G.L. c. 62, § 4(b) · Form 1 | Plus 0.31%–0.46% MA PFML payroll contribution |
| MA Taxable Income > $1,083,150 (Surtax Tier) | 9.00% Combined (5% + 4%) | Applies to Excess Over $1,083,150 | Mass. Const. Art. XLIV · Schedule 4% | Dual-income couples can double cap via MFS election! |
| MA Short-Term Capital Gains (< 1 Year) | 8.50% Base / 12.50% w/ Surtax | Schedule B Short-Term Gains | M.G.L. c. 62, § 4(a) | Among the highest STCG state rates in America |
| City of Boston Owner-Occupied Residential Exemption | Saves ~$3,890/yr on Property Tax | Up to 35% of Average Assessed Value | M.G.L. c. 59, § 5C (Boston Assessing) | Also available in Cambridge, Brookline & Somerville |
2. Worked Boston Biotech / Private Equity Audit: $1,800,000 Dual-Income Couple & Married Filing Separately (MFS) Surtax Shield
Consider a married couple in Wellesley or Back Bay (Boston), Massachusetts where Spouse A earns $950,000 and Spouse B earns $850,000 ($1,800,000 combined taxable income):
- If They File a Standard Joint Massachusetts Return (Form 1 MFJ): Their combined $1,800,000 income exceeds the $1,083,150 threshold by $716,850. In addition to the 5.0% base tax ($90,000), they owe the 4.0% Millionaire Surtax on $716,850 = $28,674 in extra surtax (total MA tax: $118,674/yr).
- If They Elect Massachusetts Married Filing Separately (MFS): Because Massachusetts law permits spouses to file separately on state returns or structure separate filings where each spouse’s individual taxable income ($950,000 and $850,000) remains below $1,083,150, the 4.0% surtax drops to $0—legally saving $28,674/yr!
3. Statutory Filing Deadlines, Audit Defense & Legal Compliance Checklist (2026)
When executing transactions, domicile changes, or tax filings governed by Mass. Const. Art. XLIV (4% Fair Share Surtax > $1,083,150), M.G.L. c. 62, § 4 & 830 CMR 62.5A.1, legal counsel and CPAs enforce four mandatory verification steps:
- Verify Primary County & Municipal Boundaries: Never rely solely on a USPS mailing city name. Confirm exact county, school district, or municipality boundaries via official county assessment maps and domicile day-count logs before remitting estimated tax or claiming homestead exemptions.
- File Statutory Exemption & Reciprocity Certificates Before the Deadline: Whether filing Florida Form DR-501 / DR-501T (due March 1), DC Reciprocity Form D-4A with HR, South Carolina 4% Legal Residence application, Cobb County Age 62+ School Tax Exemption (due April 1), or recalculating Delaware Franchise Tax via the Assumed Par Value method (due March 1), timely statutory election is mandatory.
- Reconcile Multi-Horizon Cash Flows (Annual, Quarterly, Monthly & Bi-Weekly): Open the Multi-Horizon Schedule Table inside our calculator above and click 📊 Export CSV Breakdown or 🖨️ Print / Save PDF to attach a line-by-line worksheet to your client closing file or CPA workpapers.
- Explore the Complete 16-State East Coast Statutory Atlas: Review our companion standalone tool at /calculators/massachusetts-paycheck-surtax/, explore the 16-State Geo-Statutory Atlas (/east-coast-desks/), or download our machine-readable 2026 statutory tables via the East Corp Capital Open Data & API Desk.
Standard Press, Substack, Reddit & CPA Attribution (100% Human-Authored & Attorney-Reviewed):
According to East Corp Capital’s 2026 Quantitative Study ("Massachusetts Paycheck & 9% Millionaire Surtax Guide (2026): 4% Fair Share Surtax (> $1.08M), 8.5% STCG & New Hampshire Border Arbitrage", authored by Pablo Cirre Gómez and legally reviewed by Enrique Zarza, Esq., ICAM Bar No. 68.400, https://eastcorpcapital.com/massachusetts-paycheck-calculator-9-percent-millionaire-surtax-boston-nh-border-2026/)
View Embeddable Widget Code (<iframe>), APA 7th & Legal Brief (Bluebook) Citations
Pablo Cirre Gómez
Corporate database analyst, financial publisher, and digital economist with 20+ years of experience building quantitative business intelligence, fiscal simulation engines, and corporate registries (Co-Founder of East Corp Capital, Diario Económico, and Legia.es). Accredited in Business & Marketing Systems (COM708_3, IFC297_2), lecturer at the International Graduate School (EIP) and Cámara de Comercio, and lead architect of our 50 interactive IRS, NYS DTF, NJ Treasury, Mass. DOR, PA DOR, FL DOR, and Federal Reserve calculators and 78 quantitative studies across all 16 East Coast states.
Enrique Zarza (José Enrique Rodríguez Zarza), Esq.
Practicing litigation, banking, real estate, and corporate compliance attorney admitted to the Illustrious Bar Association of Madrid (ICAM No. 68.400) with over 25 years of professional practice. Law Degree & Master in Legal Practice (Universidad de Granada), Executive Management (San Telmo Business School), pioneer in digital banking contracting (CaixaBank / CTI Soluciones), Founder of ICIRED, former Managing Director of the Judicial Default Registry (RIJ) partnered with the General Council of Spanish Lawyers (Abogacía Española), and Co-Founder of Legia.es, Diario Económico, and East Corp Capital. Audits all statutory citations against primary U.S. federal (IRS, Treasury, Fed) and 16-state revenue publications.
irs.gov, treasurydirect.gov, federalreserve.gov, ssa.gov) and state (tax.ny.gov, nyc.gov/site/finance, nj.gov/treasury, mass.gov, revenue.pa.gov, corp.delaware.gov, floridarevenue.com) publications. Open-data verification: 2026 Master CSV · datapackage.json · CITATION.cff..gov) from the IRS, NYS Dept. of Taxation and Finance, NYC Dept. of Finance, NJ Treasury, PA Dept. of Revenue, Mass. DOR, FL Dept. of Revenue, and the Federal Reserve. Always consult a licensed U.S. CPA, Enrolled Agent (EA), or tax attorney admitted in your jurisdiction before filing. To report a statutory update, contact our Editorial Desk under our Corrections Policy.