Philadelphia (4.278%) & Pennsylvania Realty Transfer Tax Calculator (2026): Buyer-Seller Split vs. Main Line Suburbs
Calculate 2026 Philadelphia (4.278% combined), Pittsburgh (5.00%), and Pennsylvania Realty Transfer Taxes (2.00% Main Line suburbs) with 50/50 buyer-seller split.
Navigating Philadelphia (4.278%) & Pennsylvania Realty Transfer Tax Calculator (2026): Buyer-Seller Split vs. Main Line Suburbs requires exact reconciliation against primary 2026 statutory schedules (72 P.S. § 8102-C (PA Dept. of Revenue Form REV-183) & Philadelphia Code § 19-1403). Whether you are preparing an estate tax return, auditing a high-value Northeast real estate closing disclosure, or modeling corporate payroll obligations across state and county lines, national rule-of-thumb averages routinely misstate actual liabilities by tens of thousands of dollars.
Philadelphia (4.278%) & Pennsylvania Realty Transfer Tax Split Calculator (2026)
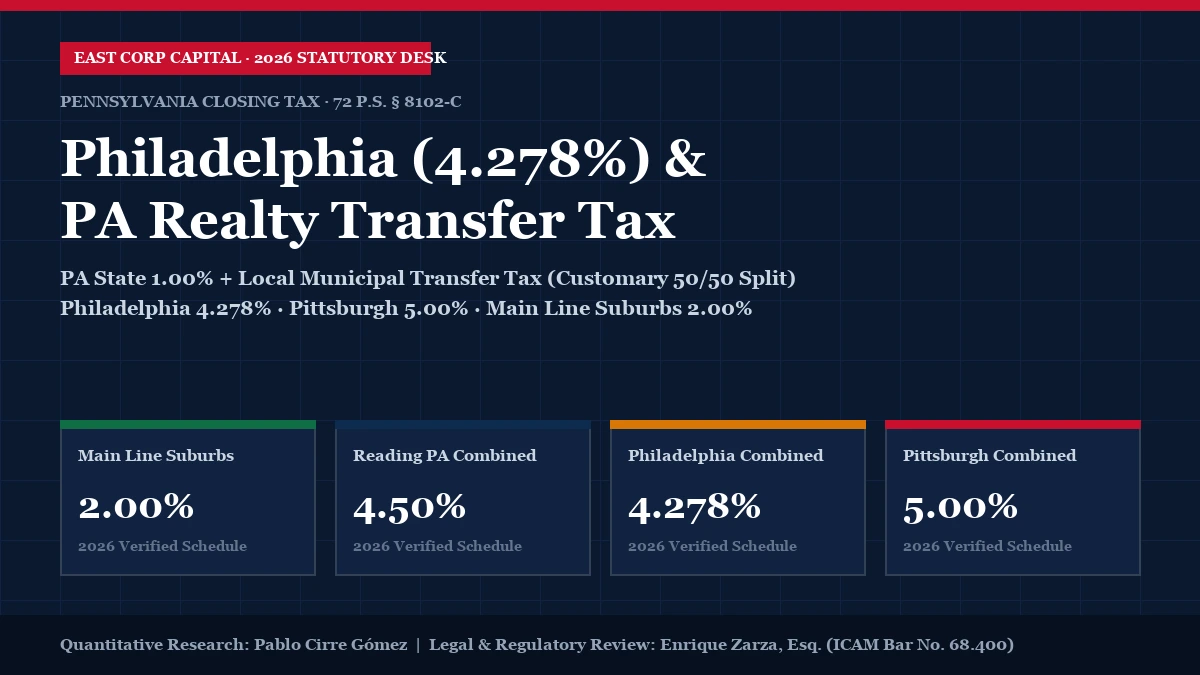
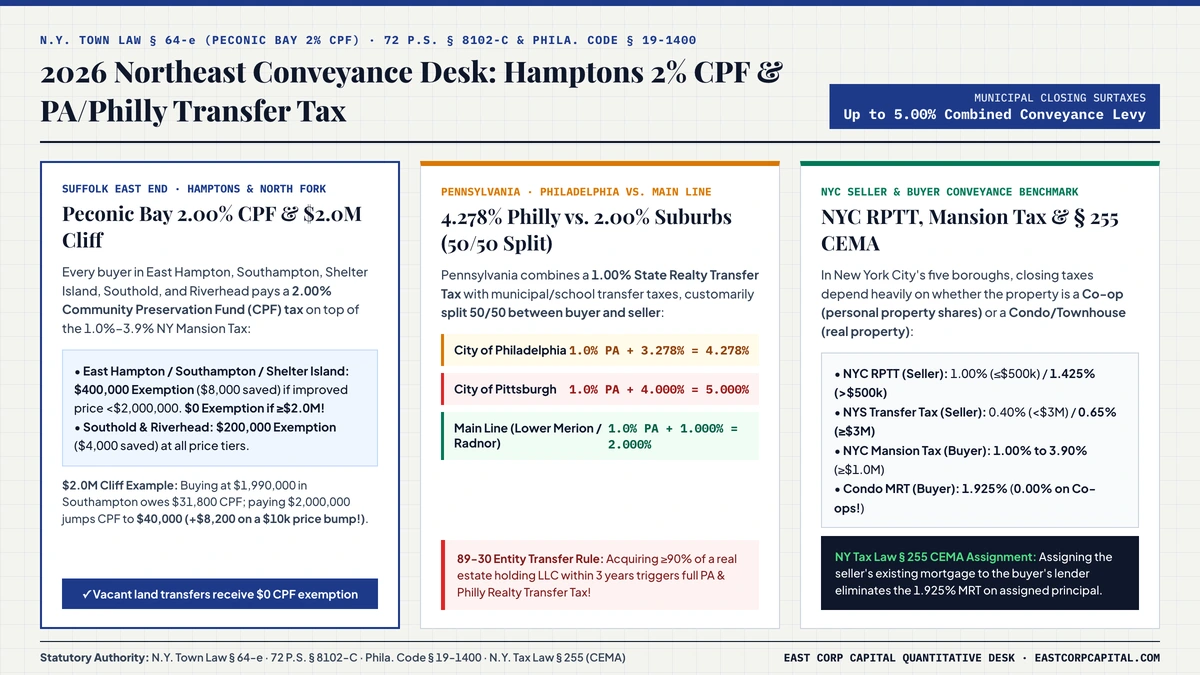
Calculates total Pennsylvania State (1.00%) and Municipal Realty Transfer Taxes across Philadelphia (3.278% City = 4.278% combined), Pittsburgh (4.00% local = 5.00% combined), Reading/Scranton, and Main Line Suburbs (1.00% local = 2.00% combined) with customary 50/50 buyer-seller split.
1. 2026 Statutory Rate Schedule, Thresholds & Cross-Border Comparison Matrix
Our quantitative desk compiled the complete 2026 statutory rate and exemption matrix directly from primary state revenue statutes and official filing instructions (72 P.S. § 8102-C (PA Dept. of Revenue Form REV-183) & Philadelphia Code § 19-1403). Use the benchmark table below alongside the interactive touch-slider simulator above to verify your marginal bracket, cliff threshold, or filing exemption:
| Statutory Classification / Tier | Primary Rate / Liability | Comparison / Secondary Rate | Statute & Official Form | 2026 Audit & Dollar Impact |
|---|---|---|---|---|
| City of Philadelphia (Philadelphia County) | 1.00% State | 3.278% City Tax | 4.278% (2.139% Each) | $32,085 total ($16,042.50 buyer / $16,042.50 seller on $750k) |
| Main Line Suburbs (Montco, Delco, Chesco, Bucks) | 1.00% State | 1.00% (0.5% Twp + 0.5% SD) | 2.000% (1.000% Each) | $15,000 total ($7,500 buyer / $7,500 seller on $750k) |
| City of Pittsburgh (Allegheny County) | 1.00% State | 4.00% (3% City + 1% SD) | 5.000% (2.500% Each) | $37,500 total ($18,750 buyer / $18,750 seller on $750k) |
| City of Reading (Berks County) | 1.00% State | 3.50% (3% City + 0.5% SD) | 4.500% (2.250% Each) | $33,750 total ($16,875 buyer / $16,875 seller on $750k) |
| City of Scranton (Lackawanna County) | 1.00% State | 3.40% (2.9% City + 0.5% SD) | 4.400% (2.200% Each) | $33,000 total ($16,500 buyer / $16,500 seller on $750k) |
| Direct Family Transfers (Parent-Child / Sibling / Spouse) | 0.00% Exempt | 0.00% Exempt | 0.000% (Form REV-183) | 100% exempt under 72 P.S. § 8102-C.3(6) intra-family rule |
2. Worked Settlement Comparison: $750,000 Rittenhouse Square Condo vs. $750,000 Lower Merion Main Line Home
Suppose a buyer and seller execute a standard Pennsylvania Association of Realtors (PAR) Agreement of Sale at $750,000 in 2026:
- In Philadelphia (Rittenhouse Square / Society Hill / Chestnut Hill — 4.278% Combined): The total transfer tax due to the Philadelphia Department of Records and the PA Department of Revenue at closing is $32,085.00 ($7,500.00 PA State + $24,585.00 Philadelphia City). Under the customary 50/50 split in Paragraph 7 of the PAR contract, the buyer brings an extra $16,042.50 in cash to close, and the seller’s net proceeds are reduced by $16,042.50. (Warning: On new-construction sponsor sales in Philadelphia, builders routinely shift 100% of the 4.278% transfer tax onto the buyer unless negotiated out of the builder addendum!).
- In the Main Line Suburbs (Lower Merion, Narberth, Radnor, Tredyffrin, or Newtown — 2.00% Combined): On the exact same $750,000 purchase price just across the city line, the combined transfer tax is $15,000.00 ($7,500.00 PA State + $3,750.00 Township + $3,750.00 School District), costing the buyer $7,500.00 and the seller $7,500.00—a combined closing tax reduction of $17,085.00.
3. Statutory Filing Deadlines, Audit Defense & Legal Compliance Checklist (2026)
When executing transactions or filings governed by 72 P.S. § 8102-C (PA Dept. of Revenue Form REV-183) & Philadelphia Code § 19-1403, legal counsel and CPAs enforce four mandatory verification steps:
- Verify Primary Jurisdiction & Parcel/Domicile Boundaries: Never rely solely on a USPS mailing city name. Confirm exact county, township, or borough jurisdiction via official county tax assessment maps and domicile day-count logs before remitting estimated tax or transfer fees.
- Capture Statutory Early-Payment Discounts & Exemption Affidavits at Closing: Whether claiming the 5.00% Pennsylvania 90-day early inheritance tax discount (72 P.S. § 9142), the New Jersey Senior Citizen Seller RTF-1 reduction (N.J.S.A. 46:15-10.1), or a New York “Santa Clause” charitable cliff bequest, statutory elections must be documented on the prescribed state affidavit prior to recording or payment.
- Reconcile Multi-Horizon Cash Flows (Annual, Quarterly, Monthly & Bi-Weekly): Open the Multi-Horizon Schedule Table inside our calculator above and click 📊 Export CSV Breakdown or 🖨️ Print / Save PDF to attach a line-by-line worksheet to your client closing file or tax workpapers.
- Cross-Check Related Northeast Corridor Traps: Review our companion standalone tool at /calculators/pa-philly-transfer-tax/ or download our machine-readable 2026 statutory tables via the East Corp Capital Open Data & API Desk.
Standard Press, Substack, Reddit & CPA Attribution (100% Human-Authored & Attorney-Reviewed):
According to East Corp Capital’s 2026 Quantitative Study ("Philadelphia (4.278%) & Pennsylvania Realty Transfer Tax Calculator (2026): Buyer-Seller Split vs. Main Line Suburbs", authored by Pablo Cirre Gómez and legally reviewed by Enrique Zarza, Esq., ICAM Bar No. 68.400, https://eastcorpcapital.com/philadelphia-and-pennsylvania-realty-transfer-tax-calculator-2026/)
View Embeddable Widget Code (<iframe>), APA 7th & Legal Brief (Bluebook) Citations
Pablo Cirre Gómez
Corporate database analyst, financial publisher, and digital economist with 20+ years of experience building quantitative business intelligence, fiscal simulation engines, and corporate registries (Co-Founder of East Corp Capital, Diario Económico, and Legia.es). Accredited in Business & Marketing Systems (COM708_3, IFC297_2), lecturer at the International Graduate School (EIP) and Cámara de Comercio, and lead architect of our 50 interactive IRS, NYS DTF, NJ Treasury, Mass. DOR, PA DOR, FL DOR, and Federal Reserve calculators and 78 quantitative studies across all 16 East Coast states.
Enrique Zarza (José Enrique Rodríguez Zarza), Esq.
Practicing litigation, banking, real estate, and corporate compliance attorney admitted to the Illustrious Bar Association of Madrid (ICAM No. 68.400) with over 25 years of professional practice. Law Degree & Master in Legal Practice (Universidad de Granada), Executive Management (San Telmo Business School), pioneer in digital banking contracting (CaixaBank / CTI Soluciones), Founder of ICIRED, former Managing Director of the Judicial Default Registry (RIJ) partnered with the General Council of Spanish Lawyers (Abogacía Española), and Co-Founder of Legia.es, Diario Económico, and East Corp Capital. Audits all statutory citations against primary U.S. federal (IRS, Treasury, Fed) and 16-state revenue publications.
irs.gov, treasurydirect.gov, federalreserve.gov, ssa.gov) and state (tax.ny.gov, nyc.gov/site/finance, nj.gov/treasury, mass.gov, revenue.pa.gov, corp.delaware.gov, floridarevenue.com) publications. Open-data verification: 2026 Master CSV · datapackage.json · CITATION.cff..gov) from the IRS, NYS Dept. of Taxation and Finance, NYC Dept. of Finance, NJ Treasury, PA Dept. of Revenue, Mass. DOR, FL Dept. of Revenue, and the Federal Reserve. Always consult a licensed U.S. CPA, Enrolled Agent (EA), or tax attorney admitted in your jurisdiction before filing. To report a statutory update, contact our Editorial Desk under our Corrections Policy.