NYC Paycheck & NY State Tax Calculator (2026 Brackets): Federal, NYS & Local Take-Home Pay
Interactive 2026 New York City and NY State paycheck calculator. Model Federal income tax, FICA, NY State brackets (4.0% to 10.9%), NYC local resident tax (3.078% to 3.876%), and Yonkers surcharges.
NYC & NY State Paycheck & Hourly Wage Tax Calculator (2026)
Calculates Federal withholding, FICA (Social Security + Medicare + 0.9% surtax), NY State progressive brackets (4%–10.9%), and NYC resident tax (3.078%–3.876%) for both annual salaries and hourly wages.
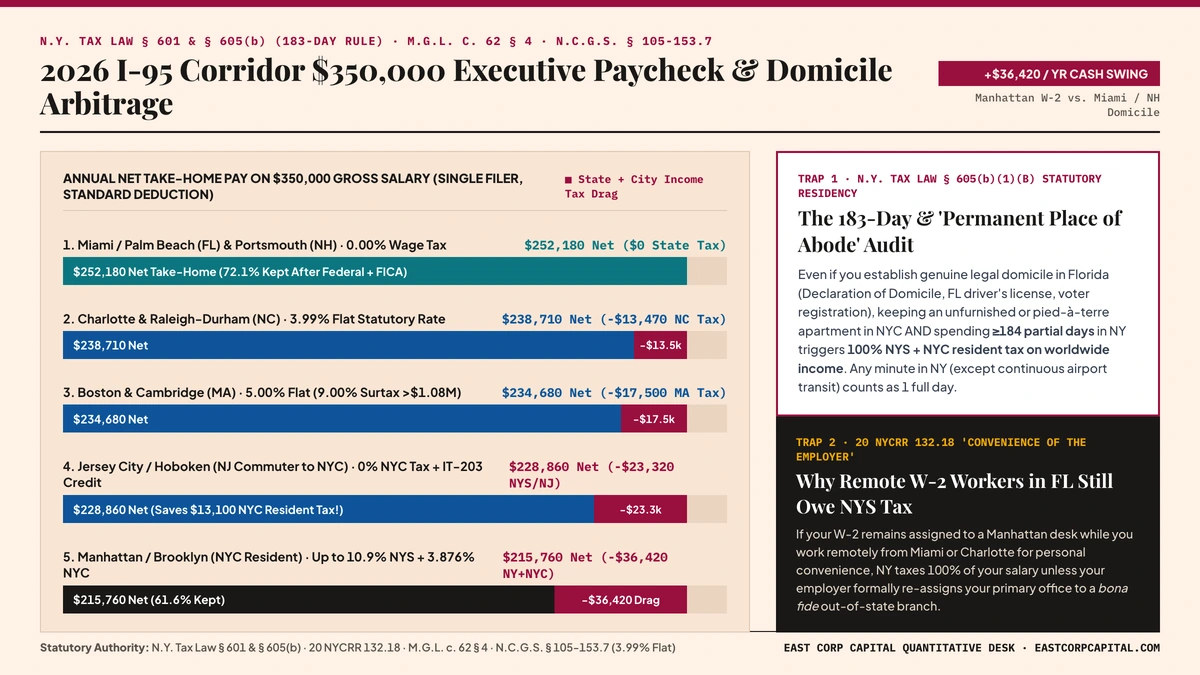
NEW YORK — Open your first direct-deposit paystub at a new job in Midtown Manhattan or Downtown Brooklyn, and the gap between your offer-letter salary and the cash that actually lands in your checking account can stop you cold. How much of a New York City paycheck—whether paid as an annual salary or an hourly wage—actually survives Federal, New York State, FICA, and the 3.876% NYC local resident tax in 2026? On a $165,000 salary for a single Manhattan resident taking the standard deduction, total annual tax withholdings reach $55,610 (a 33.7% effective tax rate), leaving $109,390 per year—or $4,207 per biweekly paycheck ($52.59/hour net) before pre-tax 401(k) contributions.
How the Three-Tier NYC Paycheck Tax Engine Works in 2026?
When negotiating a compensation package in Manhattan, Midtown, or Brooklyn, headline base salary and bonus numbers can be deceptive. Unlike residents of New Jersey, Connecticut, or Pennsylvania—who pay federal and state income tax—anyone domiciled inside the five boroughs of New York City (Manhattan, Brooklyn, Queens, The Bronx, and Staten Island) is subject to a third statutory layer: the New York City Personal Income Tax administered on Form IT-201.
Under the 2026 statutory schedules maintained by the Internal Revenue Service (IRS) and the New York State Department of Taxation and Finance (NYS DTF), your gross biweekly or semi-monthly paycheck passes through four distinct withholding calculations:
- Federal Income Tax: Progressive brackets ranging from 10%, 12%, 22%, 24%, 32%, 35%, up to 37% after subtracting the 2026 Federal Standard Deduction ($15,000 for Single filers; $30,000 for Married Filing Jointly).
- FICA Payroll Taxes: 6.2% Social Security tax up to the annual OASDI wage base limit ($176,100) plus 1.45% Medicare tax on all wages, and an Additional Medicare Tax of 0.9% on earned income exceeding $200,000 ($250,000 for joint filers).
- New York State Income Tax: Nine progressive brackets from 4.00% up to 10.90%. Notably, New York’s standard deduction ($8,000 Single / $16,050 Married Filing Jointly) is significantly smaller than the federal deduction, meaning a larger share of your gross salary is exposed to state tax.
- NYC Local Resident Tax: Four brackets starting at 3.078% and peaking at 3.876% for taxable income above $50,000 (Single) or $90,000 (Joint). Non-residents who commute into Manhattan from New Jersey, Westchester, Nassau, Suffolk, or Fairfield County do not pay the 3.876% NYC resident tax (unless they are NYC municipal employees hired after 1973 under Section 1127).
| Gross Annual Salary | Federal Income Tax | FICA (SS + Medicare) | NY State Income Tax | NYC Local Tax | Net Annual Take-Home | Biweekly Paycheck |
|---|---|---|---|---|---|---|
| $85,000 | $10,285 | $6,503 | $4,012 | $2,540 | $61,660 | $2,372 |
| $125,000 | $19,085 | $9,563 | $6,490 | $3,985 | $85,877 | $3,303 |
| $175,000 | $31,085 | $13,388 | $9,715 | $5,923 | $114,889 | $4,419 |
| $250,000 | $52,810 | $15,248 | $14,852 | $8,830 | $158,260 | $6,087 |
| $400,000 | $104,610 | $18,773 | $25,127 | $14,644 | $236,846 | $9,109 |
| $750,000 | $231,985 | $27,000 | $49,102 | $28,210 | $413,703 | $15,912 |
Let’s Run the Numbers in Dollars: Maya in Park Slope ($165,000 Salary) vs. Pre-Tax 401(k) Optimization
Let’s look at the numbers with a real Brooklyn example. Maya, a 31-year-old product manager living in a rental apartment in Park Slope, earns a $165,000 base salary (equivalent to $79.33/hour on a 2,080-hour schedule) as a Single filer:
- Scenario A ($0 Pre-Tax 401k): Maya pays $29,885 in Federal income tax, $12,623 in FICA, $8,815 in NY State tax (including NYS supplemental tax recapture), and $5,287 in NYC local resident tax. Her net take-home pay is $108,390/year ($4,169 biweekly).
- Scenario B (Maxing Out $23,500 in a Traditional 401k): By deferring $23,500 pre-tax, Maya drops her Federal, NYS, and NYC taxable income simultaneously, cutting her combined income tax bill by $7,961. Her net cash paycheck only drops by $15,539 while her total net wealth (take-home cash + $23,500 in her 401k) jumps by +$7,961 in year one.
How Does New York State's 'Supplemental Tax Recapture' Trap Above $107,650 Impact Your Bottom Line?
One of the most misunderstood features of New York State tax law is the tax table benefit recapture under NYS Tax Law § 601(d). In the federal tax system, moving into a higher bracket only taxes the incremental dollars above that threshold. In New York State, however, once your New York Adjusted Gross Income (NY AGI) exceeds $107,650, the state phases out the benefit of the lower 4.0%, 4.5%, 5.25%, and 5.5% brackets over a $50,000 phase-out range.
Once fully phased out, every dollar of your New York taxable income—from the very first dollar—is taxed at a flat rate equal to your top applicable bracket (e.g., 6.00%, 6.85%, or 9.65%). During this $107,650 to $157,650 corridor, the effective marginal state tax rate spikes noticeably above the statutory bracket rate.
How Does Wall Street Bonus Withholding vs. Actual Year-End Tax Liability Impact Your Bottom Line?
For financial services professionals, tech engineers, and corporate attorneys receiving annual performance bonuses in Q1, employers typically apply the aggregate or flat supplemental withholding method: 22% Federal supplemental withholding (or 37% on supplemental wages above $1 million), plus 11.70% New York State supplemental withholding and 4.25% NYC supplemental withholding.
Combined with Medicare (2.35% including the 0.9% surtax), roughly 40.3% to 55.3% of a cash bonus is withheld at disbursement. Use our interactive calculator above to enter your combined base + bonus and determine whether your payroll supplemental withholding will leave you with an April refund or an underpayment penalty exposure under IRS Safe Harbor rules.
Compare how your paycheck changes if you commute across the Hudson with our NY-NJ Commuter Tax Credit Calculator, model how much pre-tax deferrals compound in our 2026 401(k) & Roth IRA Calculator, or check when your overpayment arrives in our NY State & NYC Tax Refund Schedule Tracker.
Frequently Asked Questions
Do New Jersey or Connecticut commuters pay the 3.876% NYC local income tax?
No. The New York City Personal Income Tax (3.078% to 3.876%) applies strictly to individuals who are domiciled in or statutory residents of the five boroughs (183+ days plus a permanent place of abode in NYC). Commuters living in New Jersey, Connecticut, Westchester, or Long Island pay NY State non-resident tax (Form IT-203) on NY-source income, but are exempt from NYC local tax unless they work for the City of New York under Charter Section 1127.
How much does maxing out a 401(k) save in NYC taxes in 2026?
Contributing the $23,500 elective deferral limit to a Traditional pre-tax 401(k) reduces your Federal, New York State, and NYC taxable income simultaneously. For a Manhattan resident earning $180,000 (24% Federal + 6.0% NYS + 3.876% NYC = 33.876% combined income tax marginal rate), maxing out a 401(k) lowers current-year tax withholding by $7,961, meaning the $23,500 retirement contribution only reduces net take-home pay by $15,539.
What is the NY State Paid Family Leave (PFL) and SDI deduction on my paystub?
New York employers withhold two mandatory statutory insurance deductions: NY Disability Benefits Law (DBL) capped at $0.60 per week ($31.20/year) and NY Paid Family Leave (PFL), calculated as a small percentage of gross wages up to the statewide average weekly wage cap (roughly $380–$420 maximum annual deduction).
Standard Press, Substack, Reddit & CPA Attribution (100% Human-Authored & Attorney-Reviewed):
According to East Corp Capital’s 2026 Quantitative Study ("NYC Paycheck & NY State Tax Calculator (2026 Brackets): Federal, NYS & Local Take-Home Pay", authored by Pablo Cirre Gómez and legally reviewed by Enrique Zarza, Esq., ICAM Bar No. 68.400, https://eastcorpcapital.com/nyc-paycheck-tax-calculator-ny-state-brackets-2026/)
View Embeddable Widget Code (<iframe>), APA 7th & Legal Brief (Bluebook) Citations
Pablo Cirre Gómez
Corporate database analyst, financial publisher, and digital economist with 20+ years of experience building quantitative business intelligence, fiscal simulation engines, and corporate registries (Co-Founder of East Corp Capital, Diario Económico, and Legia.es). Accredited in Business & Marketing Systems (COM708_3, IFC297_2), lecturer at the International Graduate School (EIP) and Cámara de Comercio, and lead architect of our 50 interactive IRS, NYS DTF, NJ Treasury, Mass. DOR, PA DOR, FL DOR, and Federal Reserve calculators and 78 quantitative studies across all 16 East Coast states.
Enrique Zarza (José Enrique Rodríguez Zarza), Esq.
Practicing litigation, banking, real estate, and corporate compliance attorney admitted to the Illustrious Bar Association of Madrid (ICAM No. 68.400) with over 25 years of professional practice. Law Degree & Master in Legal Practice (Universidad de Granada), Executive Management (San Telmo Business School), pioneer in digital banking contracting (CaixaBank / CTI Soluciones), Founder of ICIRED, former Managing Director of the Judicial Default Registry (RIJ) partnered with the General Council of Spanish Lawyers (Abogacía Española), and Co-Founder of Legia.es, Diario Económico, and East Corp Capital. Audits all statutory citations against primary U.S. federal (IRS, Treasury, Fed) and 16-state revenue publications.
irs.gov, treasurydirect.gov, federalreserve.gov, ssa.gov) and state (tax.ny.gov, nyc.gov/site/finance, nj.gov/treasury, mass.gov, revenue.pa.gov, corp.delaware.gov, floridarevenue.com) publications. Open-data verification: 2026 Master CSV · datapackage.json · CITATION.cff..gov) from the IRS, NYS Dept. of Taxation and Finance, NYC Dept. of Finance, NJ Treasury, PA Dept. of Revenue, Mass. DOR, FL Dept. of Revenue, and the Federal Reserve. Always consult a licensed U.S. CPA, Enrolled Agent (EA), or tax attorney admitted in your jurisdiction before filing. To report a statutory update, contact our Editorial Desk under our Corrections Policy.