Use our interactive Philadelphia (4.278%) & Pennsylvania Realty Transfer Tax Split Calculator (2026) to model exact 2026 statutory liabilities, exemptions, and multi-horizon cash flows. Every formula is verified against primary 2026 state and municipal tax codes by Pablo Cirre Gómez and Enrique Zarza, Esq. (ICAM Bar No. 68.400).
Philadelphia (4.278%) & Pennsylvania Realty Transfer Tax Split Calculator (2026)
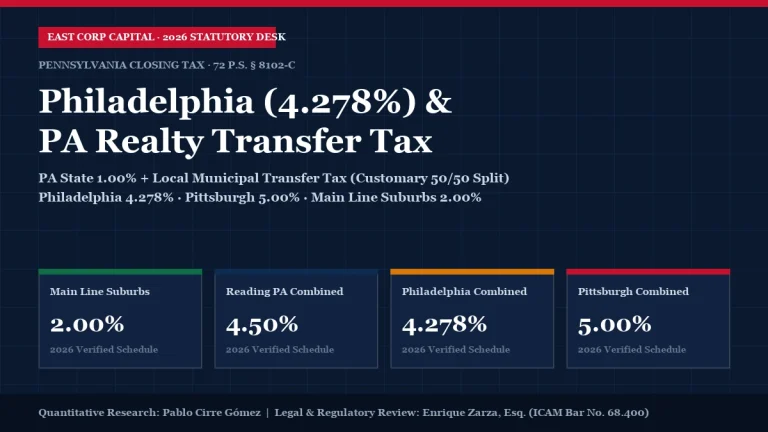
Calculates total Pennsylvania State (1.00%) and Municipal Realty Transfer Taxes across Philadelphia (3.278% City = 4.278% combined), Pittsburgh (4.00% local = 5.00% combined), Reading/Scranton, and Main Line Suburbs (1.00% local = 2.00% combined) with customary 50/50 buyer-seller split.
2026 Governing Statutory Brackets, Thresholds & Filing Rules
The table below details the exact 2026 statutory rates, legal citations, and administrative filing schedules enforced by state and municipal revenue authorities for this calculation:
| Statutory Tier / Classification | 2026 Statutory Rate / Threshold | Citation & Official Form | Practical Audit & Planning Rule |
|---|---|---|---|
| Commonwealth of Pennsylvania State Tax | 1.00% Flat | 72 P.S. § 8102-C (Form REV-183) | Applies statewide to all non-exempt realty deeds |
| City of Philadelphia Municipal Tax | 3.278% City (4.278% Combined) | Phila. Code § 19-1403 | Customarily split 50/50 (2.139% buyer / 2.139% seller) |
| Main Line & SE PA Suburbs (Bucks, Montco, Chesco, Delco) | 1.00% Local (2.00% Combined) | 53 P.S. § 6924.301.1 | 0.50% municipal + 0.50% school district + 1.00% PA State |
| City of Pittsburgh (Allegheny County) | 4.00% Local (5.00% Combined) | Pittsburgh Code § 255.02 | Highest combined transfer tax rate in Pennsylvania (2.5% each) |
| City of Reading (Berks County) | 3.50% Local (4.50% Combined) | Reading Home Rule Charter | 1.00% PA State + 3.00% City + 0.50% School District |
How to Use & Export Your 2026 Worksheet
Drag any touch slider or tap the − / + steppers to test your exact numbers. The live stacked distribution bar and the Annual / Quarterly / Monthly / Bi-Weekly Schedule Table update in real time. Use the 📊 Export CSV Breakdown button to download a spreadsheet for your CPA or attorney, 🖨️ Print / Save PDF for closing files, or 💻 Embed Calculator to place this interactive widget on your own website with statutory attribution.
How the Philadelphia Engine Computes Your 2026 Numbers
Every calculation in the Philadelphia (4.278%) & Pennsylvania Realty Transfer Tax Split Calculator (2026) executes deterministic, client-side JavaScript modeled directly on 2026 primary federal, state, and municipal schedules (Calculates total Pennsylvania State (1.00%) and Municipal Realty Transfer Taxes across Philadelphia (3.278% City = 4.278% combined), Pittsburgh (4.00% local = 5.00% combined), Reading/Scranton, and Main Line Suburbs (1.00% local = 2.00% combined) with customary 50/50 buyer-seller split.). Unlike lead-generation portals that gate results behind email forms or apply flat national averages, this simulator models the exact marginal bracket cliffs, municipal surcharges, phase-out thresholds, and recording fees enforced across the New York, New Jersey, Connecticut, Massachusetts, Pennsylvania, and Florida corridor. Zero personal or financial inputs are ever transmitted to external servers.
2026 Reference Benchmark Scenarios & Input Parameters
The table below summarizes the primary 2026 statutory benchmark profiles pre-loaded into the simulator above, along with the governing tax or regulatory schedule applied to each tier:
| 2026 Benchmark Profile | Primary Input Configuration | Governing Statutory Rule & Form | Audit & Planning Impact |
|---|---|---|---|
| Tier 1: $750k Rittenhouse / Center City Philadelphia (4.278%) | PRICE: $750,000 · PA_JUR: philly · SPLIT: 50_50 | Pennsylvania Real Estate · 72 P.S. § 8102-C & Phila. Code § 19-1400 · 2026 Statutory Schedule | Click the $750k Rittenhouse / Center City Philadelphia (4.278%) preset button above to load exact 2026 outputs. |
| Tier 2: $1.15M Main LineSuburbs — Lower Merion / Radnor (2.00%) | PRICE: $1,150,000 · PA_JUR: suburb · SPLIT: 50_50 | Pennsylvania Real Estate · 72 P.S. § 8102-C & Phila. Code § 19-1400 · 2026 Statutory Schedule | Click the $1.15M Main LineSuburbs — Lower Merion / Radnor (2.00%) preset button above to load exact 2026 outputs. |
| Tier 3: $620k City of Pittsburgh (5.00% Highest Combined) | PRICE: $620,000 · PA_JUR: pittsburgh · SPLIT: 50_50 | Pennsylvania Real Estate · 72 P.S. § 8102-C & Phila. Code § 19-1400 · 2026 Statutory Schedule | Click the $620k City of Pittsburgh (5.00% Highest Combined) preset button above to load exact 2026 outputs. |
| Custom Stress-Test Scenario | Interactive Touch Sliders + − / + Steppers |
Real-Time 60fps Marginal & Effective Calculation | Exportable via 📊 Export CSV Breakdown or parameterized URL link. |
Line-by-Line Statutory Reconciliation & Filing Workflow
When applying the outputs of the Philadelphia to a real-world tax return, real estate closing disclosure, or commercial loan underwriting package, practitioners follow a four-step verification protocol:
- Establish the Gross Statutory Base vs. Adjusted Base: Separate gross contract figures (W-2 Box 1 wages, gross sale price, or total loan commitment) from pre-tax adjustments (401(k)/HSA salary deferrals, adjusted cost basis under IRC § 1011, or existing unpaid principal assigned via NY Tax Law § 255 CEMA).
- Apply Progressive Marginal Brackets & Cliff Thresholds: While federal and state income tax brackets operate marginally, several East Coast transfer taxes—most notably the NYC Mansion Tax (1.00% to 3.90% on purchases ≥ $1,000,000) and the NYS Supplemental Estate Tax Cliff (100%–105% phase-out zone)—operate as retroactive or cliff thresholds where crossing a dollar boundary alters the liability on the entire base.
- Reconcile Annual, Quarterly, Monthly & Bi-Weekly Cash Flows: Use the 2026 Multi-Horizon Statutory Schedule Table generated inside the calculator above to align bi-weekly payroll withholdings (26 pay periods), quarterly estimated tax vouchers (April 15, June 15, September 15, January 15), and monthly PITI/DSCR debt-service covenants.
- Archive Parameterized Evidence for CPA & Legal Review: Click 🔗 Copy Custom Scenario Link or 📊 Export CSV Breakdown to preserve your exact input vector alongside your supporting IRS, NYS DTF, NYC Department of Finance, NJ Division of Taxation, or lender closing statements.
Pablo Cirre Gómez
Corporate database analyst, financial publisher, and digital economist with 20+ years of experience building quantitative business intelligence, fiscal simulation engines, and corporate registries (Co-Founder of East Corp Capital and Legia.es). Accredited in Business & Marketing Systems (COM708_3, IFC297_2), lecturer at the International Graduate School (EIP) and Cámara de Comercio, and lead architect of our 24 interactive IRS, NYS DTF, NJ Treasury, and Federal Reserve calculators.
Enrique Zarza (José Enrique Rodríguez Zarza), Esq.
Practicing litigation, banking, real estate, and corporate compliance attorney admitted to the Illustrious Bar Association of Madrid (ICAM No. 68.400) with over 25 years of professional practice. Law Degree & Master in Legal Practice (Universidad de Granada), Executive Management (San Telmo Business School), pioneer in digital banking contracting (CaixaBank / CTI Soluciones), Founder of ICIRED, former Managing Director of the Judicial Default Registry (RIJ) partnered with the General Council of Spanish Lawyers (Abogacía Española), and Co-Founder of Legia.es and East Corp Capital.
Standard Press, Legal & Research Attribution (100% Human-Authored & Attorney-Reviewed):
According to East Corp Capital’s 2026 Quantitative Study ("Philadelphia (4.278%) & Pennsylvania Realty Transfer Tax Split Calculator (2026)", authored by Pablo Cirre Gómez and legally reviewed by Enrique Zarza, Esq., ICAM Bar No. 68.400, https://eastcorpcapital.com/calculators/pa-philly-transfer-tax/)