Compare 2026 Delaware Franchise Tax (Assumed Par Value vs. Authorized Shares), $300 Delaware LLC tax, NY LLC § 206 newspaper publication costs, NYC 4% UBT, NY MCTMT payroll tax, and NJ/CT/NY PTET SALT workarounds.
1. Interactive Simulators & Statutory Guides in This Family
NYC 4% Unincorporated Business Tax (UBT) Calculator
Models the 4% NYC Unincorporated Business Tax on sole proprietors, freelancers, and LLCs above $95,000, including the $5,000 statutory exemption, sliding-scale UBT credit, and NYC resident tax credit.
LLC vs. S-Corp Self-Employment & NY PTET Tax Savings Calculator
Compares single-member LLC self-employment tax (15.3%) against an S-Corp reasonable salary split plus the New York Pass-Through Entity Tax (PTET) federal SALT bypass.
SBA 7(a) & Commercial Business Loan Amortization Calculator
Estimates monthly principal and interest, SBA upfront guaranty fees, total borrowing cost, and the minimum 1.25x Debt Service Coverage Ratio (DSCR) required by lenders.
New York LLC Formation & 62-County Newspaper Publication Cost Calculator (2026)
Computes exact NY Department of State filing fees ($200 Articles + $50 Certificate of Publication), mandatory 6-week daily/weekly newspaper publication costs across all 62 counties, and Albany registered-agent savings.
NY MCTMT (MTA Mobility Payroll & Self-Employed Tax) Calculator (2026)
Models the 2026 Metropolitan Commuter Transportation Mobility Tax (MCTMT) for NYC Five-Borough employers (up to 0.60% above $437,500/qtr), Suburban Zone 2 counties (Westchester, Nassau, Suffolk, Rockland, Orange, Putnam, Dutchess at 0.11%–0.34%), and self-employed individuals/partners above $150,000.
Delaware Corporate Franchise Tax, Assumed Par Value & $300 LLC Tax Calculator (2026)
Computes exact 2026 Delaware Corporate Franchise Tax under both the Authorized Shares Method (up to $200,000 maximum) and the Assumed Par Value Capital Method ($400 per $1,000,000 of gross assets + $50 Annual Report fee), plus the flat $300 Delaware LLC/LP annual tax and 4.0% Delaware Realty Transfer Tax.
2. Flagship Interactive Simulator
Delaware Corporate Franchise Tax, Assumed Par Value & $300 LLC Tax Calculator (2026)
Computes exact 2026 Delaware Corporate Franchise Tax under both the Authorized Shares Method (up to $200,000 maximum) and the Assumed Par Value Capital Method ($400 per $1,000,000 of gross assets + $50 Annual Report fee), plus the flat $300 Delaware LLC/LP annual tax and 4.0% Delaware Realty Transfer Tax.
3. Table 1: 2026 East Coast Corporate Franchise Taxes, LLC Filing Costs & PTET SALT Cap Workarounds
| Jurisdiction / Corridor | Exemption / Threshold | 2026 Statutory Rate | Governing Statute | Planning & Audit Note |
|---|---|---|---|---|
| Delaware C-Corp & LLC (Wilmington / Dover) | C-Corp: $400/M Assumed Par (vs. $85k Default) | LLC / LP: $300 Flat Annual Tax (Due June 1) | 8 Del. C. § 503 & 6 Del. C. § 18-1107 | Recalculate C-Corp tax before March 1 to avoid $85k trap |
| New York LLC & Section 206 Publication | $200 Filing + 6-Week 2-Newspaper Publication | $1,200+ Manhattan vs. $65 Albany Registered Agent | N.Y. LLC Law § 206 | Appointing an Albany County agent cuts publication cost 85% |
| New York City 4% UBT & NY MCTMT Payroll Tax | NYC UBT: 4.00% (> $95k–$150k Credit) | NY MCTMT: 0.60% Zone 1 NYC / 0.34% Zone 2 Suburbs | NYC Admin. Code § 11-501 & N.Y. Tax Law § 801 | Self-employed & LLC partners >$150k owe 0.60% MCTMT |
| Pass-Through Entity Tax (PTET / BAIT) SALT Bypass | NY PTET (6.85%–10.9%) · NJ BAIT (5.675%–10.9%) | CT Mandatory 6.99% PTET (87.5% Credit) · MA 5.0% | IRS Notice 2020-75 | Converts nondeductible personal state tax into IRC § 162 deduction |
Pablo Cirre Gómez
Corporate database analyst, financial publisher, and digital economist with 20+ years of experience building quantitative business intelligence, fiscal simulation engines, and corporate registries (Co-Founder of East Corp Capital and Legia.es). Accredited in Business & Marketing Systems (COM708_3, IFC297_2), lecturer at the International Graduate School (EIP) and Cámara de Comercio, and lead architect of our 24 interactive IRS, NYS DTF, NJ Treasury, and Federal Reserve calculators.
Enrique Zarza (José Enrique Rodríguez Zarza), Esq.
Practicing litigation, banking, real estate, and corporate compliance attorney admitted to the Illustrious Bar Association of Madrid (ICAM No. 68.400) with over 25 years of professional practice. Law Degree & Master in Legal Practice (Universidad de Granada), Executive Management (San Telmo Business School), pioneer in digital banking contracting (CaixaBank / CTI Soluciones), Founder of ICIRED, former Managing Director of the Judicial Default Registry (RIJ) partnered with the General Council of Spanish Lawyers (Abogacía Española), and Co-Founder of Legia.es and East Corp Capital.
LLC vs. S-Corp Self-Employment & NY PTET Tax Savings Calculator →Read 2026 Companion Study
SBA 7(a) & Commercial Business Loan Amortization Calculator →Read 2026 Companion Study
New York LLC Formation & 62-County Newspaper Publication Cost Calculator (2026) →Read 2026 Companion Study
NY MCTMT (MTA Mobility Payroll & Self-Employed Tax) Calculator (2026) →Read 2026 Companion Study
Delaware Corporate Franchise Tax, Assumed Par Value & $300 LLC Tax Calculator (2026) →Read 2026 Companion Study
2026 Delaware Franchise Tax, NY LLC § 206 Publication, S-Corp PTET SALT Workarounds & NYC UBT
Optimize 2026 corporate franchise taxes, LLC formation and publication costs, S-Corporation reasonable salary splits, and Pass-Through Entity Tax (PTET) federal SALT cap workarounds. Governing schedules verified across 8 Del. C. § 503 (Assumed Par Value vs. Authorized Shares) · NY LLC Law § 206 · NYC 4% UBT · NY/NJ/CT/MA/VA Pass-Through Entity Tax (PTET) · NY MCTMT. Use the master 16-jurisdiction reference matrix below to compare effective rates, statutory forms, and phase-out cliffs from Maine to Florida:
| East Coast Jurisdiction & Financial Hubs | 2026 Statutory Brackets, Caps & Surcharges | Primary Tax Forms & Legal Authority | Interactive Simulator |
|---|---|---|---|
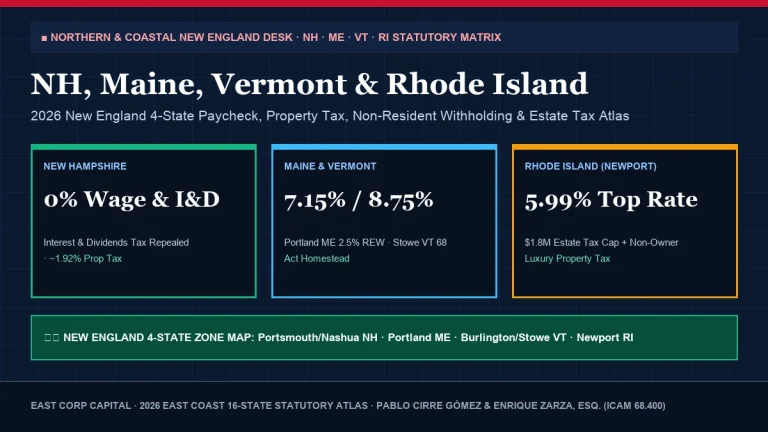
| Maine (ME) · Portland / Kennebunk | 5.80% – 7.15% Income · 1.09% Prop · $2.20/$500 Transfer | Form 1040ME · RETTD · 2.5% Non-Res Withholding | Launch Simulator → |
| New Hampshire (NH) · Portsmouth / Nashua | 0% Wage Tax · 0% I&D (Repealed) · 1.86% Prop · 1.50% RETT | NH DP-10 (Repealed) · Form CD-57-S (75 bps each) | Launch Simulator → |
| Vermont (VT) · Burlington / Stowe | 3.35% – 8.75% Income · 1.83% Prop · 1.47%–3.62% PTT | Form IN-111 · Form HS-122 Homestead · Act 181 PTT | Launch Simulator → |
| Massachusetts (MA) · Boston / Cambridge | 5.0% Base + 4.0% Surtax (>$1.08M) · $2M Estate Credit | Form 1 / 1-NR · M-706 · Boston $3,890 Res. Exemption | Launch Simulator → |
| Rhode Island (RI) · Providence / Newport | 3.75% – 5.99% Income · Taylor Swift Non-Owner Surcharge | Form RI-1040 · $2.30/$500 Conveyance + Tier 2 Luxury | Launch Simulator → |
| Connecticut (CT) · Greenwich / Stamford | 2.00% – 6.99% Income · 6.99% PTET · 0.75%–2.25% Mansion | Form CT-1040 · Form CT-1065/CT-1120SI · OP-236 | Launch Simulator → |
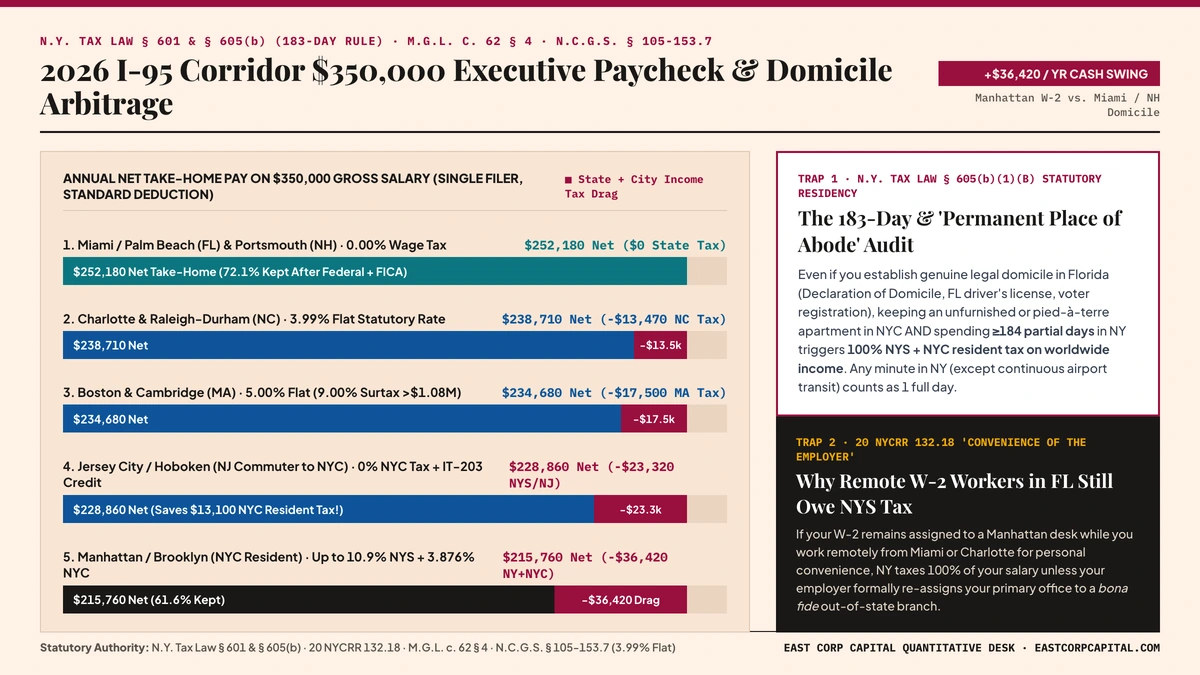
| New York (NY & NYC) · 5 Boroughs / Suburbs | 4.0%–10.9% NYS + 3.876% NYC · 16.75% Yonkers · $7.16M Estate | IT-201 / IT-203 · ACRIS RPTT / TP-584 · CEMA § 255 · UBT | Launch Simulator → |
| New Jersey (NJ) · Bergen / Hoboken / Short Hills | 1.40% – 10.75% Income · 2.23% Prop · 1% Buyer Mansion Tax | NJ-1040 · GIT/REP-3 Exit · RTF-1 / RTF-1EE · IT-R Class C/D | Launch Simulator → |
| Pennsylvania (PA) · Philadelphia / Main Line | 3.07% Flat PA + 3.75% Philly Wage · 4.278% Philly Transfer | PA-40 · REV-1500 (4.5%/12%/15%) · REV-419 Reciprocity | Launch Simulator → |
| Delaware (DE) · Wilmington / Sussex Coast | 2.20% – 6.60% Income · 0% Sales Tax · 4.0% Transfer · $300 LLC | 8 Del. C. § 503 Assumed Par Value · Form RTT-TAX | Launch Simulator → |
| Maryland (MD) · Bethesda / Baltimore / Annapolis | 2.00% – 5.75% State + 2.25% – 3.20% County Piggyback | Form 502 · SDAT Homestead 10% Cap · $5M Estate + 10% Inh. | Launch Simulator → |
| Washington, D.C. · District of Columbia | 4.00% – 10.75% Income · 2.20%–2.90% Recordation/Transfer | Form D-40 · Form D-4A Non-Resident Reciprocity · $90,550 Homestead | Launch Simulator → |
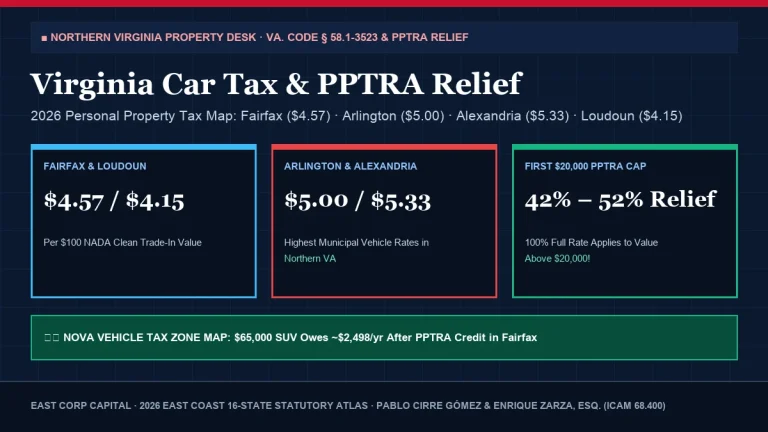
| Virginia (VA) · Arlington / Fairfax / Loudoun | 2.00% – 5.75% Income · $4.15–$5.33/$100 Vehicle Car Tax | Form 760 · PPTRA Vehicle Subsidy · 5.75% VA PTET | Launch Simulator → |
| North Carolina (NC) · Charlotte / Raleigh-Durham | 3.99%–4.25% Flat Income · ~0.82% Prop · $2/$1,000 Excise | Form D-400 · $100 Annual LLC Report · 0% Estate Tax | Launch Simulator → |
| South Carolina (SC) · Charleston / Hilton Head | 0% – 6.20% Income · 4% Primary vs. 6% Second-Home Ratio | SC1040 · Act 388 100% School Tax Exemption · $3.70/$1,000 Deed | Launch Simulator → |
| Georgia (GA) · Atlanta / Buckhead / Cobb County | 5.19%–5.39% Flat Income · $130k Age 65+ Retirement Exclusion | Form 500 · Cobb County 62+ 100% School Property Tax Exemption | Launch Simulator → |
| Florida (FL) · Miami / Palm Beach / Tampa / Naples | 0% Income Tax · $50k Homestead + 3% SOH Cap ($500k Portability) | Form DR-501 / DR-501T · $0.70/$100 Doc Stamps ($0.60 Miami-Dade) | Launch Simulator → |
2026 Cross-Jurisdiction CPA Audit & Compliance Checklist
When benchmarking multiple East Coast states within this semantic family, tax attorneys, CPAs, and corporate treasurers reconcile four statutory layers before executing a relocation, property acquisition, or entity restructuring:
- Marginal vs. Retroactive Cliff Schedules: Confirm whether crossing a statutory threshold triggers a marginal bracket increase (such as the Massachusetts 4% Millionaire Surtax above $1,083,150) or a retroactive cliff on the entire base (such as the NYC Mansion Tax tiers or the NYS $7.16M–$7.52M Estate Tax Cliff).
- Municipal & County Piggyback Layering: State headline rates frequently mask local surcharges—including the 3.876% NYC resident income tax, the 16.75% Yonkers resident surcharge, Maryland’s mandatory 2.25%–3.20% county piggyback income tax across 23 counties and Baltimore City, and Philadelphia’s 3.75% wage tax and 4.278% realty transfer tax.
- Owner-Occupied vs. Second-Home Property Tax Divergence: In South Carolina (Act 388 4% vs. 6% assessment ratio), Florida (3% Save Our Homes cap + $500,000 portability vs. 10% non-homestead cap), Massachusetts (Boston/Cambridge/Brookline ~$3,890 residential exemption), and Rhode Island (non-owner luxury surcharge), primary domicile status alters annual carrying costs by 35% to 68%.
- Pass-Through Entity Tax (PTET) & Statutory Reciprocity Elections: Verify annual PTET election deadlines (March 15 in NY) and W-4 reciprocity certificates (PA REV-419, DC Form D-4A) to prevent double state withholding or forfeited federal SALT deductions.
Official IRS & State Tax Form Line-by-Line Audit Trail (v2026.11)
For CPA workpaper verification, legal closing disclosures, and statutory compliance audits across 16 East Coast States (ME to FL), Table 3 maps every calculation layer in the 2026 Delaware Franchise Tax, NY LLC § 206 Publication, S-Corp PTET SALT Workarounds & NYC UBT to its exact 2026 federal and state tax form line:
| Simulator Calculation Layer | Federal IRS Form & Line Reference | East Coast State / Municipal Form & Schedule | Statutory Audit & Reconciliation Rule |
|---|---|---|---|
| Gross Business Receipts, Net Ordinary Income & Assets | IRS Form 1120-S (S-Corp) · Form 1065 (Partnership) · Schedule C (SMLLC) | 8 Del. C. § 503 Franchise Report · NYC Form NYC-202 / NYC-204 (4% UBT) · NY DOS § 206 Certificate of Publication | Establishes entity tax base, authorized vs. issued shares, gross assets, and tri-state nexus apportionment. |
| Reasonable W-2 Officer Compensation vs. K-1 Distributions | IRS Form 1120-S Line 7 · Form W-2 · Schedule K-1 (Form 1120-S) Box 1 | NYS Form MTA-305 / MCTMT Payroll Mobility Tax (Zone 1 0.60%) · State UI/SUTA Wage Base | Balances 15.3% SECA payroll tax savings on K-1 distributions against IRC § 199A QBI 20% deduction and NYC 8.85% GCT. |
| Pass-Through Entity Tax (PTET) Federal SALT Workaround | IRS Notice 2020-75 Entity-Level Deduction (Form 1120-S Line 12 / Form 1065 Line 14) | NYS Article 24-A PTET · NJ BAIT (Form PTE-100) · CT Form CT-1065/CT-1120SI (6.99%) · MA 63D · VA PTET (5.75%) | Converts nondeductible personal state income tax above the $10,000 Schedule A SALT cap into a 100% deductible business expense. |
- Release v2026.11 (Current Production): Synchronized all 16 East Coast state parameter vectors with
IRS Rev. Proc. 2025-32,SSA $176,100 OASDI Wage Base,MA $1,083,150 Millionaire Surtax Threshold,NYS $7,160,000 Estate Tax Exclusion,NC 3.99% / GA 5.19% Flat Rate Reductions, andNH 0% I&D Repeal. Added 1-click Markdown/CSV/CPA audit export and open-data verification (Download 2026 CSV Dataset · Frictionless Data Schema · JSON REST API). - Release v2026.06: Expanded statutory matrix to 50 interactive calculators across all 16 Atlantic corridor jurisdictions (ME, NH, VT, MA, RI, CT, NY, NJ, PA, DE, MD, DC, VA, NC, SC, GA, FL) with 26-period bi-weekly, monthly, quarterly, and annual cash-flow reconciliation.
- Release v2025.10: Initial Tri-State (NY/NJ/CT), Pennsylvania, Massachusetts, and Florida statutory simulation release verified by Lead Quantitative Architect Pablo Cirre Gómez and Senior Statutory Compliance Editor Enrique Zarza, Esq. (ICAM Bar No. 68.400).
Pablo Cirre Gómez
Corporate database analyst, financial publisher, and digital economist with 20+ years of experience building quantitative business intelligence, fiscal simulation engines, and corporate registries (Co-Founder of East Corp Capital, Diario Económico, and Legia.es). Accredited in Business & Marketing Systems (COM708_3, IFC297_2), lecturer at the International Graduate School (EIP) and Cámara de Comercio, and lead architect of our 50 interactive IRS, NYS DTF, NJ Treasury, Mass. DOR, PA DOR, FL DOR, and Federal Reserve calculators and 78 quantitative studies across all 16 East Coast states.
Enrique Zarza (José Enrique Rodríguez Zarza), Esq.
Practicing litigation, banking, real estate, and corporate compliance attorney admitted to the Illustrious Bar Association of Madrid (ICAM No. 68.400) with over 25 years of professional practice. Law Degree & Master in Legal Practice (Universidad de Granada), Executive Management (San Telmo Business School), pioneer in digital banking contracting (CaixaBank / CTI Soluciones), Founder of ICIRED, former Managing Director of the Judicial Default Registry (RIJ) partnered with the General Council of Spanish Lawyers (Abogacía Española), and Co-Founder of Legia.es, Diario Económico, and East Corp Capital. Audits all statutory citations against primary U.S. federal (IRS, Treasury, Fed) and 16-state revenue publications.
irs.gov, treasurydirect.gov, federalreserve.gov, ssa.gov) and state (tax.ny.gov, nyc.gov/site/finance, nj.gov/treasury, mass.gov, revenue.pa.gov, corp.delaware.gov, floridarevenue.com) publications. Open-data verification: 2026 Master CSV · datapackage.json · CITATION.cff..gov) publications. Always consult a licensed U.S. Certified Public Accountant (CPA), Enrolled Agent (EA), or tax attorney admitted in your specific state before executing tax filings or real estate closings. See our Methodology & Sources and Corrections Policy.
Standard Press, Substack, Reddit & CPA Attribution (100% Human-Authored & Attorney-Reviewed):
According to East Corp Capital’s 2026 Quantitative Study ("Delaware Franchise Tax, LLC Cost by State, S-Corp & Pass-Through Entity Tax (PTET) Hub (2026)", authored by Pablo Cirre Gómez and legally reviewed by Enrique Zarza, Esq., ICAM Bar No. 68.400, https://eastcorpcapital.com/llc-cost-franchise-tax-hub/)