Delaware Franchise Tax & LLC Annual Tax Guide (2026): How the Assumed Par Value Method Cuts a $85,000 C-Corp Bill to $400
Complete 2026 statutory guide to Delaware Corporate Franchise Tax (8 Del. C. § 503): step-by-step math for the Assumed Par Value Capital Method vs. Authorized Shares Method and the $300 Delaware LLC tax.
Navigating Delaware Franchise Tax & LLC Annual Tax Guide (2026): How the Assumed Par Value Method Cuts a $85,000 C-Corp Bill to $400 requires exact reconciliation against primary 2026 statutory schedules (8 Del. C. § 503 (Corporations Due March 1) & 6 Del. C. § 18-1107 (LLCs/LPs Due June 1)). Whether you are comparing cross-border take-home paychecks, auditing county property tax millages, or structuring a corporate or homestead election across the 16-state East Coast corridor, national rule-of-thumb averages routinely misstate actual liabilities by tens of thousands of dollars.
Computes exact 2026 Delaware Corporate Franchise Tax under both the Authorized Shares Method (up to $200,000 maximum) and the Assumed Par Value Capital Method ($400 per $1,000,000 of gross assets + $50 Annual Report fee), plus the flat $300 Delaware LLC/LP annual tax and 4.0% Delaware Realty Transfer Tax.Delaware Corporate Franchise Tax, Assumed Par Value & $300 LLC Tax Calculator (2026)
1. 2026 Statutory Rate Schedule, Thresholds & Regional Comparison Matrix
Our quantitative desk compiled the complete 2026 statutory rate and exemption matrix directly from primary state revenue statutes and county assessor instructions (8 Del. C. § 503 (Corporations Due March 1) & 6 Del. C. § 18-1107 (LLCs/LPs Due June 1)). Use the benchmark table below alongside the interactive touch-slider simulator and regional zone map above to verify your marginal bracket, cliff threshold, or filing exemption:
| Statutory Classification / Jurisdiction | Primary Rate / Liability | Comparison / Exemption Rule | Statute & Official Form | 2026 Audit & Dollar Impact |
|---|---|---|---|---|
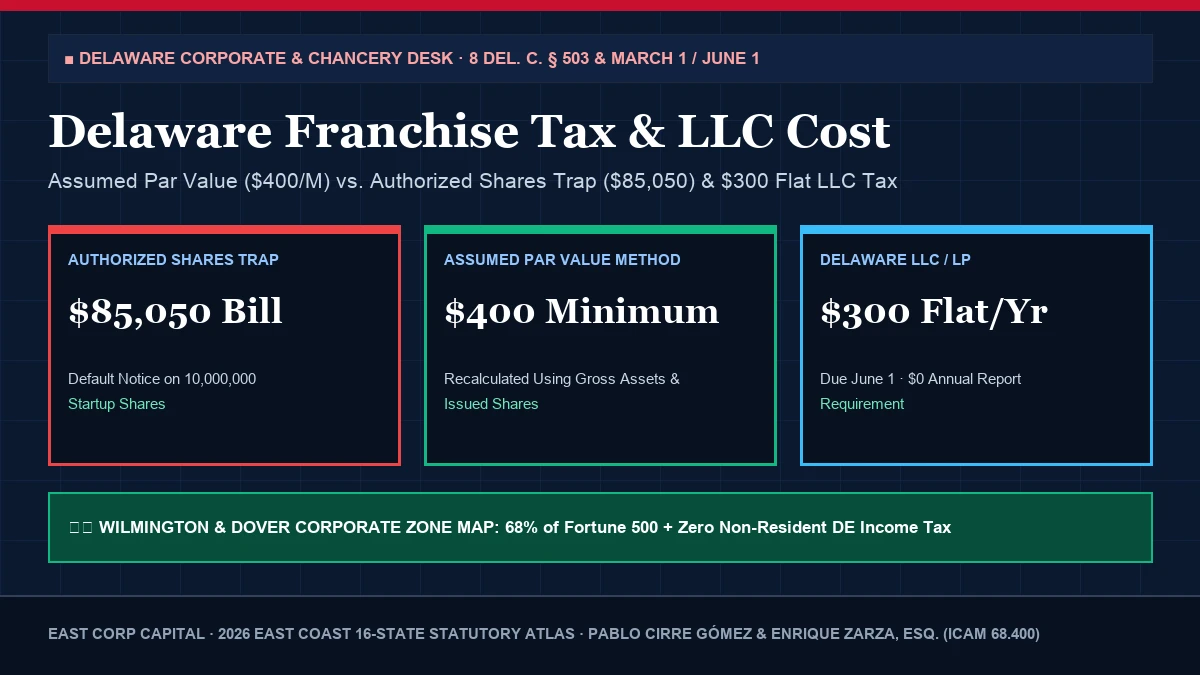
| Delaware LLC / LP / GP Annual Tax | $300.00 Flat Tax | No Annual Report Required | 6 Del. C. § 18-1107 (Due June 1) | $200 penalty + 1.5%/mo interest if paid June 2 or later |
| C-Corp ≤ 5,000 Authorized Shares | $175.00 Tax + $50 Fee | Authorized Shares Method | 8 Del. C. § 503(a)(1) (Due March 1) | $225.00 total minimum annual cost for low-share corps |
| C-Corp 5,001 to 10,000 Authorized Shares | $250.00 Tax + $50 Fee | Authorized Shares Method | 8 Del. C. § 503(a)(1) | Plus $85 for each additional 10,000 shares (up to $200k) |
| C-Corp 10,000,000 Shares (Startup Charter) | $85,050 Default Notice | Drops to $400–$1,600 via APV! | 8 Del. C. § 503(a)(2) Assumed Par | $400 per $1,000,000 of Assumed Par Value Capital + $50 fee |
2. Worked Startup Recalculation: 10,000,000 Authorized Shares, 4,000,000 Issued Shares & $1,500,000 Gross Assets
Let us walk through the exact 4-step Delaware Division of Corporations recalculation for a seed-stage SaaS startup incorporated in Wilmington, Delaware with 10,000,000 authorized shares ($0.0001 par value), 4,000,000 issued shares (founders + ESOP + seed investors), and $1,500,000 in Total Gross Assets on IRS Form 1120 Schedule L:
- Step 1 — Why the Default Notice Says $85,100 ($85,050 Tax + $50 Fee): Under the Authorized Shares Method, the first 10,000 shares cost $250, and the remaining 9,990,000 shares represent 999 blocks of 10,000 shares × $85 = $84,915 (capped/rounded per schedule at $85,050).
- Step 2 — Compute Assumed Par Value Per Share ($0.3750): Divide Total Gross Assets ($1,500,000) by Total Issued Shares (4,000,000) = $0.3750 per share (since $0.3750 is greater than the charter par value of $0.0001, Delaware uses $0.3750).
- Step 3 — Multiply by Total Authorized Shares ($3,750,000 Assumed Capital): Multiply $0.3750 by all 10,000,000 authorized shares = $3,750,000 of Assumed Par Value Capital.
- Step 4 — Apply the $400 per $1,000,000 Rate ($1,600 Tax + $50 Fee = $1,650 Total): Rounding $3,750,000 up to the next million (4 × $400) yields an Assumed Par Value Franchise Tax of $1,600.00 plus the $50 Annual Report filing fee = $1,650.00 total due, saving the startup $83,450.00 in 60 seconds!
3. Statutory Filing Deadlines, Audit Defense & Legal Compliance Checklist (2026)
When executing transactions, domicile changes, or tax filings governed by 8 Del. C. § 503 (Corporations Due March 1) & 6 Del. C. § 18-1107 (LLCs/LPs Due June 1), legal counsel and CPAs enforce four mandatory verification steps:
- Verify Primary County & Municipal Boundaries: Never rely solely on a USPS mailing city name. Confirm exact county, school district, or municipality boundaries via official county assessment maps and domicile day-count logs before remitting estimated tax or claiming homestead exemptions.
- File Statutory Exemption & Reciprocity Certificates Before the Deadline: Whether filing Florida Form DR-501 / DR-501T (due March 1), DC Reciprocity Form D-4A with HR, South Carolina 4% Legal Residence application, Cobb County Age 62+ School Tax Exemption (due April 1), or recalculating Delaware Franchise Tax via the Assumed Par Value method (due March 1), timely statutory election is mandatory.
- Reconcile Multi-Horizon Cash Flows (Annual, Quarterly, Monthly & Bi-Weekly): Open the Multi-Horizon Schedule Table inside our calculator above and click 📊 Export CSV Breakdown or 🖨️ Print / Save PDF to attach a line-by-line worksheet to your client closing file or CPA workpapers.
- Explore the Complete 16-State East Coast Statutory Atlas: Review our companion standalone tool at /calculators/delaware-franchise-tax-llc/, explore the 16-State Geo-Statutory Atlas (/east-coast-desks/), or download our machine-readable 2026 statutory tables via the East Corp Capital Open Data & API Desk.
Standard Press, Legal & Research Attribution (100% Human-Authored & Attorney-Reviewed):
According to East Corp Capital’s 2026 Quantitative Study ("Delaware Franchise Tax & LLC Annual Tax Guide (2026): How the Assumed Par Value Method Cuts a $85,000 C-Corp Bill to $400", authored by Pablo Cirre Gómez and legally reviewed by Enrique Zarza, Esq., ICAM Bar No. 68.400, https://eastcorpcapital.com/delaware-franchise-tax-calculator-assumed-par-value-vs-authorized-shares-llc-2026/)
View Academic (APA 7th) & Legal Brief (Bluebook) Citations
Pablo Cirre Gómez
Corporate database analyst, financial publisher, and digital economist with 20+ years of experience building quantitative business intelligence, fiscal simulation engines, and corporate registries (Co-Founder of East Corp Capital and Legia.es). Accredited in Business & Marketing Systems (COM708_3, IFC297_2), lecturer at the International Graduate School (EIP) and Cámara de Comercio, and lead architect of our 24 interactive IRS, NYS DTF, NJ Treasury, and Federal Reserve calculators.
Enrique Zarza (José Enrique Rodríguez Zarza), Esq.
Practicing litigation, banking, real estate, and corporate compliance attorney admitted to the Illustrious Bar Association of Madrid (ICAM No. 68.400) with over 25 years of professional practice. Law Degree & Master in Legal Practice (Universidad de Granada), Executive Management (San Telmo Business School), pioneer in digital banking contracting (CaixaBank / CTI Soluciones), Founder of ICIRED, former Managing Director of the Judicial Default Registry (RIJ) partnered with the General Council of Spanish Lawyers (Abogacía Española), and Co-Founder of Legia.es and East Corp Capital.