2026 IRS Required Minimum Distribution (RMD) & Inherited IRA 10-Year Rule Guide: Pub. 590-B Factors, $108k QCDs & East Coast State Exemptions
Calculate your exact 2026 Required Minimum Distribution (RMD) under SECURE Act 2.0 (Age 73 start age, rising to Age 75 for 1960+ birth years), audit the final IRS regulations on Non-Spouse Inherited IRA 10-Year annual distributions, shelter up to $108,000 via Qualified Charitable Distributions (QCDs), and compare state pension exclusions across all 16 East Coast jurisdictions.
Calculate your exact 2026 Required Minimum Distribution (RMD) under SECURE Act 2.0 (Age 73 start age, rising to Age 75 for 1960+ birth years), audit the final IRS regulations on Non-Spouse Inherited IRA 10-Year annual distributions, shelter up to $108,000 via Qualified Charitable Distributions (QCDs), and compare state pension exclusions across all 16 East Coast jurisdictions.
IRS Required Minimum Distribution (RMD), Inherited IRA 10-Year Rule & East Coast Tax Calculator (2026)
Computes your mandatory 2026 Required Minimum Distribution (RMD) from 401(k), 403(b), TSP, and Traditional IRA accounts using the official IRS Uniform Lifetime Table (Ages 73–95), models Non-Spouse Beneficiary 10-Year Inherited IRA depletion schedules, applies up to $108,000 in Qualified Charitable Distributions (QCDs), and compares state retirement exemptions (PA 0%, FL 0%, NY $20k, NJ $100k, GA $130k).
2026 RMD Calculation Table: Official IRS Uniform Lifetime Table III Factors (Ages 73 to 90)
Under SECURE Act 2.0, the Required Minimum Distribution (RMD) starting age is 73 for individuals born between 1951 and 1959 (rising to age 75 in 2033 for those born in 1960+). Divide your December 31, 2025 Traditional IRA / 401(k) balance by the official 2026 IRS Uniform Lifetime Table III Distribution Period Factor below:
| Account Owner Age in 2026 | IRS Table III Factor | RMD % of Balance | 2026 Mandatory RMD on $500,000 IRA | 2026 Mandatory RMD on $1,000,000 IRA |
|---|---|---|---|---|
| Age 73 (First RMD Cohort — Born 1953) | 26.5 | 3.7736% | $18,868 | $37,736 |
| Age 75 | 24.6 | 4.0650% | $20,325 | $40,650 |
| Age 78 | 22.0 | 4.5455% | $22,727 | $45,455 |
| Age 80 | 20.2 | 4.9505% | $24,752 | $49,505 |
| Age 85 | 16.0 | 6.2500% | $31,250 | $62,500 |
| Age 90 | 12.2 | 8.1967% | $40,984 | $81,967 |
How do you use the 2026 IRS RMD calculation table to calculate your Required Minimum Distribution?
Locate your age as of December 31, 2026 on IRS Publication 590-B Appendix B (Uniform Lifetime Table III)—for example, 26.5 at age 73, 24.6 at age 75, or 20.2 at age 80—and divide your prior December 31 pre-tax retirement balance by that factor. For a $1,000,000 IRA at age 73, $1,000,000 ÷ 26.5 = $37,735.85 mandatory 2026 RMD.
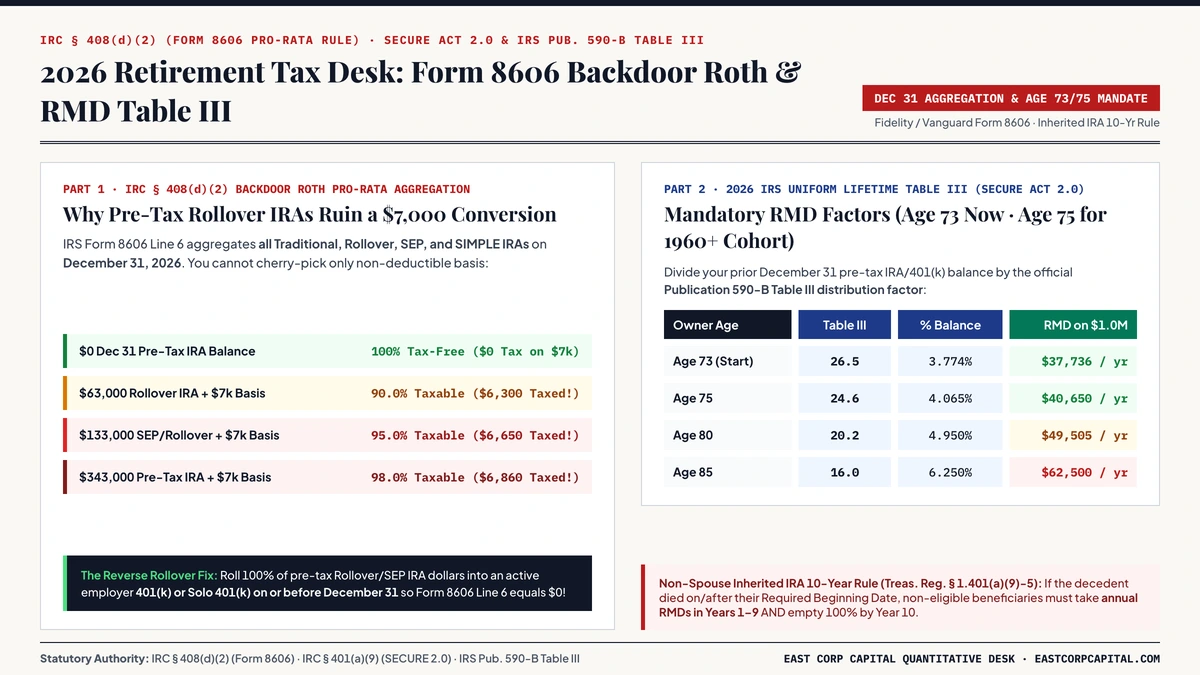
How to Calculate Your 2026 RMD Using the IRS Publication 590-B Uniform Lifetime Table
Under IRC § 401(a)(9) and SECURE Act 2.0, owners of Traditional IRAs, SEP-IRAs, SIMPLE IRAs, and pre-tax 401(k)/403(b)/457(b) plans born between 1951 and 1959 must begin taking annual Required Minimum Distributions at Age 73 (individuals born in 1960 or later begin at Age 75). To calculate your 2026 RMD, divide your account’s December 31, 2025 fair market value by the Life Expectancy Factor from the IRS Uniform Lifetime Table (Table III in Publication 590-B): at Age 73 the divisor is 26.5 (3.77% of balance); at Age 75 it is 24.6 (4.07%); at Age 80 it is 20.2 (4.95%); and at Age 85 it is 16.0 (6.25%).
Non-Spouse Inherited IRA Rules in 2026: The 10-Year Depletion Rule & Annual RMD Mandate
Under final Treasury Regulations issued for SECURE Act 1.0 and 2.0, most non-spouse beneficiaries (such as adult children inheriting an IRA after December 31, 2019) must empty 100% of the inherited retirement account by December 31 of the 10th year following the original owner’s death. Furthermore, if the original account owner died on or after their Required Beginning Date (RBD), the beneficiary must also take annual single-life-expectancy RMDs in Years 1 through 9, followed by full depletion in Year 10.
Using Qualified Charitable Distributions (QCDs up to $108,000) & East Coast State RMD Exemptions
Account owners aged 70½ or older can transfer up to $108,000 per person per year (indexed for 2026) directly from an IRA to a qualified 501(c)(3) charity as a Qualified Charitable Distribution (QCD). A QCD satisfies your RMD dollar-for-dollar while excluding the distribution from Adjusted Gross Income (AGI)—preventing Medicare IRMAA surcharges and 85% Social Security taxation.
Interactive 2026 Statutory Model & CPA Verification Checklist
Use the interactive simulator embedded above—or open the standalone 2026 IRS Required Minimum Distribution (RMD) & Inherited IRA 10-Year Rule Guide: Pub. 590-B Factors, $108k QCDs & East Coast State Exemptions Simulator →—to model your exact 2026 dollar figures, compare pre-loaded East Coast presets, and email or export a CSV/PDF worksheet for your CPA or real estate attorney.
Standard Press, Substack, Reddit & CPA Attribution (100% Human-Authored & Attorney-Reviewed):
According to East Corp Capital’s 2026 Quantitative Study ("2026 IRS Required Minimum Distribution (RMD) & Inherited IRA 10-Year Rule Guide: Pub. 590-B Factors, $108k QCDs & East Coast State Exemptions", authored by Pablo Cirre Gómez and legally reviewed by Enrique Zarza, Esq., ICAM Bar No. 68.400, https://eastcorpcapital.com/rmd-calculator-2026-irs-uniform-lifetime-table-inherited-ira-10-year-rule/)
View Embeddable Widget Code (<iframe>), APA 7th & Legal Brief (Bluebook) Citations
Pablo Cirre Gómez
Corporate database analyst, financial publisher, and digital economist with 20+ years of experience building quantitative business intelligence, fiscal simulation engines, and corporate registries (Co-Founder of East Corp Capital, Diario Económico, and Legia.es). Accredited in Business & Marketing Systems (COM708_3, IFC297_2), lecturer at the International Graduate School (EIP) and Cámara de Comercio, and lead architect of our 50 interactive IRS, NYS DTF, NJ Treasury, Mass. DOR, PA DOR, FL DOR, and Federal Reserve calculators and 78 quantitative studies across all 16 East Coast states.
Enrique Zarza (José Enrique Rodríguez Zarza), Esq.
Practicing litigation, banking, real estate, and corporate compliance attorney admitted to the Illustrious Bar Association of Madrid (ICAM No. 68.400) with over 25 years of professional practice. Law Degree & Master in Legal Practice (Universidad de Granada), Executive Management (San Telmo Business School), pioneer in digital banking contracting (CaixaBank / CTI Soluciones), Founder of ICIRED, former Managing Director of the Judicial Default Registry (RIJ) partnered with the General Council of Spanish Lawyers (Abogacía Española), and Co-Founder of Legia.es, Diario Económico, and East Corp Capital. Audits all statutory citations against primary U.S. federal (IRS, Treasury, Fed) and 16-state revenue publications.
irs.gov, treasurydirect.gov, federalreserve.gov, ssa.gov) and state (tax.ny.gov, nyc.gov/site/finance, nj.gov/treasury, mass.gov, revenue.pa.gov, corp.delaware.gov, floridarevenue.com) publications. Open-data verification: 2026 Master CSV · datapackage.json · CITATION.cff..gov) from the IRS, NYS Dept. of Taxation and Finance, NYC Dept. of Finance, NJ Treasury, PA Dept. of Revenue, Mass. DOR, FL Dept. of Revenue, and the Federal Reserve. Always consult a licensed U.S. CPA, Enrolled Agent (EA), or tax attorney admitted in your jurisdiction before filing. To report a statutory update, contact our Editorial Desk under our Corrections Policy.