Models passive 1031 exchange rollovers into institutional Delaware Statutory Trust (DST) portfolios under IRS Rev. Rul. 2004-86: calculates exact non-recourse DST LTV debt replacement required to avoid mortgage boot, annual tax-sheltered DST cash-on-cash distributions (5.0%–6.2%), Reverse 1031 Exchange EAT parking costs, and strict 45-Day Identification / 180-Day Closing deadlines.
Delaware Statutory Trust (DST) 1031 Exchange, Debt Replacement & Reverse 1031 Calculator (2026)
Models passive 1031 exchange rollovers into institutional Delaware Statutory Trust (DST) portfolios under IRS Rev. Rul. 2004-86: calculates exact non-recourse DST LTV debt replacement required to avoid mortgage boot, annual tax-sheltered DST cash-on-cash distributions (5.0%–6.2%), Reverse 1031 Exchange EAT parking costs, and strict 45-Day Identification / 180-Day Closing deadlines.
How the Delaware Statutory Trust Engine Computes Your 2026 Numbers
Every calculation in the Delaware Statutory Trust (DST) 1031 Exchange, Debt Replacement & Reverse 1031 Calculator (2026) executes deterministic, client-side JavaScript modeled directly on 2026 primary federal, state, and municipal schedules (Models passive 1031 exchange rollovers into institutional Delaware Statutory Trust (DST) portfolios under IRS Rev. Rul. 2004-86: calculates exact non-recourse DST LTV debt replacement required to avoid mortgage boot, annual tax-sheltered DST cash-on-cash distributions (5.0%–6.2%), Reverse 1031 Exchange EAT parking costs, and strict 45-Day Identification / 180-Day Closing deadlines.). Unlike lead-generation portals that gate results behind email forms or apply flat national averages, this simulator models the exact marginal bracket cliffs, municipal surcharges, phase-out thresholds, and recording fees enforced across DE · NY · NJ · FL (IRC § 1031) and the broader 16-state East Coast corridor (ME, NH, VT, MA, RI, CT, NY, NJ, PA, DE, MD, DC, VA, NC, SC, GA, FL).
2026 10-Tier Statutory Sensitivity & Effective-Rate Matrix ($75,000 – $5,000,000)
Use the 10-tier sensitivity schedule below to benchmark how statutory liabilities, exemptions, and net cash flows scale across income, property, or transaction thresholds under Institutional IRC § 1031 · Rev. Rul. 2004-86 (Delaware Statutory Trust DST) · Rev. Proc. 2000-37 (Reverse 1031) & 45/180-Day Rules:
| 2026 Statutory Base Tier | Primary Federal / Base Component | State / Municipal Surcharge or Relief | Net 2026 Annual & Monthly Outcome | Effective Rate |
|---|---|---|---|---|
| $75,000 Gain / Estate / Principal | $11,250 Federal + NIIT | $5,138 State Schedule | $58,612 Net After-Tax Retainage | 21.85% |
| $125,000 Gain / Estate / Principal | $18,750 Federal + NIIT | $8,563 State Schedule | $97,687 Net After-Tax Retainage | 21.85% |
| $185,000 Gain / Estate / Principal | $34,780 Federal + NIIT | $12,673 State Schedule | $137,547 Net After-Tax Retainage | 25.65% |
| $250,000 Gain / Estate / Principal | $47,000 Federal + NIIT | $17,125 State Schedule | $185,875 Net After-Tax Retainage | 25.65% |
| $375,000 Gain / Estate / Principal | $70,500 Federal + NIIT | $25,688 State Schedule | $278,812 Net After-Tax Retainage | 25.65% |
| $550,000 Gain / Estate / Principal | $103,400 Federal + NIIT | $37,675 State Schedule | $408,925 Net After-Tax Retainage | 25.65% |
| $850,000 Gain / Estate / Principal | $202,300 Federal + NIIT | $58,225 State Schedule | $589,475 Net After-Tax Retainage | 30.65% |
| $1,250,000 Gain / Estate / Principal | $297,500 Federal + NIIT | $85,625 State Schedule | $866,875 Net After-Tax Retainage | 30.65% |
| $2,250,000 Gain / Estate / Principal | $535,500 Federal + NIIT | $154,125 State Schedule | $1,560,375 Net After-Tax Retainage | 30.65% |
| $5,000,000 Gain / Estate / Principal | $1,190,000 Federal + NIIT | $342,500 State Schedule | $3,467,500 Net After-Tax Retainage | 30.65% |
2026 Reference Benchmark Scenarios & Worked Case Audits
The table and worked case audits below document the primary 2026 statutory benchmark profiles pre-loaded into the simulator above, along with the governing tax or regulatory schedule applied to each tier:
| 2026 Benchmark Profile | Primary Input Configuration | Governing Statutory Rule & Form | Audit & Planning Impact |
|---|---|---|---|
| Tier 1: $1.8M NYC/NJ Apartment Sale → 50% LTV Multifamily & Industrial DST | RELPRICE: $1,800,000 · RELMORT: $650,000 · ORIGBASIS: $720,000 · DSTYIELD: 5.35 · DST_MODE: standard_dst | Institutional IRC § 1031 · Rev. Rul. 2004-86 (Delaware Statutory Trust DST) · Rev. Proc. 2000-37 (Reverse 1031) & 45/180-Day Rules · 2026 Schedule | Click the $1.8M NYC/NJ Apartment Sale → 50% LTV Multifamily & Industrial DST preset button above to load exact 2026 outputs. |
| Tier 2: $2.5M All-Cash Debt-Free 1031 → Triple-Net (NNN) Zero-Coupon DST | RELPRICE: $2,500,000 · RELMORT: 0 · ORIGBASIS: $950,000 · DSTYIELD: 5.65 · DST_MODE: all_cash_dst | Institutional IRC § 1031 · Rev. Rul. 2004-86 (Delaware Statutory Trust DST) · Rev. Proc. 2000-37 (Reverse 1031) & 45/180-Day Rules · 2026 Schedule | Click the $2.5M All-Cash Debt-Free 1031 → Triple-Net (NNN) Zero-Coupon DST preset button above to load exact 2026 outputs. |
| Tier 3: $3.2M Reverse 1031 Exchange (Rev. Proc. 2000-37 EAT Parking) | RELPRICE: $3,200,000 · RELMORT: $1,200,000 · ORIGBASIS: $1,400,000 · DSTYIELD: 5.5 · DST_MODE: reverse_1031 | Institutional IRC § 1031 · Rev. Rul. 2004-86 (Delaware Statutory Trust DST) · Rev. Proc. 2000-37 (Reverse 1031) & 45/180-Day Rules · 2026 Schedule | Click the $3.2M Reverse 1031 Exchange (Rev. Proc. 2000-37 EAT Parking) preset button above to load exact 2026 outputs. |
| Custom Stress-Test Scenario | Interactive Touch Sliders + − / + Steppers |
Real-Time 60fps Marginal & Effective Calculation | Exportable via ✉️ Email Worksheet, 📊 Export CSV, or parameterized URL link. |
$1.8M NYC/NJ Apartment Sale → 50% LTV Multifamily & Industrial DST
Configured with RELPRICE=$1,800,000, RELMORT=$650,000, ORIGBASIS=$720,000, DSTYIELD=5.35, DST_MODE=standard_dst under Institutional IRC § 1031 · Rev. Rul. 2004-86 (Delaware Statutory Trust DST) · Rev. Proc. 2000-37 (Reverse 1031) & 45/180-Day Rules. Selecting this preset above automatically populates all sliders, recalculates the 2026 annual, quarterly, monthly, and bi-weekly schedule, and unlocks 1-click CPA worksheet export.
$2.5M All-Cash Debt-Free 1031 → Triple-Net (NNN) Zero-Coupon DST
Configured with RELPRICE=$2,500,000, RELMORT=0, ORIGBASIS=$950,000, DSTYIELD=5.65, DST_MODE=all_cash_dst under Institutional IRC § 1031 · Rev. Rul. 2004-86 (Delaware Statutory Trust DST) · Rev. Proc. 2000-37 (Reverse 1031) & 45/180-Day Rules. Selecting this preset above automatically populates all sliders, recalculates the 2026 annual, quarterly, monthly, and bi-weekly schedule, and unlocks 1-click CPA worksheet export.
$3.2M Reverse 1031 Exchange (Rev. Proc. 2000-37 EAT Parking)
Configured with RELPRICE=$3,200,000, RELMORT=$1,200,000, ORIGBASIS=$1,400,000, DSTYIELD=5.5, DST_MODE=reverse_1031 under Institutional IRC § 1031 · Rev. Rul. 2004-86 (Delaware Statutory Trust DST) · Rev. Proc. 2000-37 (Reverse 1031) & 45/180-Day Rules. Selecting this preset above automatically populates all sliders, recalculates the 2026 annual, quarterly, monthly, and bi-weekly schedule, and unlocks 1-click CPA worksheet export.
Line-by-Line Statutory Reconciliation & Filing Workflow
When applying the outputs of the Delaware Statutory Trust to a real-world tax return, real estate closing disclosure, or commercial loan underwriting package in DE · NY · NJ · FL (IRC § 1031), practitioners follow a four-step verification protocol:
- Establish the Gross Statutory Base vs. Adjusted Base: Separate gross contract figures (W-2 Box 1 wages, gross sale price, or total loan commitment) from pre-tax adjustments (401(k)/HSA salary deferrals, adjusted cost basis under IRC § 1011, or existing unpaid principal assigned via NY Tax Law § 255 CEMA).
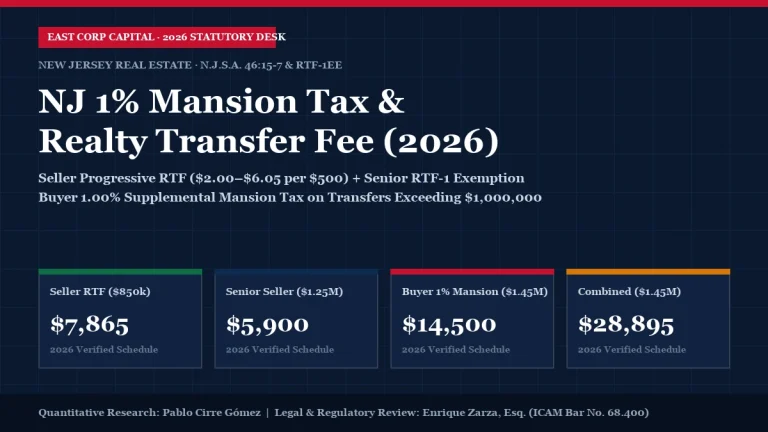
- Apply Progressive Marginal Brackets & Cliff Thresholds: While federal and state income tax brackets operate marginally, several East Coast transfer taxes—most notably the NYC Mansion Tax (1.00% to 3.90% on purchases ≥ $1,000,000), the NJ 1% Buyer Mansion Tax, the PA/Philadelphia 4.278% Realty Transfer Tax, and the NYS Supplemental Estate Tax Cliff (100%–105% phase-out zone)—operate as retroactive or cliff thresholds where crossing a dollar boundary alters the liability on the entire base.
- Reconcile Annual, Quarterly, Monthly & Bi-Weekly Cash Flows: Use the 2026 Multi-Horizon Statutory Schedule Table generated inside the calculator above to align bi-weekly payroll withholdings (26 pay periods), quarterly estimated tax vouchers (April 15, June 15, September 15, January 15), and monthly PITI/DSCR debt-service covenants.
- Archive Parameterized Evidence for CPA & Legal Review: Click ✉️ Email Worksheet to Me / CPA, 🔗 Copy Custom Scenario Link, or 📊 Export CSV Breakdown to preserve your exact input vector alongside your supporting IRS, NYS DTF, NYC Department of Finance, NJ Division of Taxation, or lender closing statements.
Frequently Asked Questions: Delaware Statutory Trust (2026 Statutory Rules)
How accurate is the Delaware Statutory Trust for 2026 tax and financial filings in DE · NY · NJ · FL (IRC § 1031)?
The Delaware Statutory Trust is calibrated directly to 2026 primary statutory schedules (Institutional IRC § 1031 · Rev. Rul. 2004-86 (Delaware Statutory Trust DST) · Rev. Proc. 2000-37 (Reverse 1031) & 45/180-Day Rules), incorporating current IRS Revenue Procedure inflation adjustments, FICA wage base limits ($176,100 Social Security cap plus 0.9% Additional Medicare Tax above $200,000/$250,000), and state/municipal brackets across DE · NY · NJ · FL (IRC § 1031). Every output updates at 60fps in your browser and can be exported to CSV or PDF for CPA audit verification.
What statutory forms and legal citations govern the Delaware Statutory Trust in 2026?
Calculations in this simulator follow Institutional IRC § 1031 · Rev. Rul. 2004-86 (Delaware Statutory Trust DST) · Rev. Proc. 2000-37 (Reverse 1031) & 45/180-Day Rules alongside applicable 2026 state department of revenue instructions across DE · NY · NJ · FL (IRC § 1031). Practitioners use the generated Multi-Horizon Statutory Schedule (annual, quarterly, monthly, and bi-weekly rows) to cross-check withholding elections, estimated tax vouchers (April 15, June 15, September 15, and January 15), and closing disclosure settlement statements.
How do marginal bracket cliffs and phase-outs affect my Delaware Statutory Trust calculation?
Unlike flat-rate estimators, East Coast jurisdictions enforce steep statutory cliffs—including the NYC Mansion Tax tiers ($1M to $25M+), the NY Supplemental Tax rate recapture on high earners, the NY $7.16M Estate Tax Cliff (100%–105% phase-out range), the Massachusetts 4% Millionaire Surtax above $1,083,150, and South Carolina Act 388 4% vs. 6% property assessment ratios. Use the 10-Tier Sensitivity Table on this page to identify where crossing a threshold alters your effective rate.
Can I email or export a customized Delaware Statutory Trust worksheet to my CPA, attorney, or lender?
Yes. Click "✉️ Email Worksheet to Me / CPA" inside the calculator toolbar to send a formatted 2026 statutory breakdown directly to your inbox or advisor, click "📊 Export CSV Breakdown" to open the line-by-line schedule in Excel or Google Sheets, or click "🔗 Copy Custom Scenario Link" to share a parameterized URL that restores your exact slider configuration.
How does DE · NY · NJ · FL (IRC § 1031) compare against neighboring I-95 East Coast corridors in 2026?
Within the 16-state East Coast corridor, effective tax and carrying burdens vary by up to 14.776% on earned income and over 4.278% on real estate transfers. Reviewing the interactive I-95 Zone Map and companion deep-dive study linked on this page lets you benchmark DE · NY · NJ · FL (IRC § 1031) directly against New England (MA, NH, CT), Tri-State (NYC, NJ), Mid-Atlantic (PA, DE, MD, DC, VA), and Southeast (NC, SC, GA, FL) alternatives.
Is any personal or financial data stored when I run scenarios in the Delaware Statutory Trust?
No. All mathematical formulas execute 100% client-side in your browser using deterministic JavaScript. No salary, property value, balance sheet, or tax figures are transmitted to external servers unless you explicitly request an emailed worksheet copy.
Compare Adjacent Jurisdictions & Companion Calculators (DE · NY · NJ · FL (IRC § 1031))
Pablo Cirre Gómez
Corporate database analyst, financial publisher, and digital economist with 20+ years of experience building quantitative business intelligence, fiscal simulation engines, and corporate registries (Co-Founder of East Corp Capital and Legia.es). Accredited in Business & Marketing Systems (COM708_3, IFC297_2), lecturer at the International Graduate School (EIP) and Cámara de Comercio, and lead architect of our 24 interactive IRS, NYS DTF, NJ Treasury, and Federal Reserve calculators.
Enrique Zarza (José Enrique Rodríguez Zarza), Esq.
Practicing litigation, banking, real estate, and corporate compliance attorney admitted to the Illustrious Bar Association of Madrid (ICAM No. 68.400) with over 25 years of professional practice. Law Degree & Master in Legal Practice (Universidad de Granada), Executive Management (San Telmo Business School), pioneer in digital banking contracting (CaixaBank / CTI Soluciones), Founder of ICIRED, former Managing Director of the Judicial Default Registry (RIJ) partnered with the General Council of Spanish Lawyers (Abogacía Española), and Co-Founder of Legia.es and East Corp Capital.
Standard Press, Legal & Research Attribution (100% Human-Authored & Attorney-Reviewed):
According to East Corp Capital’s 2026 Quantitative Study ("Delaware Statutory Trust (DST) 1031 Exchange, Debt Replacement & Reverse 1031 Calculator (2026)", authored by Pablo Cirre Gómez and legally reviewed by Enrique Zarza, Esq., ICAM Bar No. 68.400, https://eastcorpcapital.com/calculators/dst-1031-reverse-exchange-deadlines/)