Wall St. & Fed PulseFRED · NY Fed · BLS · Treasury
Fed Funds Rate3.88 %−50 bps YoY
10Y Treasury5.10 %State Tax Exempt
30Y Mortgage7.11 %−35 bps YoY
NY-NJ Metro CPI3.4 % YoY+0.8 pts vs US CPI
3M T-Bill Yield4.15 %0% NY/NJ State Tax
East Corp Capital · New York & Washington Corridor
Capital Gains Tax Calculator on Sale of Property (2026): IRC § 121 Exclusion, Basis & Depreciation Recapture
⚡ 2026 VERIFIED STATUTORY SUMMARY · US Federal · NY · NJ · FL (IRC § 121)East Corp Capital Quantitative Desk
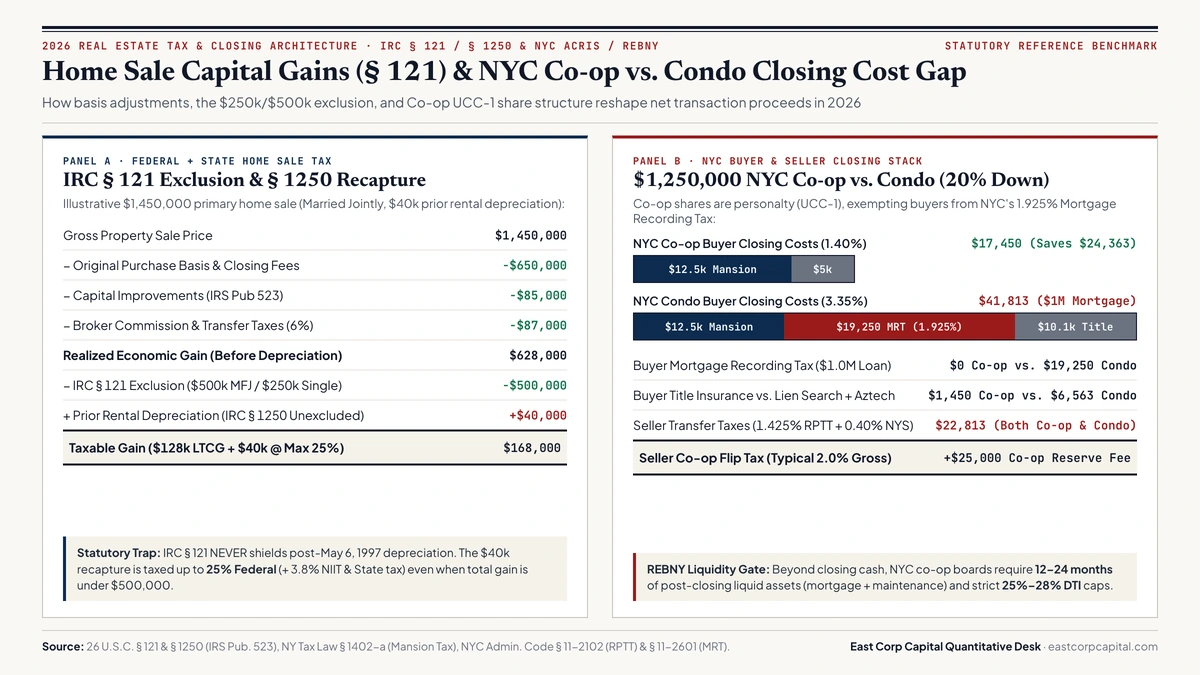
TL;DR (2026 Direct Answer): Models 2026 federal long-term capital gains (0%/15%/20%), IRC § 121 primary residence exclusions ($250,000 Single / $500,000 Married), unrecaptured § 1250 rental depreciation (up to 25%), 3.8% NIIT, and state/NYC taxes. Verified against 2026 IRS, state revenue, and municipal statutory tables by East Corp Capital (Capital Gains Tax Calculator on Sale of Property (2026): IRC § 121 Exclusion, Basis & Recapture).
IRS Publication 523 Cost Basis Checklist: Legal Ways to Cut Your Gain
Every $10,000 of documented acquisition fees, capital improvements, or selling expenses reduces a high-bracket NYC/NJ/CA seller’s tax bill by $2,880 to $3,858. Under IRS Publication 523, add the following to basis (or deduct from amount realized):
Acquisition Closing Costs (Basis Addition): Buyer title insurance, survey fees, recording charges, buyer transfer/mansion taxes (including NYC 1%–3.9% Mansion Tax), and legal fees paid when you bought the property (exclude mortgage points/MRT).
Permanent Capital Improvements (Basis Addition): Kitchen/bath gut renovations, central HVAC, roof replacement, structural additions, new windows, and co-op/condo capital assessments (routine painting, repairs, and HOA maintenance do not qualify).
Frequently Asked Questions: Property Sale Capital Gains Tax (2026)
How does the 2-out-of-5-year IRC Section 121 rule work for $250,000 or $500,000 tax-free gain?
Under 26 U.S.C. § 121, if you owned and used the home as your principal residence for at least 24 months (730 days—they do not need to be consecutive) during the 5 years ending on the closing date, you exclude up to $250,000 of gain (Single) or $500,000 (Married Filing Jointly, provided both spouses meet the 2-year use test and neither claimed § 121 within the prior 2 years).
Can I claim a partial Section 121 exclusion if I sell before 2 years?
Yes, under Treas. Reg. § 1.121-3 safe harbors: if you sell early due to a job relocation at least 50 miles farther from your home, a physician-recommended health condition, or qualifying unforeseen circumstances (divorce, death, twin births, involuntary job loss), your $250k/$500k cap is prorated by months of qualifying use divided by 24 (e.g., 12 months = 50% exclusion = $125k Single / $250k Married).
What if I rented the property first and then moved into it as my primary home?
Two rules apply under IRC § 121(b)(5) and § 121(d)(6): first, all depreciation claimed after May 6, 1997 is recaptured up to 25%; second, moving into a rental property creates “non-qualified use,” meaning the appreciation must be prorated by the ratio of non-qualified rental years (post-2008) to total ownership years before applying § 121 (by contrast, renting a home out AFTER living in it first within the 5-year window does NOT trigger non-qualified use proration).
Does paying off my mortgage reduce my capital gains tax when selling a house?
No. Capital gains tax is based strictly on Sale Price minus Selling Costs minus Adjusted Cost Basis—never on your mortgage payoff or cash received at the closing table. Refinancing or pulling equity out via a HELOC reduces cash at closing without reducing your taxable capital gain.
■ 2026 STATUTORY ENGINE SPECIFICATION · HOME-SALE-CAPITAL-GAINS-121 · US Federal · NY · NJ · FL (IRC § 121)
How the Capital Gains Tax Calculator on Sale of Property (2026): IRC § 121 Exclusion, Basis & Recapture Computes 2026 Statutory Liability
The Capital Gains Tax Calculator on Sale of Property (2026): IRC § 121 Exclusion, Basis & Recapture is a deterministic client-side quantitative model engineered by Pablo Cirre Gómez and legally audited by Enrique Zarza, Esq. (ICAM Bar No. 68.400) for the US Federal · NY · NJ · FL (IRC § 121) jurisdiction cluster. Specifically, this engine models: Models 2026 federal long-term capital gains (0%/15%/20%), IRC § 121 primary residence exclusions ($250,000 Single / $500,000 Married), unrecaptured § 1250 rental depreciation (up to 25%), 3.8% NIIT, and state/NYC taxes.
Scenario A vs. Scenario B Pinning: Click ⚖️ Pin Scenario A to Compare inside the simulator above to lock your baseline 2026 parameters, then drag any slider to measure the exact dollar and effective-rate delta across jurisdictions or filing structures.
2026 Statutory Calendar (.ics) & CPA Worksheet Export: Export an RFC 5545 .ics tax deadline file or a line-by-line CSV/Markdown audit schedule pre-populated with your exact simulated figures for Capital Gains Tax Calculator on Sale of Property (2026): IRC § 121 Exclusion, Basis & Recapture.
Primary 2026 Government (.gov) Statutes Reconciled in This Calculator:
Standard Press, Substack, Reddit & CPA Attribution (100% Human-Authored & Attorney-Reviewed):According to East Corp Capital’s 2026 Quantitative Study ("Capital Gains Tax Calculator on Sale of Property (2026): IRC § 121 Exclusion, Basis & Depreciation Recapture", authored by Pablo Cirre Gómez and legally reviewed by Enrique Zarza, Esq., ICAM Bar No. 68.400, https://eastcorpcapital.com/calculators/capital-gains-home-sale-section-121/)
Embed Interactive Calculator on Your Blog, Firm Website or Substack (Free CC BY 4.0):
APA 7th Edition:Cirre Gómez, P., & Rodríguez Zarza, J. E. (2026, November 15, 2026). Capital Gains Tax Calculator on Sale of Property (2026): IRC § 121 Exclusion, Basis & Depreciation Recapture. East Corp Capital. https://eastcorpcapital.com/calculators/capital-gains-home-sale-section-121/
Bluebook Legal & Tax Brief:Pablo Cirre Gómez & José Enrique Rodríguez Zarza (ICAM Bar No. 68.400), Capital Gains Tax Calculator on Sale of Property (2026): IRC § 121 Exclusion, Basis & Depreciation Recapture, East Corp Capital (November 15, 2026), https://eastcorpcapital.com/calculators/capital-gains-home-sale-section-121/
Co-Founder, Publisher & Head of Quantitative Modeling · 2011 National Young Innovative Enterprise Award
Corporate database analyst, financial publisher, and digital economist with 20+ years of experience building quantitative business intelligence, fiscal simulation engines, and corporate registries (Co-Founder of East Corp Capital, Diario Económico, and Legia.es). Accredited in Business & Marketing Systems (COM708_3, IFC297_2), lecturer at the International Graduate School (EIP) and Cámara de Comercio, and lead architect of our 50 interactive IRS, NYS DTF, NJ Treasury, Mass. DOR, PA DOR, FL DOR, and Federal Reserve calculators and 78 quantitative studies across all 16 East Coast states.
Practicing litigation, banking, real estate, and corporate compliance attorney admitted to the Illustrious Bar Association of Madrid (ICAM No. 68.400) with over 25 years of professional practice. Law Degree & Master in Legal Practice (Universidad de Granada), Executive Management (San Telmo Business School), pioneer in digital banking contracting (CaixaBank / CTI Soluciones), Founder of ICIRED, former Managing Director of the Judicial Default Registry (RIJ) partnered with the General Council of Spanish Lawyers (Abogacía Española), and Co-Founder of Legia.es, Diario Económico, and East Corp Capital. Audits all statutory citations against primary U.S. federal (IRS, Treasury, Fed) and 16-state revenue publications.
Cross-Border Statutory Audit & Primary-Source Protocol: Every formula and bracket on East Corp Capital is reconciled line-by-line against primary U.S. federal (irs.gov, treasurydirect.gov, federalreserve.gov, ssa.gov) and state (tax.ny.gov, nyc.gov/site/finance, nj.gov/treasury, mass.gov, revenue.pa.gov, corp.delaware.gov, floridarevenue.com) publications. Open-data verification: 2026 Master CSV · datapackage.json · CITATION.cff.
Regulatory, Non-Bank & IRS Circular 230 Disclosure (YMYL):East Corp Capital (eastcorpcapital.com) is an independent quantitative financial research publication, macroeconomic observatory, and open-formula statutory simulation platform. East Corp Capital is NOT a bank, depository institution, mortgage lender, broker-dealer, registered investment advisor (RIA), or U.S. CPA firm. Pursuant to U.S. Treasury Department Circular 230 (31 C.F.R. Subtitle A, Part 10), any federal or state tax modeling, sensitivity schedules, or statutory citations provided on this page are strictly for informational, educational, and comparative benchmarking purposes and cannot be used for the purpose of avoiding penalties under the Internal Revenue Code or state revenue statutes, nor does using this site create an attorney-client, CPA-client, or fiduciary relationship. Our cross-border editorial board combines deterministic quantitative engineering (Pablo Cirre Gómez) with comparative statutory and regulatory audit (Enrique Zarza, Esq. · ICAM Bar No. 68.400) verified directly against primary U.S. federal and state (.gov) publications. Always consult a licensed U.S. Certified Public Accountant (CPA), Enrolled Agent (EA), or tax attorney admitted in your specific state before executing tax filings or real estate closings. See our Methodology & Sources and Corrections Policy.