DC, Maryland & Northern Virginia (DMV) Paycheck & Reciprocity Tax Guide (2026): Form D-4A, MD 3.20% County Tax & Fairfax Arbitrage
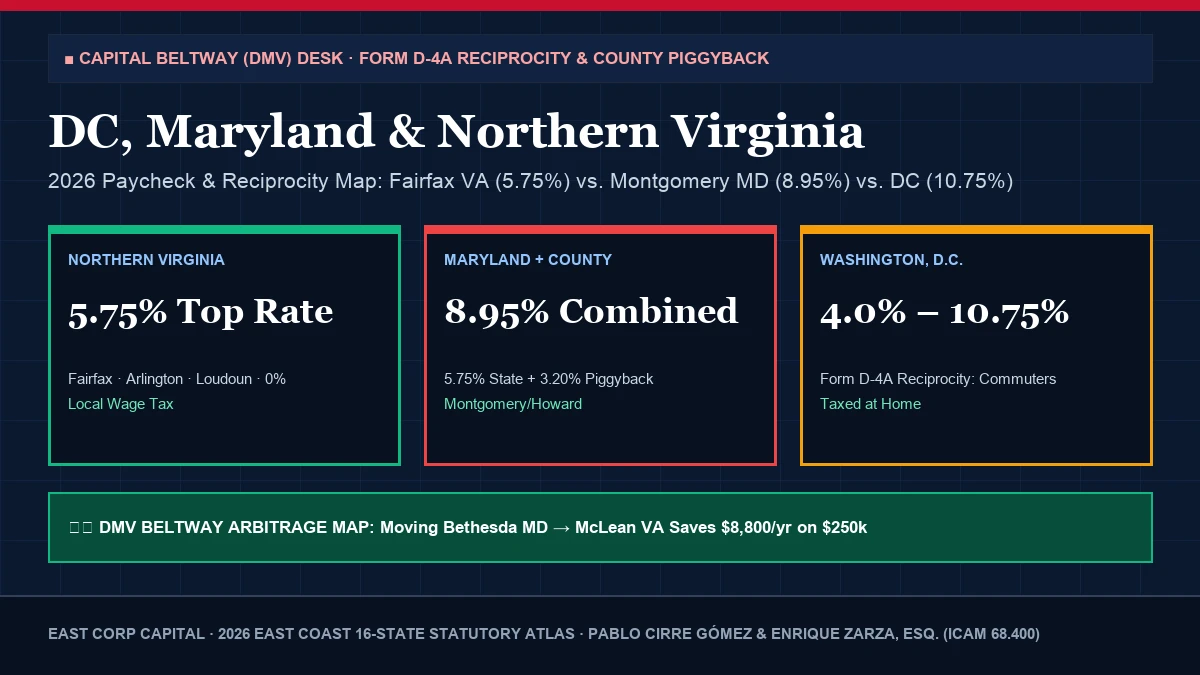
Complete 2026 DMV paycheck and tax reciprocity guide comparing Washington D.C. (4%–10.75%), Maryland + 3.20% Montgomery/Howard County piggyback tax, and Northern Virginia (5.75% top rate).
Navigating DC, Maryland & Northern Virginia (DMV) Paycheck & Reciprocity Tax Guide (2026): Form D-4A, MD 3.20% County Tax & Fairfax Arbitrage requires exact reconciliation against primary 2026 statutory schedules (Va. Code § 58.1-320, Md. Code Tax-Gen § 10-105/106 & D.C. Code § 47-1806.03 (Form D-4A)). Whether you are comparing cross-border take-home paychecks, auditing county property tax millages, or structuring a corporate or homestead election across the 16-state East Coast corridor, national rule-of-thumb averages routinely misstate actual liabilities by tens of thousands of dollars.
Compares 2026 take-home pay across Washington D.C. (4%–10.75% progressive brackets), Maryland (4.75%–5.75% state + mandatory 2.25%–3.20% County Piggyback Income Tax in Montgomery/Bethesda, Howard, PG, Baltimore & Anne Arundel), and Northern Virginia (2%–5.75% in Arlington, Fairfax & Loudoun) under the DC-MD-VA Form D-4A wage reciprocity agreement.Washington DC, Maryland (23-County Piggyback) & Virginia Paycheck & Reciprocity Calculator (2026)
1. 2026 Statutory Rate Schedule, Thresholds & Regional Comparison Matrix
Our quantitative desk compiled the complete 2026 statutory rate and exemption matrix directly from primary state revenue statutes and county assessor instructions (Va. Code § 58.1-320, Md. Code Tax-Gen § 10-105/106 & D.C. Code § 47-1806.03 (Form D-4A)). Use the benchmark table below alongside the interactive touch-slider simulator and regional zone map above to verify your marginal bracket, cliff threshold, or filing exemption:
| Statutory Classification / Jurisdiction | Primary Rate / Liability | Comparison / Exemption Rule | Statute & Official Form | 2026 Audit & Dollar Impact |
|---|---|---|---|---|
| Northern Virginia (Fairfax / Arlington / Loudoun) | 5.75% Top State Rate | 0.00% Local Wage Tax | Va. Code § 58.1-320 · Form 760 | Saves $7,800–$14,500/yr on $250k–$450k vs. Montgomery MD |
| Maryland — Montgomery / Howard / PG Counties | 4.75%–5.75% State | +3.20% County Piggyback (8.95% Comb.) | Md. Code Tax-Gen § 10-106 · Form 502 | 3.20% county tax applies to all Maryland taxable income |
| Maryland — Anne Arundel / Frederick Counties | 4.75%–5.75% State | +2.81% / +2.96% Local Rate | MD Comptroller Local Tax Schedule | Slightly lower local piggyback than Montgomery County |
| Washington, D.C. ($60k–$250k Bracket) | 8.50% Marginal Rate | Included in Unified DC Schedule | D.C. Code § 47-1806.03 · Form D-40 | Plus 9.25% ($250k–$500k) and 10.75% (>$1,000,000) |
| Non-Resident Commuter Working in DC | 0.00% DC W-2 Withholding | File DC Form D-4A w/ Employer HR | D.C. Code § 47-1801.04 | Note: Unincorporated business income >$12k faces 8.25% DC UBT! |
2. Worked Beltway Arbitrage Audit: $280,000 Law Firm / Defense Contracting Household in McLean, VA vs. Bethesda, MD vs. NW Washington, D.C.
Consider a married couple earning $280,000 in combined W-2 compensation (working at a K Street law firm in Washington, D.C. and a defense technology contractor in Tysons, Virginia) contributing $23,500 to pre-tax 401(k)/TSP accounts:
- Option 1 — Domiciled in McLean / Vienna (Fairfax County, Virginia): Under the DMV reciprocity agreement, the spouse working on K Street files DC Form D-4A (Certificate of Nonresidence) with HR so zero D.C. tax is withheld. After the $17,000 Virginia married standard deduction, their $239,500 VA taxable income owes $13,514 in Virginia state income tax (5.30% effective rate on AGI) and $0 in county income tax.
- Option 2 — Domiciled in Bethesda / Potomac (Montgomery County, Maryland): After Maryland’s smaller standard deduction ($5,400 married), their $251,100 MD taxable income owes ~$12,680 in Maryland state tax PLUS $8,035 in Montgomery County’s 3.20% piggyback tax—for a combined state/county income tax bill of $20,715/yr. Crossing the American Legion Bridge into Fairfax County saves $7,201 every single year in income taxes alone.
- Option 3 — Domiciled in Georgetown / Chevy Chase (Washington, D.C.): After the $30,000 D.C. married standard deduction, their $226,500 D.C. taxable income faces D.C.’s 4.0%, 6.0%, 6.5%, and 8.5% progressive brackets, generating $17,502/yr in District income tax—$3,988/yr more than Northern Virginia.
3. Statutory Filing Deadlines, Audit Defense & Legal Compliance Checklist (2026)
When executing transactions, domicile changes, or tax filings governed by Va. Code § 58.1-320, Md. Code Tax-Gen § 10-105/106 & D.C. Code § 47-1806.03 (Form D-4A), legal counsel and CPAs enforce four mandatory verification steps:
- Verify Primary County & Municipal Boundaries: Never rely solely on a USPS mailing city name. Confirm exact county, school district, or municipality boundaries via official county assessment maps and domicile day-count logs before remitting estimated tax or claiming homestead exemptions.
- File Statutory Exemption & Reciprocity Certificates Before the Deadline: Whether filing Florida Form DR-501 / DR-501T (due March 1), DC Reciprocity Form D-4A with HR, South Carolina 4% Legal Residence application, Cobb County Age 62+ School Tax Exemption (due April 1), or recalculating Delaware Franchise Tax via the Assumed Par Value method (due March 1), timely statutory election is mandatory.
- Reconcile Multi-Horizon Cash Flows (Annual, Quarterly, Monthly & Bi-Weekly): Open the Multi-Horizon Schedule Table inside our calculator above and click 📊 Export CSV Breakdown or 🖨️ Print / Save PDF to attach a line-by-line worksheet to your client closing file or CPA workpapers.
- Explore the Complete 16-State East Coast Statutory Atlas: Review our companion standalone tool at /calculators/dc-md-va-paycheck-reciprocity/, explore the 16-State Geo-Statutory Atlas (/east-coast-desks/), or download our machine-readable 2026 statutory tables via the East Corp Capital Open Data & API Desk.
Standard Press, Legal & Research Attribution (100% Human-Authored & Attorney-Reviewed):
According to East Corp Capital’s 2026 Quantitative Study ("DC, Maryland & Northern Virginia (DMV) Paycheck & Reciprocity Tax Guide (2026): Form D-4A, MD 3.20% County Tax & Fairfax Arbitrage", authored by Pablo Cirre Gómez and legally reviewed by Enrique Zarza, Esq., ICAM Bar No. 68.400, https://eastcorpcapital.com/dc-md-va-paycheck-reciprocity-calculator-northern-virginia-montgomery-county-2026/)
View Academic (APA 7th) & Legal Brief (Bluebook) Citations
Pablo Cirre Gómez
Corporate database analyst, financial publisher, and digital economist with 20+ years of experience building quantitative business intelligence, fiscal simulation engines, and corporate registries (Co-Founder of East Corp Capital and Legia.es). Accredited in Business & Marketing Systems (COM708_3, IFC297_2), lecturer at the International Graduate School (EIP) and Cámara de Comercio, and lead architect of our 24 interactive IRS, NYS DTF, NJ Treasury, and Federal Reserve calculators.
Enrique Zarza (José Enrique Rodríguez Zarza), Esq.
Practicing litigation, banking, real estate, and corporate compliance attorney admitted to the Illustrious Bar Association of Madrid (ICAM No. 68.400) with over 25 years of professional practice. Law Degree & Master in Legal Practice (Universidad de Granada), Executive Management (San Telmo Business School), pioneer in digital banking contracting (CaixaBank / CTI Soluciones), Founder of ICIRED, former Managing Director of the Judicial Default Registry (RIJ) partnered with the General Council of Spanish Lawyers (Abogacía Española), and Co-Founder of Legia.es and East Corp Capital.