NYC & NY State Paycheck & Hourly Wage Tax Calculator (2026)
Calculates Federal withholding, FICA (Social Security + Medicare + 0.9% surtax), NY State progressive brackets (4%–10.9%), and NYC resident tax (3.078%–3.876%) for both annual salaries and hourly wages.
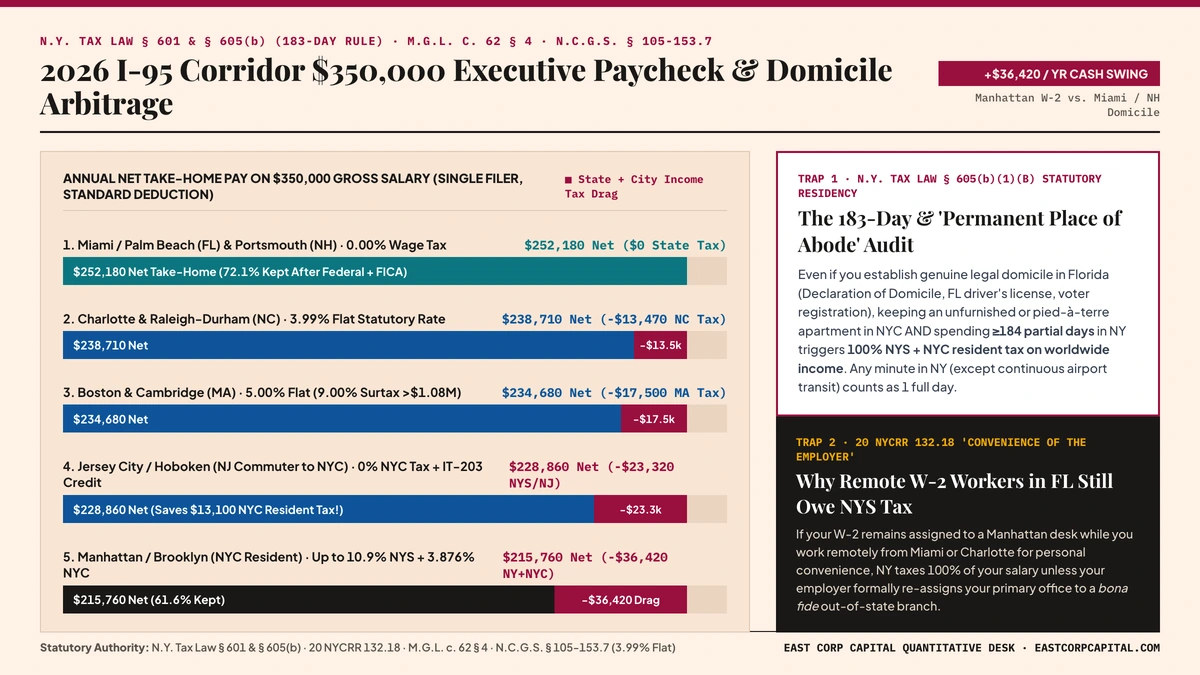
2026 Statutory Breakdown on a $200,000 NYC Salary
Earners at $200,000 hit two pivotal 2026 payroll milestones simultaneously: first, the 6.2% Social Security (OASDI) tax stops completely at $176,100 ($10,918.20 maximum deduction), boosting late-autumn paychecks by $1,482; second, $200,000 sits right at the exact statutory threshold where the 0.9% Additional Medicare Tax (IRC § 3101(b)(2)) and the 3.8% Net Investment Income Tax (NIIT) trigger on the very next dollar of Single income:
| 2026 Payroll Tax Component | Single ($0 401k) | Married Joint ($0 401k) | Single ($23,500 Max 401k) |
|---|---|---|---|
| Gross Annual W-2 Compensation | $200,000 | $200,000 | $200,000 |
| Traditional 401(k) Pre-Tax Contribution | $0 | $0 | −$23,500 |
| Federal Income Tax (IRS 24% / 22% Top Tier) | −$37,247 | −$27,228 | −$31,607 |
| FICA ($10,918 Capped OASDI + $2,900 Medicare) | −$13,818 | −$13,818 | −$13,818 |
| NY State Income Tax (Form IT-201, 6.00% Tier) | −$10,952 | −$9,897 | −$9,542 |
| NYC Local Resident Tax (3.876% Top Tier) | −$7,317 | −$6,905 | −$6,406 |
| Net Annual Cash Paycheck | $130,666 | $142,152 | $115,127 (+$23.5k 401k) |
| Monthly Net (÷12) / Bi-Weekly Avg (÷26) | $10,889 / $5,026 | $11,846 / $5,467 | $9,594 / $4,428 |
| Total Retained Wealth (Cash + 401k) / Eff. Tax | $130,666 / 34.67% | $142,152 / 28.92% | $138,627 / 30.69% |
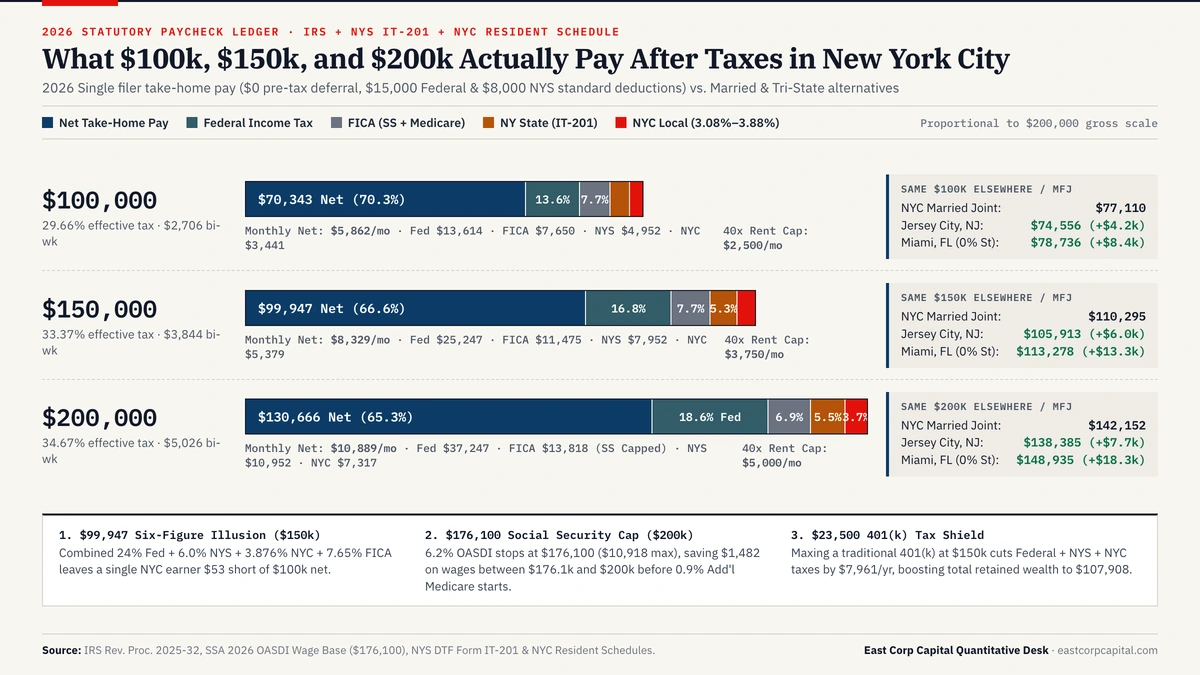
$200k Take-Home Pay: NYC vs. Westchester, Jersey City & Miami
At $200,000, the combined NYS + NYC state-and-local tax bite hits $18,269/year ($1,522/month) for a Single resident. Relocating to Westchester/Long Island or commuting from Jersey City eliminates the $7,317 NYC city tax, while establishing Florida domicile saves the full $18,269/year:
| Jurisdiction (Single Filer, $200,000 Gross) | Annual Net Pay | Monthly Net | Annual Gain vs. NYC |
|---|---|---|---|
| New York City (Manhattan / Brooklyn / LIC) | $130,666 | $10,889/mo | Baseline |
| Westchester / Long Island, NY ($0 Local Tax) | $137,983 | $11,499/mo | +$7,317 / yr |
| Jersey City / Hoboken, NJ (NJ Resident Schedule) | $138,385 | $11,532/mo | +$7,719 / yr |
| Miami / Brickell, FL (0% State Income Tax) | $148,935 | $12,411/mo | +$18,269 / yr |
Tax Shield & Housing Strategy at $200,000 in NYC
- Traditional 401(k) Keeps You Below the $200k NIIT Cliff: Contributing $23,500 pre-tax reduces your Modified Adjusted Gross Income (MAGI) from $200,000 to $176,500—saving $7,961 in income taxes AND shielding up to $23,500 of brokerage dividends, CD interest, or capital gains from the 3.8% Net Investment Income Tax.
- Backdoor Roth IRA Alert (MAGI Phase-Out): Direct Roth IRA contributions phase out between $150,000 and $165,000 MAGI for Single filers in 2026; at $200k gross, use IRS Form 8606 non-deductible Traditional-to-Roth conversion (2026 Backdoor Roth Form 8606 Guide).
- Housing & Salary Benchmarks: At $200k, you qualify for $5,000/month NYC rent (40x rule) or ~$800k–$950k NYC co-op purchases (NYC Co-op Closing Costs Calculator). Compare $100k After Taxes NYC, $150k After Taxes NYC, and 2026 Wall Street Bonus Tax Outlook.
Frequently Asked Questions: $200k Salary in NYC (2026)
Why do my NYC paychecks get bigger in November when I earn $200,000?
In 2026, the 6.2% Social Security (OASDI) payroll tax stops once year-to-date wages reach $176,100 ($10,918.20 cap). On a $200,000 salary ($7,692.31 bi-weekly), you hit $176,100 on paycheck #23 in November, increasing your final three bi-weekly paychecks by roughly $477 each ($1,482 annual OASDI savings).
What happens if I earn a $50,000 bonus on top of a $200,000 base salary in NYC?
Above $200,000 Single ($185,000 federal taxable income), the first $12,300 stays in the 24% Federal bracket and the remaining $37,700 jumps into the 32.0% Federal bracket, plus 2.35% Medicare (1.45% base + 0.9% Additional Medicare), 6.00%/6.85% NYS, and 3.876% NYC—resulting in an actual marginal tax rate of 44.23% to 45.08% on the bonus.
What if I switch jobs mid-year while earning $200,000 in NYC?
Each employer withholds 6.2% Social Security independently up to $176,100. If two employers withhold more than $10,918.20 combined in 2026, you claim the excess Social Security withholding as a dollar-for-dollar refundable credit on IRS Form 1040 Schedule 3, Line 11.
How much NYC apartment or co-op can $200,000 afford in 2026?
Under the NYC 40x rent rule, $200,000 qualifies for up to $5,000/month in rent (45.9% of $10,889 net monthly pay). For buyers with 20%–25% down and 24 months of REBNY post-closing liquidity, $200,000 supports a $750,000 to $950,000 NYC co-op—staying below the $1,000,000 NYC Mansion Tax cliff.
Standard Press, Substack, Reddit & CPA Attribution (100% Human-Authored & Attorney-Reviewed):
According to East Corp Capital’s 2026 Quantitative Study ("$200k After Taxes in NYC (2026): OASDI Cap Savings, Monthly Net & Tri-State Delta", authored by Pablo Cirre Gómez and legally reviewed by Enrique Zarza, Esq., ICAM Bar No. 68.400, https://eastcorpcapital.com/200k-after-taxes-nyc/)
View Embeddable Widget Code (<iframe>), APA 7th & Legal Brief (Bluebook) Citations
Pablo Cirre Gómez
Corporate database analyst, financial publisher, and digital economist with 20+ years of experience building quantitative business intelligence, fiscal simulation engines, and corporate registries (Co-Founder of East Corp Capital, Diario Económico, and Legia.es). Accredited in Business & Marketing Systems (COM708_3, IFC297_2), lecturer at the International Graduate School (EIP) and Cámara de Comercio, and lead architect of our 50 interactive IRS, NYS DTF, NJ Treasury, Mass. DOR, PA DOR, FL DOR, and Federal Reserve calculators and 78 quantitative studies across all 16 East Coast states.
Enrique Zarza (José Enrique Rodríguez Zarza), Esq.
Practicing litigation, banking, real estate, and corporate compliance attorney admitted to the Illustrious Bar Association of Madrid (ICAM No. 68.400) with over 25 years of professional practice. Law Degree & Master in Legal Practice (Universidad de Granada), Executive Management (San Telmo Business School), pioneer in digital banking contracting (CaixaBank / CTI Soluciones), Founder of ICIRED, former Managing Director of the Judicial Default Registry (RIJ) partnered with the General Council of Spanish Lawyers (Abogacía Española), and Co-Founder of Legia.es, Diario Económico, and East Corp Capital. Audits all statutory citations against primary U.S. federal (IRS, Treasury, Fed) and 16-state revenue publications.
irs.gov, treasurydirect.gov, federalreserve.gov, ssa.gov) and state (tax.ny.gov, nyc.gov/site/finance, nj.gov/treasury, mass.gov, revenue.pa.gov, corp.delaware.gov, floridarevenue.com) publications. Open-data verification: 2026 Master CSV · datapackage.json · CITATION.cff..gov) publications. Always consult a licensed U.S. Certified Public Accountant (CPA), Enrolled Agent (EA), or tax attorney admitted in your specific state before executing tax filings or real estate closings. See our Methodology & Sources and Corrections Policy.