NYC & NY State Paycheck & Hourly Wage Tax Calculator (2026)
Calculates Federal withholding, FICA (Social Security + Medicare + 0.9% surtax), NY State progressive brackets (4%–10.9%), and NYC resident tax (3.078%–3.876%) for both annual salaries and hourly wages.
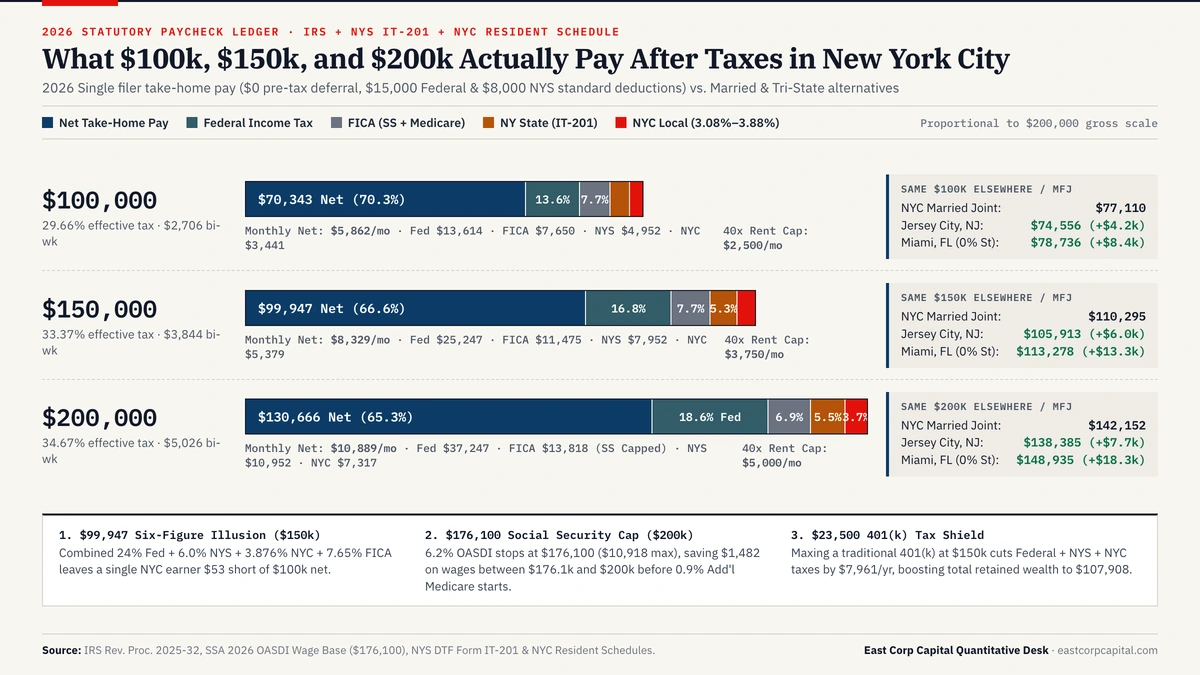
2026 Tax Ledger: Where $50,053 Goes on a $150,000 NYC Salary
At $150,000 gross, a Single NYC taxpayer crosses deep into the 24.0% Federal bracket (taxable income above $103,350), the 6.00% NY State bracket (above $80,650), and the top 3.876% NYC resident bracket, while still paying the full 7.65% FICA rate on every dollar (since $150k sits below the $176,100 Social Security cap). Every marginal raise or cash bonus at $150k faces a 41.53% combined marginal tax rate:
| 2026 Payroll Tax Component | Single ($0 401k) | Married Joint ($0 401k) | Single ($23,500 Max 401k) |
|---|---|---|---|
| Gross Annual W-2 Compensation | $150,000 | $150,000 | $150,000 |
| Traditional 401(k) Pre-Tax Contribution | $0 | $0 | −$23,500 |
| Federal Income Tax ($15k / $30k Std. Ded.) | −$25,247 | −$16,228 | −$19,607 |
| FICA ($9,300 Social Security + $2,175 Medicare) | −$11,475 | −$11,475 | −$11,475 |
| NY State Income Tax (Form IT-201) | −$7,952 | −$7,035 | −$6,542 |
| NYC Local Resident Income Tax (Top 3.876%) | −$5,379 | −$4,967 | −$4,468 |
| Net Annual Cash Paycheck | $99,947 | $110,295 | $84,408 (+$23.5k 401k) |
| Monthly Net (÷12) / Bi-Weekly Net (÷26) | $8,329 / $3,844 | $9,191 / $4,242 | $7,034 / $3,246 |
| Total Retained Wealth (Cash + 401k) / Eff. Tax | $99,947 / 33.37% | $110,295 / 26.47% | $107,908 / 28.06% |
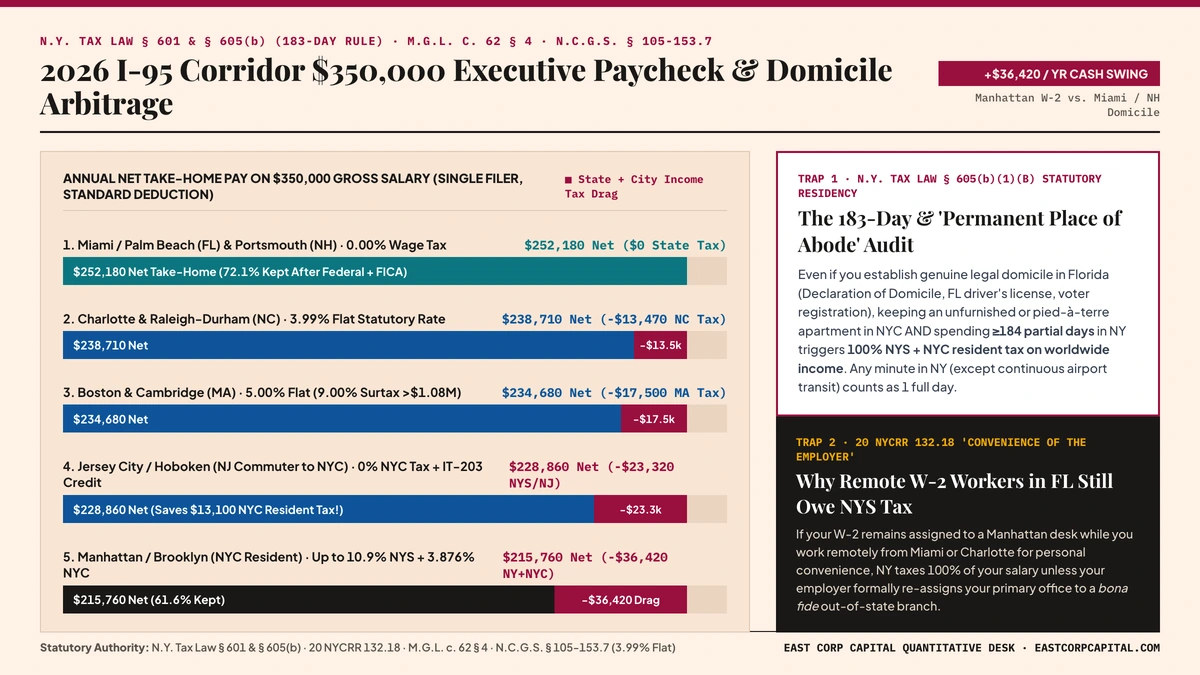
$150k in NYC vs. Hoboken/Jersey City, Westchester & Florida
Moving across the Hudson to Jersey City/Hoboken (as a remote/NJ-sourced worker) or to Long Island/Westchester eliminates the $5,379 NYC resident tax, while relocating to a 0%-income-tax state like Florida adds +$13,331/year (+$1,111/month) in net take-home pay:
| Jurisdiction (Single Filer, $150,000 Gross) | Annual Net Pay | Monthly Net | Annual Savings vs. NYC |
|---|---|---|---|
| New York City (5 Boroughs) | $99,947 | $8,329/mo | Baseline |
| Westchester / Nassau / Suffolk, NY ($0 Local) | $105,326 | $8,777/mo | +$5,379 / yr |
| Jersey City / Hoboken, NJ (NJ Schedule) | $105,913 | $8,826/mo | +$5,966 / yr |
| Miami / Palm Beach, FL (0% State Tax) | $113,278 | $9,440/mo | +$13,331 / yr |
3 High-Impact Moves for $150k NYC Earners
- Maxing Your $23,500 401(k) Saves $7,961 Instantly: Deferring $23,500 drops your cash paycheck by only $15,539 (from $99,947 to $84,408) because IRS + NYS + NYC absorb 33.88% ($7,961) of the contribution—lifting your total retained net worth from $99,947 to $107,908/year.
- 40x Rent Ceiling ($3,750/month): At $150,000 gross, NYC landlords approve leases up to $3,750/month ($150,000 ÷ 40), which unlocks solo Manhattan studios or Brooklyn/LIC 1-bedrooms at 45% of net cash pay.
- Compare Adjacent Salary & Bonus Tiers: Model $100k After Taxes in NYC ($70,343 net), $200k After Taxes in NYC ($130,666 net), NYC Wall Street Bonus Withholding, or NY-to-Florida 183-Day Relocation Savings.
Frequently Asked Questions: $150k After Taxes in NYC (2026)
What gross salary do you need in NYC in 2026 to take home $100,000 after taxes?
A Single NYC resident needs exactly $150,089 in gross W-2 salary (with $0 pre-tax deductions) to clear $100,000 in net cash take-home pay in 2026, because a $150,000 salary nets $99,947 after $50,053 in Federal, FICA, NYS, and NYC taxes.
How much is $150,000 bi-weekly and monthly after taxes in Manhattan or Brooklyn?
For a Single filer with $0 pre-tax deductions, $150,000 produces $8,329 per month, $4,164 semi-monthly (24 pay periods), or $3,844 bi-weekly (26 pay periods). Contributing the $23,500 401(k) maximum adjusts bi-weekly cash take-home to $3,246 while adding $904 bi-weekly into tax-deferred retirement assets.
Does living in Jersey City and working in Manhattan save taxes on $150,000?
Yes. Moving from Manhattan/Brooklyn to Jersey City or Hoboken while commuting to a NY office eliminates the entire $5,379 NYC local resident tax. You still file NY non-resident Form IT-203 ($7,952 tax) and claim a dollar-for-dollar credit on NJ Schedule NJ-COJ so you owe $0 additional NJ income tax on W-2 wages.
Can I buy a NYC co-op on a $150,000 salary?
Under standard REBNY co-op board rules (28% housing debt-to-income cap = $3,500/month combined mortgage + maintenance), a $150,000 buyer with 20%–25% down plus 24 months of post-closing liquidity typically qualifies for NYC co-ops priced between $525,000 and $675,000.
Standard Press, Substack, Reddit & CPA Attribution (100% Human-Authored & Attorney-Reviewed):
According to East Corp Capital’s 2026 Quantitative Study ("$150k After Taxes in NYC (2026): Why Six Figures Clears $99,947 & Monthly Net", authored by Pablo Cirre Gómez and legally reviewed by Enrique Zarza, Esq., ICAM Bar No. 68.400, https://eastcorpcapital.com/150k-after-taxes-nyc/)
View Embeddable Widget Code (<iframe>), APA 7th & Legal Brief (Bluebook) Citations
Pablo Cirre Gómez
Corporate database analyst, financial publisher, and digital economist with 20+ years of experience building quantitative business intelligence, fiscal simulation engines, and corporate registries (Co-Founder of East Corp Capital, Diario Económico, and Legia.es). Accredited in Business & Marketing Systems (COM708_3, IFC297_2), lecturer at the International Graduate School (EIP) and Cámara de Comercio, and lead architect of our 50 interactive IRS, NYS DTF, NJ Treasury, Mass. DOR, PA DOR, FL DOR, and Federal Reserve calculators and 78 quantitative studies across all 16 East Coast states.
Enrique Zarza (José Enrique Rodríguez Zarza), Esq.
Practicing litigation, banking, real estate, and corporate compliance attorney admitted to the Illustrious Bar Association of Madrid (ICAM No. 68.400) with over 25 years of professional practice. Law Degree & Master in Legal Practice (Universidad de Granada), Executive Management (San Telmo Business School), pioneer in digital banking contracting (CaixaBank / CTI Soluciones), Founder of ICIRED, former Managing Director of the Judicial Default Registry (RIJ) partnered with the General Council of Spanish Lawyers (Abogacía Española), and Co-Founder of Legia.es, Diario Económico, and East Corp Capital. Audits all statutory citations against primary U.S. federal (IRS, Treasury, Fed) and 16-state revenue publications.
irs.gov, treasurydirect.gov, federalreserve.gov, ssa.gov) and state (tax.ny.gov, nyc.gov/site/finance, nj.gov/treasury, mass.gov, revenue.pa.gov, corp.delaware.gov, floridarevenue.com) publications. Open-data verification: 2026 Master CSV · datapackage.json · CITATION.cff..gov) publications. Always consult a licensed U.S. Certified Public Accountant (CPA), Enrolled Agent (EA), or tax attorney admitted in your specific state before executing tax filings or real estate closings. See our Methodology & Sources and Corrections Policy.