South Carolina 4% Primary Residence vs. 6% Second-Home Property Tax Guide (2026): Charleston, Kiawah, Hilton Head & Greenville
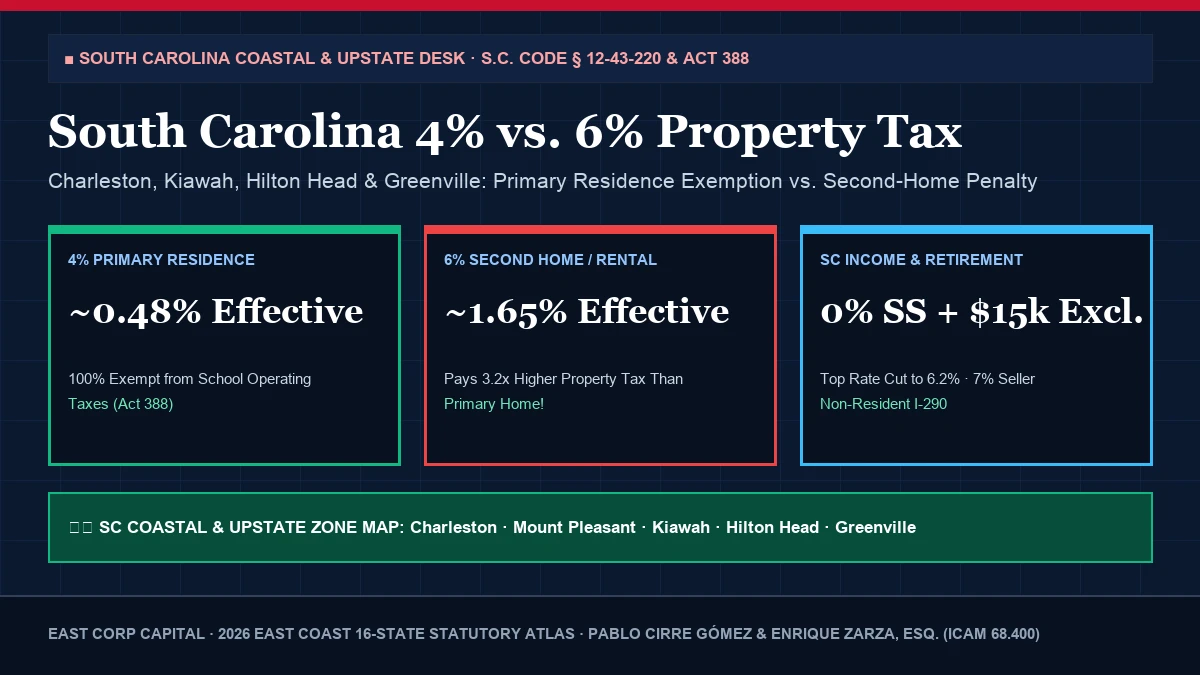
Complete 2026 South Carolina property tax guide explaining why a 4% Legal Residence pays 65%–70% less tax than a 6% Second Home under Act 388 in Charleston, Kiawah Island, Hilton Head, and Greenville.
Navigating South Carolina 4% Primary Residence vs. 6% Second-Home Property Tax Guide (2026): Charleston, Kiawah, Hilton Head & Greenville requires exact reconciliation against primary 2026 statutory schedules (S.C. Code § 12-43-220(c) (4% Ratio), § 12-37-220(B)(47) (Act 388 School Exemption) & § 12-8-580 (7% Non-Res Withholding)). Whether you are comparing cross-border take-home paychecks, auditing county property tax millages, or structuring a corporate or homestead election across the 16-state East Coast corridor, national rule-of-thumb averages routinely misstate actual liabilities by tens of thousands of dollars.
Quantifies the dramatic South Carolina property tax gap between a 4% Legal Residence (100% exempt from school operating taxes under Act 388) and a 6% Non-Owner-Occupied Second Home or Rental across Charleston, Mount Pleasant, Kiawah Island, Hilton Head (Beaufort), Greenville, and Myrtle Beach, plus SC income tax.South Carolina 4% Primary Residence vs. 6% Second-Home Property Tax & Paycheck Calculator (2026)
1. 2026 Statutory Rate Schedule, Thresholds & Regional Comparison Matrix
Our quantitative desk compiled the complete 2026 statutory rate and exemption matrix directly from primary state revenue statutes and county assessor instructions (S.C. Code § 12-43-220(c) (4% Ratio), § 12-37-220(B)(47) (Act 388 School Exemption) & § 12-8-580 (7% Non-Res Withholding)). Use the benchmark table below alongside the interactive touch-slider simulator and regional zone map above to verify your marginal bracket, cliff threshold, or filing exemption:
| Statutory Classification / Jurisdiction | Primary Rate / Liability | Comparison / Exemption Rule | Statute & Official Form | 2026 Audit & Dollar Impact |
|---|---|---|---|---|
| 4% Primary Legal Residence (Owner-Occupied) | ~0.45%–0.55% Effective Rate | 100% Exempt from School Operating Tax | S.C. Code § 12-43-220(c) & Act 388 | $1,200,000 Charleston home owes ~$5,400/yr! |
| 6% Second Home / Vacation / LLC / Rental | ~1.55%–1.85% Effective Rate | Pays Full School Operating Millage | S.C. Code § 12-43-220(e) | Same $1,200,000 home owes ~$19,080/yr (+$13,680 Penalty!) |
| Age 65+ SC Homestead Exemption | First $50,000 FMV 100% Exempt | After 1 Year of SC Residency | S.C. Code § 12-37-250 | Applies on top of the 4% ratio & Act 388 exemption |
| Non-Resident Seller Closing Withholding | 7.00% of Net Recognized Gain | 5.00% if Seller is a Corporation | S.C. Code § 12-8-580 · Form I-290 | Remitted by closing attorney to SC DOR at settlement |
2. Worked Coastal Audit: $1,250,000 Home on Kiawah Island / Mount Pleasant (Charleston County) or Hilton Head (Beaufort County)
Examine a $1,250,000 coastal home in Charleston County, South Carolina where total combined county, municipal, and school millage is 265 mills (0.265) and school operating taxes represent 58% of the millage (153.7 mills):
- Scenario A — Purchased as a 6% Vacation Home by a New York / New Jersey Resident ($19,875/yr): At the 6% non-resident ratio, the taxable assessed value is $75,000 ($1,250,000 × 6%). Multiplied by the full 0.265 millage rate, the annual property tax bill is $19,875/yr (1.59% effective rate).
- Scenario B — Converted to a 4% Primary Legal Residence Upon Domiciling in SC ($5,565/yr): Once the owners change their domicile to South Carolina and qualify for the 4% Legal Residence certificate, the assessed value drops to $50,000 ($1,250,000 × 4%) AND the 153.7-mill school operating tax is 100% wiped out under Act 388 (leaving only 111.3 non-school mills). Their annual property tax plummets from $19,875 to $5,565/yr—an instant $14,310/yr property tax reduction (72% cut)!
3. Statutory Filing Deadlines, Audit Defense & Legal Compliance Checklist (2026)
When executing transactions, domicile changes, or tax filings governed by S.C. Code § 12-43-220(c) (4% Ratio), § 12-37-220(B)(47) (Act 388 School Exemption) & § 12-8-580 (7% Non-Res Withholding), legal counsel and CPAs enforce four mandatory verification steps:
- Verify Primary County & Municipal Boundaries: Never rely solely on a USPS mailing city name. Confirm exact county, school district, or municipality boundaries via official county assessment maps and domicile day-count logs before remitting estimated tax or claiming homestead exemptions.
- File Statutory Exemption & Reciprocity Certificates Before the Deadline: Whether filing Florida Form DR-501 / DR-501T (due March 1), DC Reciprocity Form D-4A with HR, South Carolina 4% Legal Residence application, Cobb County Age 62+ School Tax Exemption (due April 1), or recalculating Delaware Franchise Tax via the Assumed Par Value method (due March 1), timely statutory election is mandatory.
- Reconcile Multi-Horizon Cash Flows (Annual, Quarterly, Monthly & Bi-Weekly): Open the Multi-Horizon Schedule Table inside our calculator above and click 📊 Export CSV Breakdown or 🖨️ Print / Save PDF to attach a line-by-line worksheet to your client closing file or CPA workpapers.
- Explore the Complete 16-State East Coast Statutory Atlas: Review our companion standalone tool at /calculators/south-carolina-property-paycheck-tax/, explore the 16-State Geo-Statutory Atlas (/east-coast-desks/), or download our machine-readable 2026 statutory tables via the East Corp Capital Open Data & API Desk.
Standard Press, Legal & Research Attribution (100% Human-Authored & Attorney-Reviewed):
According to East Corp Capital’s 2026 Quantitative Study ("South Carolina 4% Primary Residence vs. 6% Second-Home Property Tax Guide (2026): Charleston, Kiawah, Hilton Head & Greenville", authored by Pablo Cirre Gómez and legally reviewed by Enrique Zarza, Esq., ICAM Bar No. 68.400, https://eastcorpcapital.com/south-carolina-4-percent-vs-6-percent-property-tax-ratio-charleston-hilton-head-2026/)
View Academic (APA 7th) & Legal Brief (Bluebook) Citations
Pablo Cirre Gómez
Corporate database analyst, financial publisher, and digital economist with 20+ years of experience building quantitative business intelligence, fiscal simulation engines, and corporate registries (Co-Founder of East Corp Capital and Legia.es). Accredited in Business & Marketing Systems (COM708_3, IFC297_2), lecturer at the International Graduate School (EIP) and Cámara de Comercio, and lead architect of our 24 interactive IRS, NYS DTF, NJ Treasury, and Federal Reserve calculators.
Enrique Zarza (José Enrique Rodríguez Zarza), Esq.
Practicing litigation, banking, real estate, and corporate compliance attorney admitted to the Illustrious Bar Association of Madrid (ICAM No. 68.400) with over 25 years of professional practice. Law Degree & Master in Legal Practice (Universidad de Granada), Executive Management (San Telmo Business School), pioneer in digital banking contracting (CaixaBank / CTI Soluciones), Founder of ICIRED, former Managing Director of the Judicial Default Registry (RIJ) partnered with the General Council of Spanish Lawyers (Abogacía Española), and Co-Founder of Legia.es and East Corp Capital.