LLC vs. S-Corp Self-Employment & NY PTET Tax Savings Calculator
Compares single-member LLC self-employment tax (15.3%) against an S-Corp reasonable salary split plus the New York Pass-Through Entity Tax (PTET) federal SALT bypass.
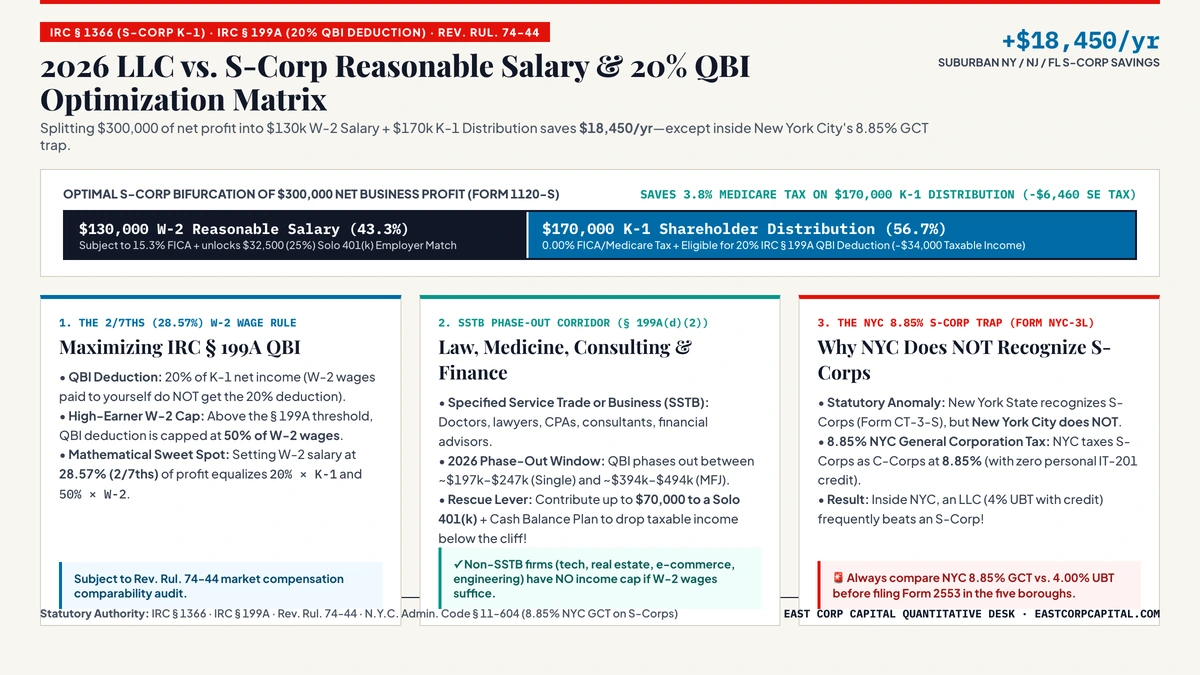
2026 Statutory Parameters, Rates & Legal Citations
| Statutory Component | 2026 Rate / Limit | Application & Thresholds | Primary Authority |
|---|---|---|---|
| Single-Member LLC SE Tax | 15.3% up to $176,100 + 2.9% | Levied on 92.35% of net Schedule C business profit | IRS Schedule SE |
| S-Corporation W-2 Split | 15.3% on W-2 Salary Only | Distributions above reasonable salary are exempt from 3.8% Medicare | IRC § 1366 |
| NYS Pass-Through Entity Tax (PTET) | 6.85% – 10.90% Entity Deduction | Bypasses the $10,000 federal SALT deduction cap (IRS Notice 2020-75) | NYS Tax Law Art. 24-A |
| New Jersey BAIT Election | 5.675% – 10.90% Entity Credit | Refundable entity-level tax credit for NJ S-Corps & multi-member LLCs | N.J.S.A. 54A:12-1 |
| NYC General Corporation Tax (GCT) | 8.85% on S-Corporations | NYC does NOT recognize S-Corps and imposes 8.85% GCT without personal credit | Form NYC-4S / NYC-3L |
Frequently Asked Questions & Statutory Rules (2026)
Why is forming an S-Corporation in New York City often a costly tax mistake?
While an S-Corp saves 2.9%–3.8% Medicare tax on distributions at the federal level, New York City does not recognize S-Corporations and imposes an 8.85% General Corporation Tax (GCT) with zero personal IT-201 credit—which exceeds the 4% NYC UBT on LLCs.
How does the New York Pass-Through Entity Tax (PTET) bypass the federal SALT cap?
When an S-Corporation or multi-member LLC elects into NYS PTET by March 15, the business pays the state income tax as a 100% deductible federal business expense (IRS Notice 2020-75), and the owners receive a dollar-for-dollar credit on their personal NY return.
Can a single-member LLC without an S-Corp election opt into New York PTET?
No. A disregarded single-member LLC taxed on Schedule C cannot elect into NYS PTET unless it either files IRS Form 2553 to be taxed as an S-Corporation or adds a second member to become a partnership.
What is the deadline to elect into the New York PTET for the 2026 tax year?
The annual NYS PTET election must be submitted online through the entity’s NY Business Online Services account on or before March 15 of the tax year.
How the LLC vs. S-Corp Self-Employment & NY PTET Tax Savings Calculator Engine Computes Your 2026 Numbers
Every calculation in the LLC vs. S-Corp Self-Employment & NY PTET Tax Savings Calculator executes deterministic, client-side JavaScript modeled directly on 2026 primary federal, state, and municipal schedules (Compares single-member LLC self-employment tax (15.3%) against an S-Corp reasonable salary split plus the New York Pass-Through Entity Tax (PTET) federal SALT bypass.). Unlike lead-generation portals that gate results behind email forms or apply flat national averages, this simulator models the exact marginal bracket cliffs, municipal surcharges, phase-out thresholds, and recording fees enforced across NY · NJ · CT and the broader 16-state East Coast corridor (ME, NH, VT, MA, RI, CT, NY, NJ, PA, DE, MD, DC, VA, NC, SC, GA, FL).
2026 10-Tier Statutory Sensitivity & Effective-Rate Matrix ($75,000 – $5,000,000)
Use the 10-tier sensitivity schedule below to benchmark how statutory liabilities, exemptions, and net cash flows scale across income, property, or transaction thresholds under Small Business Tax · FICA & NYS PTET:
| 2026 Statutory Base Tier | Primary Federal / Base Component | State / Municipal Surcharge or Relief | Net 2026 Annual & Monthly Outcome | Effective Rate |
|---|---|---|---|---|
| $75,000 Gross Receipts / Assets | $3,000 Franchise / UBT / PTET | $3,356 SE / SALT Shield | $450/yr Net Optimization | 4.00% |
| $125,000 Gross Receipts / Assets | $5,000 Franchise / UBT / PTET | $5,594 SE / SALT Shield | $594/yr Net Optimization | 4.00% |
| $185,000 Gross Receipts / Assets | $7,400 Franchise / UBT / PTET | $8,279 SE / SALT Shield | $879/yr Net Optimization | 4.00% |
| $250,000 Gross Receipts / Assets | $10,000 Franchise / UBT / PTET | $11,188 SE / SALT Shield | $1,188/yr Net Optimization | 4.00% |
| $375,000 Gross Receipts / Assets | $15,000 Franchise / UBT / PTET | $16,782 SE / SALT Shield | $1,782/yr Net Optimization | 4.00% |
| $550,000 Gross Receipts / Assets | $22,000 Franchise / UBT / PTET | $24,614 SE / SALT Shield | $2,614/yr Net Optimization | 4.00% |
| $850,000 Gross Receipts / Assets | $34,000 Franchise / UBT / PTET | $34,808 SE / SALT Shield | $808/yr Net Optimization | 4.00% |
| $1,250,000 Gross Receipts / Assets | $50,000 Franchise / UBT / PTET | $34,808 SE / SALT Shield | $450/yr Net Optimization | 4.00% |
| $2,250,000 Gross Receipts / Assets | $90,000 Franchise / UBT / PTET | $34,808 SE / SALT Shield | $450/yr Net Optimization | 4.00% |
| $5,000,000 Gross Receipts / Assets | $200,000 Franchise / UBT / PTET | $34,808 SE / SALT Shield | $450/yr Net Optimization | 4.00% |
2026 Reference Benchmark Scenarios & Worked Case Audits
The table and worked case audits below document the primary 2026 statutory benchmark profiles pre-loaded into the simulator above, along with the governing tax or regulatory schedule applied to each tier:
| 2026 Benchmark Profile | Primary Input Configuration | Governing Statutory Rule & Form | Audit & Planning Impact |
|---|---|---|---|
| Tier 1: $260k NY State S-Corp + PTET | PROFIT: $260,000 · SALARY: $110,000 · STATE: ny | Small Business Tax · FICA & NYS PTET · 2026 Schedule | Click the $260k NY State S-Corp + PTET preset button above to load exact 2026 outputs. |
| Tier 2: $320k NYC Resident (8.85% GCT Trap) | PROFIT: $320,000 · SALARY: $135,000 · STATE: nyc | Small Business Tax · FICA & NYS PTET · 2026 Schedule | Click the $320k NYC Resident (8.85% GCT Trap) preset button above to load exact 2026 outputs. |
| Tier 3: $400k New Jersey S-Corp + BAIT | PROFIT: $400,000 · SALARY: $150,000 · STATE: nj | Small Business Tax · FICA & NYS PTET · 2026 Schedule | Click the $400k New Jersey S-Corp + BAIT preset button above to load exact 2026 outputs. |
| Custom Stress-Test Scenario | Interactive Touch Sliders + − / + Steppers |
Real-Time 60fps Marginal & Effective Calculation | Exportable via ✉️ Email Worksheet, 📊 Export CSV, or parameterized URL link. |
$260k NY State S-Corp + PTET
Configured with PROFIT=$260,000, SALARY=$110,000, STATE=ny under Small Business Tax · FICA & NYS PTET. Selecting this preset above automatically populates all sliders, recalculates the 2026 annual, quarterly, monthly, and bi-weekly schedule, and unlocks 1-click CPA worksheet export.
$320k NYC Resident (8.85% GCT Trap)
Configured with PROFIT=$320,000, SALARY=$135,000, STATE=nyc under Small Business Tax · FICA & NYS PTET. Selecting this preset above automatically populates all sliders, recalculates the 2026 annual, quarterly, monthly, and bi-weekly schedule, and unlocks 1-click CPA worksheet export.
$400k New Jersey S-Corp + BAIT
Configured with PROFIT=$400,000, SALARY=$150,000, STATE=nj under Small Business Tax · FICA & NYS PTET. Selecting this preset above automatically populates all sliders, recalculates the 2026 annual, quarterly, monthly, and bi-weekly schedule, and unlocks 1-click CPA worksheet export.
Line-by-Line Statutory Reconciliation & Filing Workflow
When applying the outputs of the LLC vs. S-Corp Self-Employment & NY PTET Tax Savings Calculator to a real-world tax return, real estate closing disclosure, or commercial loan underwriting package in NY · NJ · CT, practitioners follow a four-step verification protocol:
- Establish the Gross Statutory Base vs. Adjusted Base: Separate gross contract figures (W-2 Box 1 wages, gross sale price, or total loan commitment) from pre-tax adjustments (401(k)/HSA salary deferrals, adjusted cost basis under IRC § 1011, or existing unpaid principal assigned via NY Tax Law § 255 CEMA).
- Apply Progressive Marginal Brackets & Cliff Thresholds: While federal and state income tax brackets operate marginally, several East Coast transfer taxes—most notably the NYC Mansion Tax (1.00% to 3.90% on purchases ≥ $1,000,000), the NJ 1% Buyer Mansion Tax, the PA/Philadelphia 4.278% Realty Transfer Tax, and the NYS Supplemental Estate Tax Cliff (100%–105% phase-out zone)—operate as retroactive or cliff thresholds where crossing a dollar boundary alters the liability on the entire base.
- Reconcile Annual, Quarterly, Monthly & Bi-Weekly Cash Flows: Use the 2026 Multi-Horizon Statutory Schedule Table generated inside the calculator above to align bi-weekly payroll withholdings (26 pay periods), quarterly estimated tax vouchers (April 15, June 15, September 15, January 15), and monthly PITI/DSCR debt-service covenants.
- Archive Parameterized Evidence for CPA & Legal Review: Click ✉️ Email Worksheet to Me / CPA, 🔗 Copy Custom Scenario Link, or 📊 Export CSV Breakdown to preserve your exact input vector alongside your supporting IRS, NYS DTF, NYC Department of Finance, NJ Division of Taxation, or lender closing statements.
Official IRS & State Tax Form Line-by-Line Audit Trail (v2026.11)
For CPA workpaper verification, legal closing disclosures, and statutory compliance audits across NY · NJ · CT, Table 3 maps every calculation layer in the LLC vs. S-Corp Self-Employment & NY PTET Tax Savings Calculator to its exact 2026 federal and state tax form line:
| Simulator Calculation Layer | Federal IRS Form & Line Reference | East Coast State / Municipal Form & Schedule | Statutory Audit & Reconciliation Rule |
|---|---|---|---|
| Gross Business Receipts, Net Ordinary Income & Assets | IRS Form 1120-S (S-Corp) · Form 1065 (Partnership) · Schedule C (SMLLC) | 8 Del. C. § 503 Franchise Report · NYC Form NYC-202 / NYC-204 (4% UBT) · NY DOS § 206 Certificate of Publication | Establishes entity tax base, authorized vs. issued shares, gross assets, and tri-state nexus apportionment. |
| Reasonable W-2 Officer Compensation vs. K-1 Distributions | IRS Form 1120-S Line 7 · Form W-2 · Schedule K-1 (Form 1120-S) Box 1 | NYS Form MTA-305 / MCTMT Payroll Mobility Tax (Zone 1 0.60%) · State UI/SUTA Wage Base | Balances 15.3% SECA payroll tax savings on K-1 distributions against IRC § 199A QBI 20% deduction and NYC 8.85% GCT. |
| Pass-Through Entity Tax (PTET) Federal SALT Workaround | IRS Notice 2020-75 Entity-Level Deduction (Form 1120-S Line 12 / Form 1065 Line 14) | NYS Article 24-A PTET · NJ BAIT (Form PTE-100) · CT Form CT-1065/CT-1120SI (6.99%) · MA 63D · VA PTET (5.75%) | Converts nondeductible personal state income tax above the $10,000 Schedule A SALT cap into a 100% deductible business expense. |
- Release v2026.11 (Current Production): Synchronized all 16 East Coast state parameter vectors with
IRS Rev. Proc. 2025-32,SSA $176,100 OASDI Wage Base,MA $1,083,150 Millionaire Surtax Threshold,NYS $7,160,000 Estate Tax Exclusion,NC 3.99% / GA 5.19% Flat Rate Reductions, andNH 0% I&D Repeal. Added 1-click Markdown/CSV/CPA audit export and open-data verification (Download 2026 CSV Dataset · Frictionless Data Schema · JSON REST API). - Release v2026.06: Expanded statutory matrix to 50 interactive calculators across all 16 Atlantic corridor jurisdictions (ME, NH, VT, MA, RI, CT, NY, NJ, PA, DE, MD, DC, VA, NC, SC, GA, FL) with 26-period bi-weekly, monthly, quarterly, and annual cash-flow reconciliation.
- Release v2025.10: Initial Tri-State (NY/NJ/CT), Pennsylvania, Massachusetts, and Florida statutory simulation release verified by Lead Quantitative Architect Pablo Cirre Gómez and Senior Statutory Compliance Editor Enrique Zarza, Esq. (ICAM Bar No. 68.400).
Frequently Asked Questions: LLC vs. S-Corp Self-Employment & NY PTET Tax Savings Calculator (2026 Statutory Rules)
How accurate is the LLC vs. S-Corp Self-Employment & NY PTET Tax Savings Calculator for 2026 tax and financial filings in NY · NJ · CT?
The LLC vs. S-Corp Self-Employment & NY PTET Tax Savings Calculator is calibrated directly to 2026 primary statutory schedules (Small Business Tax · FICA & NYS PTET), incorporating current IRS Revenue Procedure inflation adjustments, FICA wage base limits ($176,100 Social Security cap plus 0.9% Additional Medicare Tax above $200,000/$250,000), and state/municipal brackets across NY · NJ · CT. Every output updates at 60fps in your browser and can be exported to CSV or PDF for CPA audit verification.
What statutory forms and legal citations govern the LLC vs. S-Corp Self-Employment & NY PTET Tax Savings Calculator in 2026?
Calculations in this simulator follow Small Business Tax · FICA & NYS PTET alongside applicable 2026 state department of revenue instructions across NY · NJ · CT. Practitioners use the generated Multi-Horizon Statutory Schedule (annual, quarterly, monthly, and bi-weekly rows) to cross-check withholding elections, estimated tax vouchers (April 15, June 15, September 15, and January 15), and closing disclosure settlement statements.
How do marginal bracket cliffs and phase-outs affect my LLC vs. S-Corp Self-Employment & NY PTET Tax Savings Calculator calculation?
Unlike flat-rate estimators, East Coast jurisdictions enforce steep statutory cliffs—including the NYC Mansion Tax tiers ($1M to $25M+), the NY Supplemental Tax rate recapture on high earners, the NY $7.16M Estate Tax Cliff (100%–105% phase-out range), the Massachusetts 4% Millionaire Surtax above $1,083,150, and South Carolina Act 388 4% vs. 6% property assessment ratios. Use the 10-Tier Sensitivity Table on this page to identify where crossing a threshold alters your effective rate.
Can I email or export a customized LLC vs. S-Corp Self-Employment & NY PTET Tax Savings Calculator worksheet to my CPA, attorney, or lender?
Yes. Click "✉️ Email Worksheet to Me / CPA" inside the calculator toolbar to send a formatted 2026 statutory breakdown directly to your inbox or advisor, click "📊 Export CSV Breakdown" to open the line-by-line schedule in Excel or Google Sheets, or click "🔗 Copy Custom Scenario Link" to share a parameterized URL that restores your exact slider configuration.
How does NY · NJ · CT compare against neighboring I-95 East Coast corridors in 2026?
Within the 16-state East Coast corridor, effective tax and carrying burdens vary by up to 14.776% on earned income and over 4.278% on real estate transfers. Reviewing the interactive I-95 Zone Map and companion deep-dive study linked on this page lets you benchmark NY · NJ · CT directly against New England (MA, NH, CT), Tri-State (NYC, NJ), Mid-Atlantic (PA, DE, MD, DC, VA), and Southeast (NC, SC, GA, FL) alternatives.
Is any personal or financial data stored when I run scenarios in the LLC vs. S-Corp Self-Employment & NY PTET Tax Savings Calculator?
No. All mathematical formulas execute 100% client-side in your browser using deterministic JavaScript. No salary, property value, balance sheet, or tax figures are transmitted to external servers unless you explicitly request an emailed worksheet copy.
Compare Adjacent Jurisdictions & Companion Calculators (NY · NJ · CT)
Pablo Cirre Gómez
Corporate database analyst, financial publisher, and digital economist with 20+ years of experience building quantitative business intelligence, fiscal simulation engines, and corporate registries (Co-Founder of East Corp Capital, Diario Económico, and Legia.es). Accredited in Business & Marketing Systems (COM708_3, IFC297_2), lecturer at the International Graduate School (EIP) and Cámara de Comercio, and lead architect of our 50 interactive IRS, NYS DTF, NJ Treasury, Mass. DOR, PA DOR, FL DOR, and Federal Reserve calculators and 78 quantitative studies across all 16 East Coast states.
Enrique Zarza (José Enrique Rodríguez Zarza), Esq.
Practicing litigation, banking, real estate, and corporate compliance attorney admitted to the Illustrious Bar Association of Madrid (ICAM No. 68.400) with over 25 years of professional practice. Law Degree & Master in Legal Practice (Universidad de Granada), Executive Management (San Telmo Business School), pioneer in digital banking contracting (CaixaBank / CTI Soluciones), Founder of ICIRED, former Managing Director of the Judicial Default Registry (RIJ) partnered with the General Council of Spanish Lawyers (Abogacía Española), and Co-Founder of Legia.es, Diario Económico, and East Corp Capital. Audits all statutory citations against primary U.S. federal (IRS, Treasury, Fed) and 16-state revenue publications.
irs.gov, treasurydirect.gov, federalreserve.gov, ssa.gov) and state (tax.ny.gov, nyc.gov/site/finance, nj.gov/treasury, mass.gov, revenue.pa.gov, corp.delaware.gov, floridarevenue.com) publications. Open-data verification: 2026 Master CSV · datapackage.json · CITATION.cff..gov) publications. Always consult a licensed U.S. Certified Public Accountant (CPA), Enrolled Agent (EA), or tax attorney admitted in your specific state before executing tax filings or real estate closings. See our Methodology & Sources and Corrections Policy.How the LLC vs. S-Corp Self-Employment & NY PTET Tax Savings Calculator Computes 2026 Statutory Liability
The LLC vs. S-Corp Self-Employment & NY PTET Tax Savings Calculator is a deterministic client-side quantitative model engineered by Pablo Cirre Gómez and legally audited by Enrique Zarza, Esq. (ICAM Bar No. 68.400) for the NY · NJ · CT jurisdiction cluster. Specifically, this engine models: Compares single-member LLC self-employment tax (15.3%) against an S-Corp reasonable salary split plus the New York Pass-Through Entity Tax (PTET) federal SALT bypass.
- Scenario A vs. Scenario B Pinning: Click
⚖️ Pin Scenario A to Compareinside the simulator above to lock your baseline 2026 parameters, then drag any slider to measure the exact dollar and effective-rate delta across jurisdictions or filing structures. - 2026 Statutory Calendar (.ics) & CPA Worksheet Export: Export an RFC 5545
.icstax deadline file or a line-by-line CSV/Markdown audit schedule pre-populated with your exact simulated figures for LLC vs. S-Corp Self-Employment & NY PTET Tax Savings Calculator.
Standard Press, Substack, Reddit & CPA Attribution (100% Human-Authored & Attorney-Reviewed):
According to East Corp Capital’s 2026 Quantitative Study ("LLC vs. S-Corp & NY PTET Tax Calculator (2026): Self-Employment & SALT Savings", authored by Pablo Cirre Gómez and legally reviewed by Enrique Zarza, Esq., ICAM Bar No. 68.400, https://eastcorpcapital.com/calculators/llc-scorp/)