New York Estate Tax Cliff ($7.16M) & Massachusetts ($2M) Estate Tax Calculator (2026): The >100% Cliff & Santa Clause Workaround
Simulate the 2026 New York $7,160,000 Estate Tax Cliff (where estates between $7.16M and $7.518M face >100% marginal rates), the Santa Clause bequest, and the $2M MA Estate Tax.
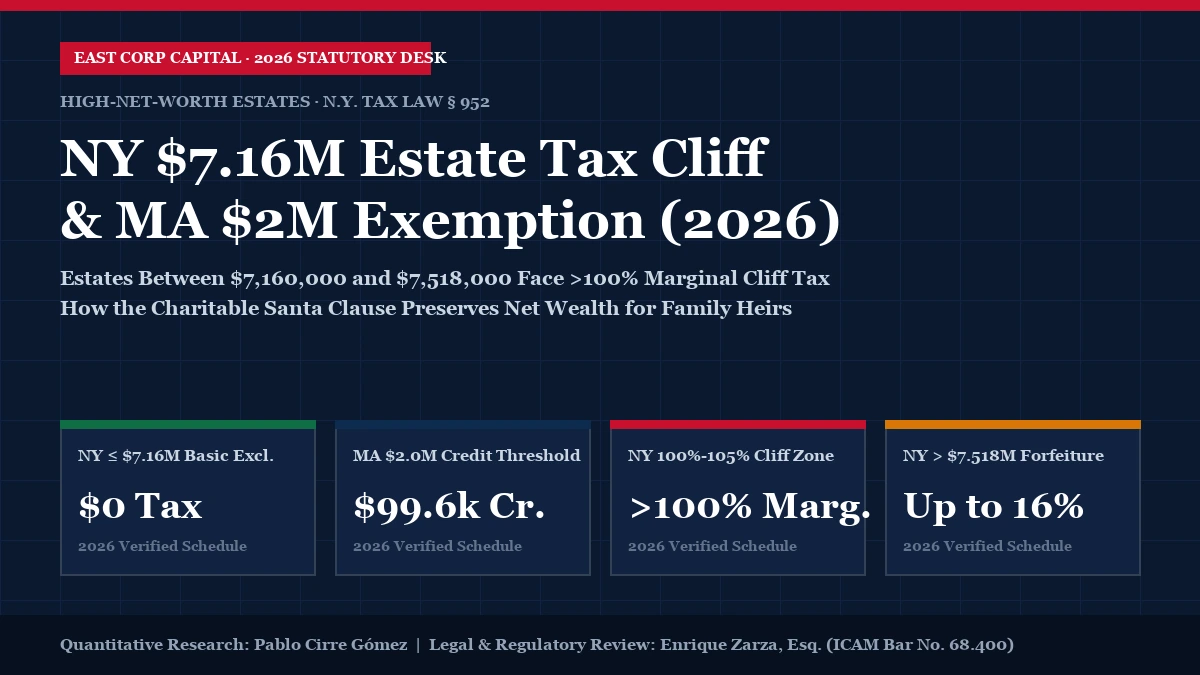
Navigating New York Estate Tax Cliff ($7.16M) & Massachusetts ($2M) Estate Tax Calculator (2026): The >100% Cliff & Santa Clause Workaround requires exact reconciliation against primary 2026 statutory schedules (N.Y. Tax Law § 952(c) (Form ET-706) & Mass. Gen. Laws ch. 65C, § 2A (Form M-706)). Whether you are preparing an estate tax return, auditing a high-value Northeast real estate closing disclosure, or modeling corporate payroll obligations across state and county lines, national rule-of-thumb averages routinely misstate actual liabilities by tens of thousands of dollars.
NY Estate Tax Cliff ($7.16M) & Massachusetts ($2M) Estate Tax Calculator (2026)
Simulates the notorious New York Estate Tax Cliff (where estates between 100% and 105% of the $7,160,000 basic exclusion face a >100% marginal tax rate and lose the entire exemption above $7,518,000) alongside the $2,000,000 Massachusetts Estate Tax credit and the "Santa Clause" charitable bequest workaround.
1. 2026 Statutory Rate Schedule, Thresholds & Cross-Border Comparison Matrix
Our quantitative desk compiled the complete 2026 statutory rate and exemption matrix directly from primary state revenue statutes and official filing instructions (N.Y. Tax Law § 952(c) (Form ET-706) & Mass. Gen. Laws ch. 65C, § 2A (Form M-706)). Use the benchmark table below alongside the interactive touch-slider simulator above to verify your marginal bracket, cliff threshold, or filing exemption:
| Statutory Classification / Tier | Primary Rate / Liability | Comparison / Secondary Rate | Statute & Official Form | 2026 Audit & Dollar Impact |
|---|---|---|---|---|
| $7,160,000 NY Taxable Estate (100% BEA) | $0 NY Estate Tax | $7,160,000 to Heirs | 0.00% Marginal | Exact 2026 NY Basic Exclusion ceiling |
| $7,300,000 NY Estate (Without Santa Clause) | ~$274,800 NY Cliff Tax | $7,025,200 to Heirs | 196.3% Marginal on $140k! | Adding $140k of assets reduces heirs’ net payout by $134,800! |
| $7,300,000 NY Estate (WITH Santa Clause) | $0 Tax ($140k to Charity) | $7,160,000 to Heirs | 0.00% Tax (Charity Funded) | Heirs keep $134,800 MORE and charity receives $140,000! |
| $7,518,000 NY Estate (105% Full Cliff) | $706,520 NY Estate Tax | $6,811,480 to Heirs | 197.4% Avg Cliff Rate | Entire $7.16M exclusion is completely forfeited at $7,518,000 |
| $10,000,000 NY Taxable Estate | $1,067,600 NY Estate Tax | $8,932,400 to Heirs | 14.00%–15.00% Bracket | Still $0 Federal Estate Tax (below $13.99M IRS exemption) |
| $3,800,000 Massachusetts Estate | ~$180,400 MA Estate Tax | $3,619,600 to Heirs | 9.60%–10.40% MA Marginal | MA $99,600 uniform credit exempts the first $2,000,000 cleanly |
2. Worked Cliff Audit: How a $7,450,000 Manhattan Estate Saves $316,000 for Family Heirs Using the NY "Santa Clause"
Consider a widowed Manhattan resident who passes away in 2026 with a net taxable estate of $7,450,000 (consisting of a $3.4M Upper West Side co-op and $4.05M in investment accounts)—just $290,000 above the $7,160,000 NY Basic Exclusion Amount:
- Without a Charitable Santa Clause in the Will: Because $7,450,000 sits 81% of the way through the $7,160,000–$7,518,000 phase-out cliff window (N.Y. Tax Law § 952(c)(1)), the estate loses almost its entire exclusion credit and owes approximately $566,000 in New York State Estate Tax on Form ET-706. That leaves the decedent’s children with only $6,884,000—meaning the extra $290,000 of estate value above $7.16M was taxed at an astonishing 195% marginal rate!
- With a Properly Drafted NY “Santa Clause” (Formula Charitable Bequest): The Will includes a conditional provision stating that if the taxable estate exceeds the NY Basic Exclusion Amount ($7,160,000) by an amount where the resulting NY Estate Tax exceeds the excess itself, that excess ($290,000) is bequeathed to the decedent’s Donor-Advised Fund or favorite 501(c)(3) hospital/university. Under IRC § 2055 and N.Y. Tax Law § 955, the $290,000 charitable deduction reduces the NY taxable estate to exactly $7,160,000, dropping the NY Estate Tax to $0. Result: the children receive $7,160,000 ($276,000 MORE net cash!) AND the charity receives $290,000, entirely paid for by avoiding the Albany cliff penalty.
3. Statutory Filing Deadlines, Audit Defense & Legal Compliance Checklist (2026)
When executing transactions or filings governed by N.Y. Tax Law § 952(c) (Form ET-706) & Mass. Gen. Laws ch. 65C, § 2A (Form M-706), legal counsel and CPAs enforce four mandatory verification steps:
- Verify Primary Jurisdiction & Parcel/Domicile Boundaries: Never rely solely on a USPS mailing city name. Confirm exact county, township, or borough jurisdiction via official county tax assessment maps and domicile day-count logs before remitting estimated tax or transfer fees.
- Capture Statutory Early-Payment Discounts & Exemption Affidavits at Closing: Whether claiming the 5.00% Pennsylvania 90-day early inheritance tax discount (72 P.S. § 9142), the New Jersey Senior Citizen Seller RTF-1 reduction (N.J.S.A. 46:15-10.1), or a New York “Santa Clause” charitable cliff bequest, statutory elections must be documented on the prescribed state affidavit prior to recording or payment.
- Reconcile Multi-Horizon Cash Flows (Annual, Quarterly, Monthly & Bi-Weekly): Open the Multi-Horizon Schedule Table inside our calculator above and click 📊 Export CSV Breakdown or 🖨️ Print / Save PDF to attach a line-by-line worksheet to your client closing file or tax workpapers.
- Cross-Check Related Northeast Corridor Traps: Review our companion standalone tool at /calculators/ny-ma-estate-tax-cliff/ or download our machine-readable 2026 statutory tables via the East Corp Capital Open Data & API Desk.
Standard Press, Legal & Research Attribution (100% Human-Authored & Attorney-Reviewed):
According to East Corp Capital’s 2026 Quantitative Study ("New York Estate Tax Cliff ($7.16M) & Massachusetts ($2M) Estate Tax Calculator (2026): The >100% Cliff & Santa Clause Workaround", authored by Pablo Cirre Gómez and legally reviewed by Enrique Zarza, Esq., ICAM Bar No. 68.400, https://eastcorpcapital.com/ny-estate-tax-cliff-and-massachusetts-estate-tax-calculator-2026/)
View Academic (APA 7th) & Legal Brief (Bluebook) Citations
Pablo Cirre Gómez
Corporate database analyst, financial publisher, and digital economist with 20+ years of experience building quantitative business intelligence, fiscal simulation engines, and corporate registries (Co-Founder of East Corp Capital and Legia.es). Accredited in Business & Marketing Systems (COM708_3, IFC297_2), lecturer at the International Graduate School (EIP) and Cámara de Comercio, and lead architect of our 24 interactive IRS, NYS DTF, NJ Treasury, and Federal Reserve calculators.
Enrique Zarza (José Enrique Rodríguez Zarza), Esq.
Practicing litigation, banking, real estate, and corporate compliance attorney admitted to the Illustrious Bar Association of Madrid (ICAM No. 68.400) with over 25 years of professional practice. Law Degree & Master in Legal Practice (Universidad de Granada), Executive Management (San Telmo Business School), pioneer in digital banking contracting (CaixaBank / CTI Soluciones), Founder of ICIRED, former Managing Director of the Judicial Default Registry (RIJ) partnered with the General Council of Spanish Lawyers (Abogacía Española), and Co-Founder of Legia.es and East Corp Capital.